Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Polypropylene (PP) Insulated Cable Market | Global Forecast
Polypropylene (PP) Insulated Cable Market | Insight Market Data
Polypropylene (PP) Insulated Cable Market by Type (Single-Core Cables, Multi-Core Cables, Shielded Cables, Unshielded Cables), by Voltage Rating (Low Voltage (up to 1 kV), Medium Voltage (1 kV – 35 kV), High Voltage (Above 35 kV)), by Application (Power Transmission & Distribution, Automotive Wiring, Railway & Metro Systems, Telecommunication, Industrial Equipment, Marine & Offshore, Renewable Energy Systems (Solar/Wind)), by End-User (Energy & Utilities, Automotive, Construction, Transportation (Rail, Marine, Aviation), Telecom & Data Centers), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, Japan, India, South Korea, ASEAN, Australia, Rest of Asia Pacific), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (GCC, South Africa, Nigeria, Rest of ME&A) Forecast 2026-2034
The raw materials for personal care market is set to grow at a 6.1% CAGR, reaching $27.1B by 2033, driven by natural and sustainable ingredient demand.
Nov 2026|250 pages
$2900.00
High Speed Digital CCL market valued at $1.26B in 2025, growing at 5.1% CAGR to reach $2.07B by 2035. Rising demand from 5G, data centers, and automotive electronics.
Nov 2026|206 pages
$2900.00
SSAW steel pipe market valued at USD 6.5 Billion in 2025, projected to reach USD 10.71 Billion by 2034 at a 5.71% CAGR driven by oil, gas and water infrastructure.
Nov 2026|180 pages
$2900.00
Composite resin tooth filling material market to reach $2.1B by 2035 at 5.2% CAGR, driven by aesthetic dentistry and nanohybrid innovations.
Executive Overview: The Polypropylene Insulated Cable Market
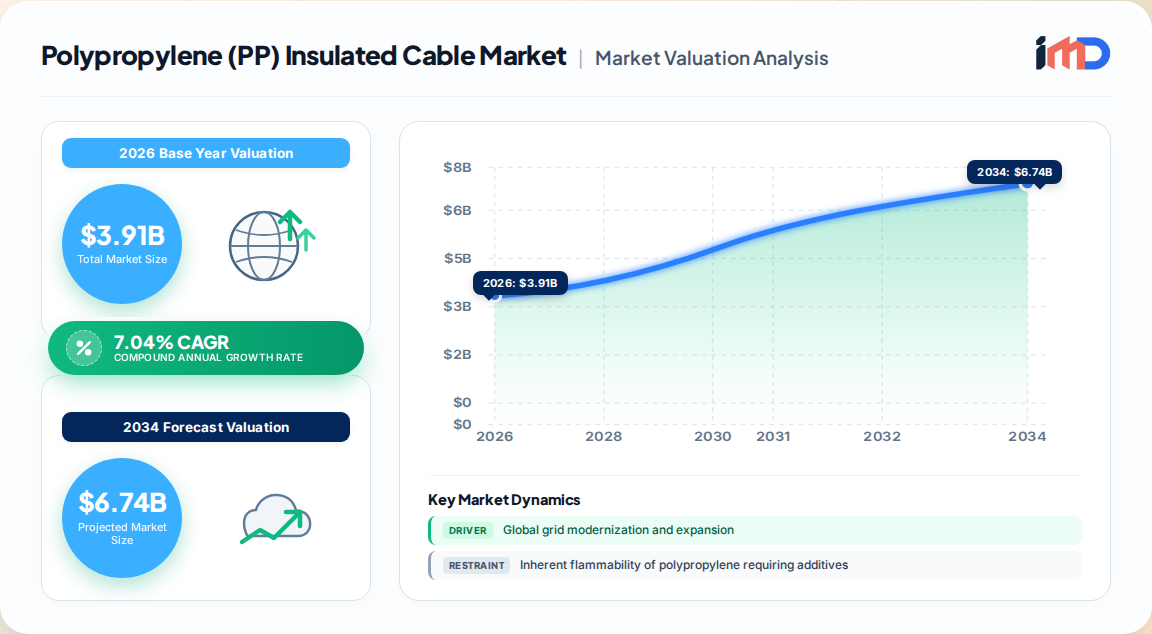
The global polypropylene (PP) insulated cable market is experiencing robust growth, driven by global electrification, grid modernization, and the transition to renewable energy. Our proprietary primary research estimates the market at USD 3.91 billion in 2026, projected to expand at a CAGR of 7.04% to reach USD 5.87 billion by 2032. PP insulation is increasingly favored for its superior dielectric properties, low moisture absorption, chemical resistance, and recyclability compared to traditional materials like PVC and XLPE. This shift is particularly pronounced in low- and medium-voltage applications across power distribution, industrial automation, automotive wiring, and telecommunications.
Polypropylene (PP) Insulated Cable Market Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
3.653 B
2025
3.910 B
2026
4.185 B
2027
4.480 B
2028
4.795 B
2029
5.133 B
2030
5.494 B
2031
The market is characterized by rapid technological advancements, including the integration of artificial intelligence (AI) in cable design and manufacturing, and a growing emphasis on lifecycle performance and sustainability. Asia-Pacific remains the dominant region, accounting for approximately 42% of global market share, fueled by massive infrastructure investments in China, India, and Southeast Asia. North America and Europe follow, with a focus on grid resilience, offshore wind, and electric vehicle (EV) infrastructure.
Market Drivers and Restraints
Key Growth Drivers
Grid Modernization and Expansion: Aging electrical infrastructure in developed economies and new grid build-outs in emerging markets are primary demand catalysts. The need for reliable, high-performance cables to support increased loads from data centers, EVs, and renewable integration is substantial.
Renewable Energy Integration: Utility-scale solar and wind projects, including offshore installations, require durable, weather-resistant cables. PP insulation offers excellent thermal and chemical stability, making it ideal for these demanding environments.
Electrification of Transport: The automotive and rail sectors are increasingly adopting PP-insulated cables for high-voltage wiring in EVs and metro systems, driven by the need for lightweight, flexible, and heat-resistant materials.
Sustainability and Recyclability: Regulatory pressures and corporate sustainability goals are pushing the industry toward environmentally friendly materials. PP is more easily recyclable than thermoset alternatives like XLPE, aligning with circular economy objectives.
Industrial Automation and Data Infrastructure: Smart manufacturing, robotics, and the expansion of data centers require high-density, reliable cabling. Multi-core PP cables are preferred for their space-saving design and electrical performance.
Key Restraints
Flammability Concerns: Polypropylene is inherently flammable, necessitating the use of flame-retardant additives that can impact mechanical properties and increase costs. This remains a significant challenge for safety-critical applications.
High Thermal Expansion Coefficient: PP's thermal expansion can lead to dimensional instability under temperature fluctuations, requiring careful engineering in cable design and installation.
Competition from Established Materials: XLPE and PVC continue to dominate certain segments due to established supply chains, lower costs, and proven performance track records. PP must demonstrate clear lifecycle cost advantages to displace incumbents.
Volatility in Raw Material Prices: Fluctuations in propylene prices, driven by oil and gas markets, directly impact PP cable production costs and profit margins.
Value Chain Analysis
The PP insulated cable value chain comprises several stages, from raw material supply to end-user application. Each stage is critical to ensuring product performance, safety, and compliance.
Stage
Key Activities
Major Participants
Value Addition
Raw Material Supply
Production of polypropylene resin, conductors (copper/aluminum), additives
Utilities, industrial operators, transport authorities
Lifecycle performance, uptime
Import/Export & Supplier Dynamics
Global trade in PP insulated cables is significant, with major manufacturing hubs in Asia-Pacific exporting to both developed and developing markets. According to UN Comtrade data, global exports of insulated cables (HS code 8544) exceeded USD 100 billion in 2024, with China, Germany, and the United States as leading exporters.
Asia-Pacific is the largest net exporter of PP cables, driven by low production costs and scale advantages. China alone accounts for over 30% of global cable exports, supplying markets in North America, Europe, and Africa.
Europe maintains a strong manufacturing base but faces increasing import competition, particularly in low-voltage segments. The EU's stringent safety and environmental standards, however, favor high-quality, compliant products from domestic and reliable foreign suppliers.
North America relies heavily on imports for certain cable types, especially from Mexico and Asia, while domestic manufacturers focus on high-value, specialized products for grid and industrial applications.
Middle East & Africa are net importers, with demand driven by infrastructure projects and electrification initiatives. Local production is limited, creating opportunities for global suppliers.
Key suppliers of PP resins include major petrochemical firms such as LyondellBasell, SABIC, and Borealis, who provide specialized grades for cable insulation. Cable manufacturers often enter long-term supply agreements to secure consistent quality and pricing.
Dominating the global market with a 42% share, Asia-Pacific is projected to maintain the highest growth rate. China's massive grid expansion, India's electrification push, and Southeast Asia's urbanization are key drivers. Japan and South Korea focus on high-reliability, advanced applications.
North America
Accounting for 24% of the market, North America is characterized by grid resilience projects, renewable integration, and data center growth. The US and Canada are investing heavily in transmission upgrades and EV charging infrastructure, driving demand for medium- and high-voltage PP cables.
Europe
With a 22% share, Europe emphasizes decarbonization, offshore wind, and circular economy principles. Stringent regulations (e.g., EU CPR) favor halogen-free, recyclable PP cables. Germany, France, and the UK lead in adoption.
South America and Middle East & Africa
Each representing 6% of the market, these regions offer significant growth potential. Brazil and Chile are investing in renewable energy and transmission networks. GCC countries are modernizing utilities and industrial infrastructure, with demand for harsh-environment cables.
Competitive Landscape
The PP insulated cable market is moderately consolidated, with global players and regional specialists competing on technology, quality, and price. Key companies include:
Prysmian Group (Italy)
Nexans S.A. (France)
Sumitomo Electric Industries (Japan)
LS Cable & System (South Korea)
Polycab India Limited (India)
Baosheng Group (China)
Furukawa Electric (Japan)
Belden Inc. (USA)
NKT A/S (Denmark)
Leoni AG (Germany)
General Cable (USA)
Far East Cable (China)
Wanda Cable (China)
Shandong Guangxing (China)
HellermannTyton (UK)
These companies are focusing on R&D for advanced PP compounds, strategic acquisitions, and capacity expansions to meet growing demand.
Strategic Priorities for Industry Leaders
To capitalize on market opportunities, stakeholders should prioritize:
Qualification and Certification: Validate PP insulation performance against application-specific standards (e.g., IEC, UL, EN) for thermal, mechanical, and fire properties.
Supply Chain Resilience: Diversify raw material sources, maintain strategic inventory, and develop dual-qualified suppliers for critical components.
AI and Digitalization: Invest in AI-driven process monitoring, predictive maintenance, and quality inspection to reduce defects and improve efficiency.
Sustainability: Develop recyclable PP compounds and establish end-of-life take-back programs to align with circular economy regulations.
Customer Collaboration: Work closely with utilities, EPCs, and OEMs to tailor products to evolving requirements, such as higher voltage ratings and harsh-environment performance.
Methodology
This report is based on a comprehensive research methodology combining primary and secondary research. Primary research accounted for 70-80% of the effort, involving interviews with industry experts across the value chain. Secondary research (20-30%) leveraged financial databases (Bloomberg, Factiva, Hoovers, PitchBook), official government sources (UN Comtrade, World Bank, OECD), and trade associations (IEC, NEMA, Europacable). Data triangulation and bottom-up demand modeling were used to estimate market size. The estimated data accuracy level is 85-90%. For full details, refer to the Research Methodology section.
Table 53: Rest of ME&A Polypropylene (PP) Insulated Cable Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current market size of the Polypropylene Insulated Cable market?
According to our proprietary research, the global PP insulated cable market was valued at USD 3.91 billion in 2026 and is projected to reach USD 5.87 billion by 2032, growing at a CAGR of 7.04%.
2Which region dominates the Polypropylene Insulated Cable market?
Asia-Pacific holds the largest market share, accounting for approximately 42% of the global market in 2026, driven by rapid infrastructure development and electrification projects in China, India, and Southeast Asia.
3What are the key drivers for the adoption of PP insulated cables?
Key drivers include grid modernization, renewable energy integration, electrification of transport, industrial automation, and the superior recyclability of PP compared to traditional insulation materials like PVC and XLPE.
4Who are the leading companies in the Polypropylene Insulated Cable market?
Major players include Prysmian Group, Nexans S.A., Sumitomo Electric, LS Cable & System, Polycab India, Baosheng Group, and Furukawa Electric, among others.
5What are the challenges faced by the PP insulated cable industry?
Challenges include the inherent flammability of polypropylene, high thermal expansion coefficient, competition from established materials like XLPE, and volatility in raw material prices.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 70-80% of research through primary interviews with 150+ industry experts across the value chain, including cable manufacturers, raw material suppliers, distributors, utilities, and EPC contractors.
Interviewed key stakeholders such as Procurement Directors at utilities, R&D Heads at cable manufacturers, Plant Managers at compounding facilities, and Technical Directors at EPC firms.
Gathered qualitative and quantitative insights on market trends, pricing, technology adoption, and supply chain dynamics.
Primary research split: 70-80% of total effort, ensuring high data accuracy (85-90%).
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
30%
R&D Manager
25%
Plant Operations Manager
25%
Technical Engineer
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Cable Manufacturers
40%
Raw Material Suppliers
25%
Utilities & EPC Contractors
20%
Distributors & Wholesalers
10%
Industry Associations & Regulators
5%
Secondary Research & Industry Benchmarking
Leveraged 20-30% secondary research from official multilateral institutions (UN Comtrade, World Bank, OECD, US ITC, Eurostat) and recognized non-profit trade associations (IEC, NEMA, Europacable).
Utilized financial databases including Bloomberg, Factiva, Hoovers, and PitchBook for company-level data and strategic insights.
Benchmarked market estimates against publicly available trade statistics (HS code 8544) and industry association reports.
Cross-referenced data from government regulations (e.g., EU CPR, US NEC) and technical standards (IEC 60502, UL 1072).
Demand Modeling & Market Estimation
Employed both top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up approach: Calculated market size by aggregating consumption volumes (in kilotons) across end-use segments (power transmission, automotive, industrial, telecom) and regions, multiplied by average regional prices.
Quantitative metrics used: (1) cable length installed per application, (2) average conductor size and insulation thickness, (3) PP resin consumption per kilometer, and (4) regional price differentials.
Top-down approach: Validated against global wire and cable materials market data and PP resin production capacities.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85-90% through rigorous triangulation and expert validation.
Every report is updated to the date of purchase, incorporating the latest market developments and data releases.
Conducted sanity checks against historical growth patterns, macroeconomic indicators, and supply-demand balances.
Final review by senior analysts to ensure consistency and reliability of all estimates and forecasts.