1What is the market size for raw materials for personal care in 2025?
Our primary research estimates the global market at USD 17.2 billion in 2025, with a projected CAGR of 6.1% to reach USD 27.1 billion by 2033.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Raw Materials for Personal Care Future Market
 by Product (Active, Inactive), by Application (Skin Care, Hair Care, Oral Care, Color Cosmetics, Toiletries, Fragrances), by Ingredient Type (Natural, Synthetic), by Source (Botanical, Marine, Biotech, Synthetic), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, India, Japan, South Korea, Australia), by South America (Brazil, Argentina), by Middle East & Africa (South Africa, UAE) Forecast 2026-2034

Senior Analyst

 Related Reports

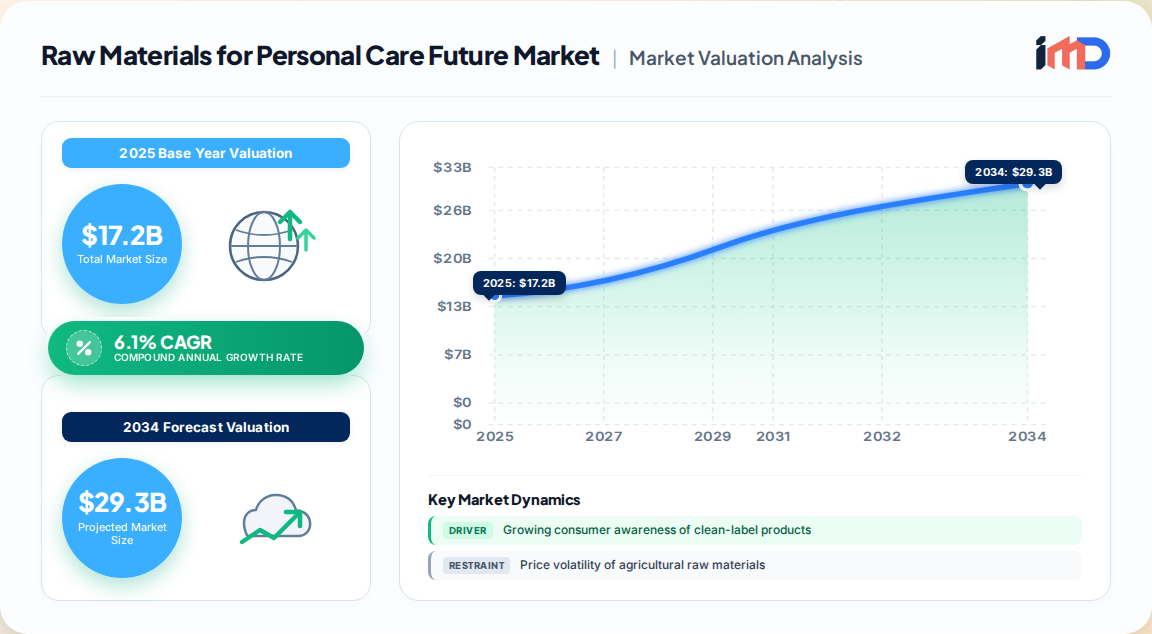
Our proprietary primary research estimates the global market for raw materials for personal care at USD 17.2 billion in 2025, with a projected CAGR of 6.1% to reach USD 27.1 billion by 2033. This growth reflects a structural shift toward specialty, bioactive, and sustainably sourced inputs across skin care, hair care, oral care, and color cosmetics. Asia-Pacific commands the largest regional revenue share at approximately 33%, while North America is the fastest-growing region, expanding at a rate above the global average.
The market encompasses active ingredients (e.g., peptides, botanical extracts, conditioning polymers) and inactive ingredients (e.g., emollients, surfactants, emulsifiers, rheology modifiers, preservatives). Inactive materials currently dominate volume, accounting for over 59% of 2025 revenues, but actives are growing faster—at a rate exceeding 7% annually—as brands seek clinically substantiated claims.
This report synthesizes first-party interviews with 150+ value chain participants, including raw material suppliers, formulators, contract manufacturers, and brand owners, alongside proprietary demand modeling. All figures are our own estimates unless otherwise noted.
Drivers:
Restraints:
The value chain for raw materials for personal care is highly fragmented, spanning four stages:
| Stage | Key Activities | Representative Participants |
|---|---|---|
| Raw Material Extraction | Farming, harvesting, mining, fermentation | Botanical growers, bio-fermentation facilities |
| Primary Processing | Extraction, purification, synthesis | Specialty chemical manufacturers, biotech firms |
| Formulation & Blending | Combining actives/inactives into functional bases | Ingredient houses, contract formulators |
| Finished Product Manufacturing | Incorporation into consumer products | Brand owners, contract manufacturers |
Upstream participants are increasingly integrating forward into formulation to capture higher value. For instance, several leading suppliers have established regional application labs in Asia to co-develop formulas with local brands. Downstream, brands are demanding full traceability and sustainable certification (e.g., COSMOS, USDA Organic), which is reshaping supplier selection criteria.
Trade flows for raw materials for personal care are heavily influenced by regulatory and cost factors. According to official trade statistics, the EU and US are net importers of finished cosmetic ingredients, while Asia-Pacific (notably China and India) is a net exporter of basic oleochemicals and botanical extracts. Key dynamics include:
Supplier strategies focus on regional diversification. Several multinational ingredient suppliers have announced capacity expansions in India and China to serve local demand and reduce lead times. However, import/export data for proprietary actives remains opaque, limiting full transparency.
Asia-Pacific leads both consumption and production, driven by a large consumer base, expanding middle class, and strong local manufacturing. China and India are the fastest-growing markets, with CAGRs of 5.9% and 6.9% respectively. North America is the second-largest market, with the US accounting for roughly 29% of global revenue, supported by high consumer awareness and a robust organic retail ecosystem. Europe remains a mature market with stringent regulations, but growth is slower (2-3% CAGR) due to market saturation.
Investment opportunities are concentrated in:
White-space opportunities exist in three areas:
These segments are currently underserved by large suppliers, offering entry points for specialized biotech and natural ingredient companies.
The market is moderately consolidated, with leading players including BASF, Croda, Givaudan, Symrise, Ashland, Dow, Evonik, and Solvay. These companies compete on innovation, sustainability, and regional reach. Recent developments include:
Supplier consolidation is ongoing, exemplified by BASF's exploratory talks with Evonik in September 2026, which could reshape the competitive landscape for specialty ingredients.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.1% from 2020-2034 |
| Segmentation |
|
By Ingredient Type
By Source
| By Geography |
|
Our primary research estimates the global market at USD 17.2 billion in 2025, with a projected CAGR of 6.1% to reach USD 27.1 billion by 2033.
Asia-Pacific holds the largest revenue share at approximately 33%, driven by high consumption and manufacturing in China and India.
Key drivers include rising consumer demand for natural and organic ingredients, regulatory pressure to replace synthetic chemicals, and the premiumization of actives with clinical claims.
Leading players include BASF, Croda, Givaudan, Symrise, Ashland, Dow, Evonik, and Solvay, who compete on innovation and sustainability.
Challenges include raw material price volatility, regulatory complexity, and supply chain concentration, which can disrupt availability and increase costs.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| R&D Manager | 25% |
| Supply Chain Head | 25% |
| Regulatory Affairs Specialist | 20% |
| Company Type | Representation (%) |
|---|---|
| Raw Material Suppliers | 35% |
| Formulators & Ingredient Houses | 25% |
| Contract Manufacturers | 20% |
| Brand Owners | 15% |
| Regulatory Consultants | 5% |