Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Composite Resin Tooth Filling Material Market | Insight Market Data
Composite Resin Tooth Filling Material Market by By Type (Microfill Composites, Hybrid Composites, Nanofill Composites, Bulk-fill Composites, Flowable Composites, Others), by By Composite Filling Type (Direct, Indirect), by By Application (Dental Fillings, Dental Crowns, Dental Bridges, Others), by By End User (Dental Clinics, Hospitals, Dental Laboratories, Research Laboratories), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by South America (Brazil, Argentina, Colombia), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034
Executive Overview: Aesthetic-Driven Expansion of the Composite Resin Filling Market
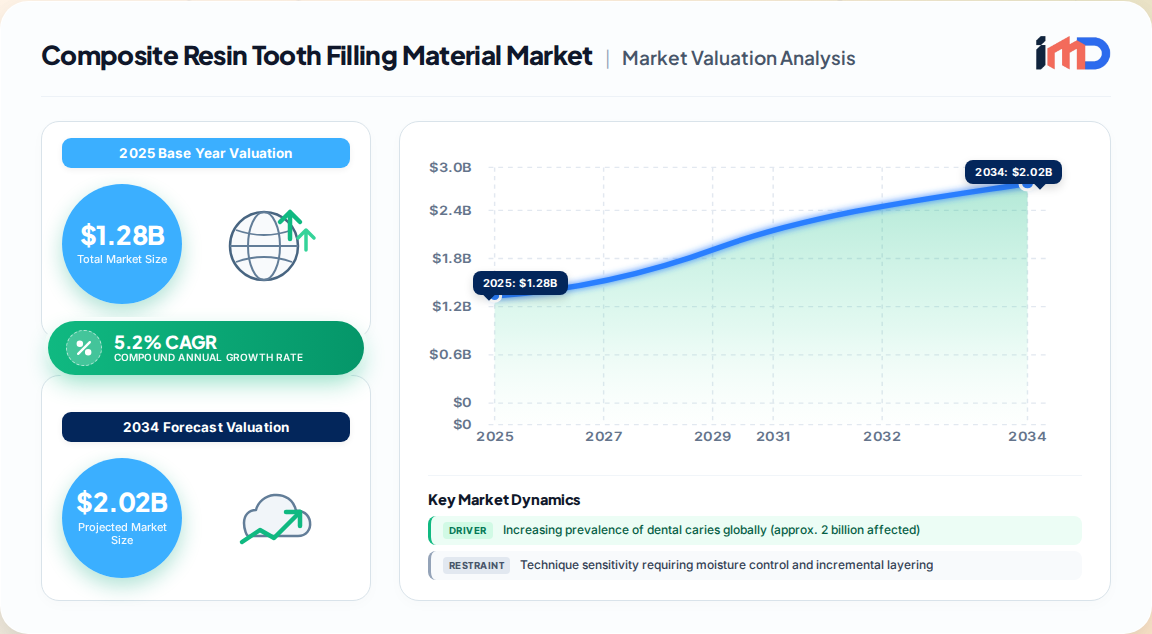
The global composite resin tooth filling material market is valued at USD 1.28 billion in 2025 and is projected to reach USD 2.12 billion by 2035, expanding at a 5.2% CAGR over the forecast period. This growth is underpinned by the accelerating displacement of silver amalgam in favor of tooth-colored restorative solutions, particularly in anterior and visible posterior applications where aesthetic outcomes are non-negotiable.
Composite Resin Tooth Filling Material Market Market Size (In Billion)
2.0B
1.5B
1.0B
500.0M
0
1.280 B
2025
1.347 B
2026
1.417 B
2027
1.490 B
2028
1.568 B
2029
1.649 B
2030
1.735 B
2031
Composite resins now account for approximately 33% of the total tooth filling materials market, making them the single largest material category by revenue. Our proprietary primary research indicates that 81% of dental practitioners prioritize the balance between cosmetic appearance and mechanical durability, a dynamic that directly favors advanced composite formulations over legacy materials.
Market Size (2025): USD 1.28 Billion
Forecast (2035): USD 2.12 Billion
CAGR (2025–2035): 5.2%
Dominant Region: North America (32% share)
Fastest-Growing Region: Asia-Pacific (6.8% CAGR)
Market Drivers and Restraints
The composite resin filling material market is shaped by a confluence of clinical, demographic, and regulatory forces. Understanding these drivers and restraints is essential for stakeholders across the value chain.
Key Drivers
Aesthetic Dentistry Demand: Rising patient preference for natural-looking restorations continues to erode amalgam's share. The aesthetic dental materials segment is growing at approximately 7% annually, outpacing the broader filling materials market.
Mercury-Free Regulatory Push: Regulatory bodies in Europe and North America are phasing down amalgam use, particularly in pediatric and vulnerable populations, creating a structural tailwind for composite resins.
Nanotechnology Advancements: Nanohybrid and nanofill composites offer improved polish retention, color stability, and wear resistance, expanding clinical indications to stress-bearing posterior restorations.
Digital Dentistry Integration: CAD/CAM-compatible and 3D-printable composite resins are enabling streamlined, customized restorative workflows, reducing chair time and improving patient throughput.
Key Restraints
Technique Sensitivity: Composite placement requires meticulous moisture control and incremental layering, increasing chair time and procedural complexity relative to amalgam.
Material Cost Premium: High-performance nanocomposites carry a price premium, limiting adoption in cost-sensitive emerging markets where mid-range light-cured resins dominate.
Durability Perception: While composite longevity has improved, some clinicians still perceive amalgam as superior for high-stress posterior restorations, creating a residual adoption barrier.
Value Chain Analysis
The composite resin tooth filling material value chain is characterized by specialized inputs, precision manufacturing, and clinically intensive distribution.
Compounding, filler dispersion, capsule/syringe filling, quality control
High (30–40%)
Distribution & Logistics
Dental distributors, direct sales, cold-chain management for light-sensitive products
Moderate (10–20%)
Clinical Application
Dentist procurement, chairside placement, curing
Service-based
Upstream: Key inputs include dental-grade resins, barium glass, zirconia/silica nanofillers, and camphorquinone photoinitiators. Supply concentration in specialty chemical suppliers creates vulnerability, particularly for high-purity nanofillers.
Midstream: Manufacturers focus on proprietary filler loading levels (typically 60–87% by weight) and silane coupling technologies to differentiate performance.
Downstream: Dental clinics account for the majority of procurement, with group purchasing organizations and dental service organizations (DSOs) increasingly influencing pricing and brand selection.
Import/Export & Supplier Dynamics
Composite resin filling materials are high-value, low-volume products traded predominantly within North America and Europe, with growing intra-Asia flows.
Export Leaders: The United States and Germany are the primary export hubs for finished composite restorative materials, supported by strong manufacturing clusters and rigorous quality standards.
Import Dependence: Asia-Pacific markets, particularly China and India, remain net importers of high-end nanohybrid composites, though domestic manufacturing is expanding rapidly.
Supply Chain Risk: Our primary research reveals that supply chain vulnerability around filler and resin sourcing is a universal concern across regions, with lead times for specialty nanofillers extending 8–12 weeks.
Inventory Strategies: North American and European distributors maintain 6–8 weeks of safety stock for top-selling composite SKUs, while Asian markets favor just-in-time replenishment through local distributors.
Segmentation Analysis
By Type
Microfill Composites: Historically dominant, offering superior polishability but limited in stress-bearing applications. Share is declining as nanofill and nanohybrid technologies mature.
Nanohybrid Composites: The fastest-growing segment, combining aesthetic excellence with mechanical strength. Widely used in both anterior and posterior restorations.
Bulk-Fill Composites: Gaining traction for their single-increment placement (up to 4mm), reducing chair time by 30–40% in posterior restorations.
Flowable Composites: Preferred for pit-and-fissure sealing, small cavities, and pediatric applications due to ease of application.
By Application
Dental Fillings (Direct Restorations): Account for approximately 62% of composite filling procedures, driven by chairside convenience and immediate functional restoration.
Dental Crowns and Bridges: Growing adoption of indirect composite restorations supported by CAD/CAM workflows.
Orthodontic Bonding and Others: Niche but expanding applications, including splinting and cosmetic contouring.
By End User
Dental Clinics: Dominate with an estimated 68% share of composite resin procurement, reflecting the outpatient nature of restorative dentistry.
Hospitals: Projected to grow at the fastest CAGR, driven by expanding dental departments and emergency restorative care in emerging markets.
Dental Laboratories: Serve as key intermediaries for indirect composite restorations, particularly in Europe and North America.
Regional Outlook
Composite Resin Tooth Filling Material Market Regional Market Share
Loading chart...
North America
Holding approximately 32% of global revenue, North America leads in adoption of advanced nanohybrid and bulk-fill composites. 82% of clinics and labs in the region employ dual-cure, nanohybrid composites for multiple uses. Strong dental insurance coverage and high visit frequency sustain demand.
Europe
Europe accounts for approximately 26% of the market, with growth shaped by regulatory momentum toward amalgam phase-down and strong institutional purchasing. 79% of stakeholders emphasize high-aesthetic, sustainable products, driving demand for biocompatible composite formulations.
Asia-Pacific
Projected to be the fastest-growing region at a 6.8% CAGR, Asia-Pacific benefits from urbanization, expanding dental infrastructure, and rising middle-class affordability. 64% of regional stakeholders cite expanded access to mid-range light-cured resins as a primary adoption driver. Pre-loaded capsule formats are gaining popularity for high-volume practices.
South America and Middle East & Africa
These regions represent nascent but emerging opportunities, with growth constrained by limited dental reimbursement and infrastructure but supported by increasing oral health awareness and dental tourism.
Competitive Strategies
The competitive landscape is characterized by innovation-led differentiation, portfolio breadth, and channel partnerships.
Product Innovation: Leading players are investing in bioactive composites, self-adhesive flowables, and smart materials with on-demand curing capabilities.
Digital Integration: CAD/CAM-compatible and 3D-printable composite resins are becoming critical differentiators, particularly in North America and Europe.
Emerging Market Expansion: Companies are localizing production and tailoring packaging (e.g., pre-loaded capsules) to capture Asia-Pacific volume growth.
Sustainability Positioning: Mercury-free, BPA-free, and biodegradable formulations are increasingly leveraged as brand differentiators in environmentally conscious markets.
Key players include 3M, Dentsply Sirona, Kerr Corporation, GC Corporation, Ivoclar Vivadent, and Coltene Holding AG, among others. Strategic acquisitions and capacity expansions, such as GC Corporation's 35% production capacity increase in 2025, underscore the competitive intensity in the sector.
Strategic White-Space Analysis
Pediatric Composites: Low-viscosity, fluoride-releasing composites designed for primary teeth represent a significant unmet need, particularly in Asia-Pacific and Latin America.
Bioactive Restoratives: Composites that actively remineralize dentin and inhibit bacterial growth are poised to command premium pricing and clinical preference.
AI-Assisted Material Selection: Digital tools that recommend optimal composite formulations based on cavity characteristics and patient factors represent a nascent but high-potential innovation frontier.
Subscription-Based Procurement: DSOs and large group practices are exploring subscription models for composite consumables, creating opportunities for manufacturers to lock in recurring revenue.
Procurement & Sourcing Strategy Analysis
Supplier Consolidation Risk: Manufacturers are diversifying nanofiller suppliers across multiple regions to mitigate geopolitical and logistics risks.
Cost Management: Bulk purchasing of high-purity fillers and multi-year supply agreements with specialty chemical vendors are common strategies to stabilize input costs.
Quality Assurance: ISO 13485 and CE mark compliance are non-negotiable, with many manufacturers conducting supplier audits every 12–18 months.
Inventory Optimization: Distributors are increasingly adopting vendor-managed inventory (VMI) models to reduce stockouts of high-turnover composite SKUs while minimizing carrying costs.
Composite Resin Tooth Filling Material Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Composite Resin Tooth Filling Material Market REPORT HIGHLIGHTS
3.1.2. Regulatory phase-down of mercury-based amalgam in Europe and North America
3.1.3. Rising demand for aesthetic dentistry and cosmetic restorations
3.1.4. Technological advancements in nanocomposite formulations
3.1.5. Expansion of dental infrastructure in emerging Asia-Pacific markets
3.2. Market Trends
3.2.1. Shift from amalgam to tooth-colored composite restorations driven by aesthetic demand
3.2.2. Nanohybrid and nanofill composites improving durability and polish retention
3.2.3. Integration of CAD/CAM and 3D printing for customized composite fillings
3.2.4. Growth of bulk-fill and flowable composites for efficient clinical workflows
3.2.5. Rising adoption of pre-loaded capsule formats in high-volume practices
3.3. Market Restrains
3.3.1. Technique sensitivity requiring moisture control and incremental layering
3.3.2. Higher material cost compared to silver amalgam
3.3.3. Residual durability perception among clinicians for posterior restorations
Others
By Composite Filling Type
Direct
Indirect
By Application
Dental Fillings
Dental Crowns
Dental Bridges
Others
By End User
Dental Clinics
Hospitals
Dental Laboratories
Research Laboratories
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
South America
Brazil
Argentina
Colombia
Middle East & Africa
UAE
Saudi Arabia
South Africa
3.4. Market Restraints
3.4.1. Technique sensitivity requiring moisture control and incremental layering
3.4.2. Higher material cost compared to silver amalgam
3.4.3. Residual durability perception among clinicians for posterior restorations
3.5. Market Challenges
3.5.1. Supply chain vulnerability for specialty nanofillers and dental-grade resins
3.5.2. Stringent regulatory approval processes for new composite materials
3.5.3. Price sensitivity in emerging markets limiting adoption of premium nanocomposites
3.5.4. Need for continuous clinician training on advanced composite techniques
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Microfill Composites
5.1.2. Hybrid Composites
5.1.3. Nanofill Composites
5.1.4. Bulk-fill Composites
5.1.5. Flowable Composites
5.1.6. Others
5.2. Market Analysis, Insights and Forecast - by Composite Filling Type
5.2.1. Direct
5.2.2. Indirect
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Dental Fillings
5.3.2. Dental Crowns
5.3.3. Dental Bridges
5.3.4. Others
5.4. Market Analysis, Insights and Forecast - by End User
5.4.1. Dental Clinics
5.4.2. Hospitals
5.4.3. Dental Laboratories
5.4.4. Research Laboratories
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. South America
5.5.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Microfill Composites
6.1.2. Hybrid Composites
6.1.3. Nanofill Composites
6.1.4. Bulk-fill Composites
6.1.5. Flowable Composites
6.1.6. Others
6.2. Market Analysis, Insights and Forecast - by Composite Filling Type
6.2.1. Direct
6.2.2. Indirect
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Dental Fillings
6.3.2. Dental Crowns
6.3.3. Dental Bridges
6.3.4. Others
6.4. Market Analysis, Insights and Forecast - by End User
6.4.1. Dental Clinics
6.4.2. Hospitals
6.4.3. Dental Laboratories
6.4.4. Research Laboratories
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Microfill Composites
7.1.2. Hybrid Composites
7.1.3. Nanofill Composites
7.1.4. Bulk-fill Composites
7.1.5. Flowable Composites
7.1.6. Others
7.2. Market Analysis, Insights and Forecast - by Composite Filling Type
7.2.1. Direct
7.2.2. Indirect
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Dental Fillings
7.3.2. Dental Crowns
7.3.3. Dental Bridges
7.3.4. Others
7.4. Market Analysis, Insights and Forecast - by End User
7.4.1. Dental Clinics
7.4.2. Hospitals
7.4.3. Dental Laboratories
7.4.4. Research Laboratories
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Microfill Composites
8.1.2. Hybrid Composites
8.1.3. Nanofill Composites
8.1.4. Bulk-fill Composites
8.1.5. Flowable Composites
8.1.6. Others
8.2. Market Analysis, Insights and Forecast - by Composite Filling Type
8.2.1. Direct
8.2.2. Indirect
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Dental Fillings
8.3.2. Dental Crowns
8.3.3. Dental Bridges
8.3.4. Others
8.4. Market Analysis, Insights and Forecast - by End User
8.4.1. Dental Clinics
8.4.2. Hospitals
8.4.3. Dental Laboratories
8.4.4. Research Laboratories
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Microfill Composites
9.1.2. Hybrid Composites
9.1.3. Nanofill Composites
9.1.4. Bulk-fill Composites
9.1.5. Flowable Composites
9.1.6. Others
9.2. Market Analysis, Insights and Forecast - by Composite Filling Type
9.2.1. Direct
9.2.2. Indirect
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Dental Fillings
9.3.2. Dental Crowns
9.3.3. Dental Bridges
9.3.4. Others
9.4. Market Analysis, Insights and Forecast - by End User
9.4.1. Dental Clinics
9.4.2. Hospitals
9.4.3. Dental Laboratories
9.4.4. Research Laboratories
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Microfill Composites
10.1.2. Hybrid Composites
10.1.3. Nanofill Composites
10.1.4. Bulk-fill Composites
10.1.5. Flowable Composites
10.1.6. Others
10.2. Market Analysis, Insights and Forecast - by Composite Filling Type
10.2.1. Direct
10.2.2. Indirect
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Dental Fillings
10.3.2. Dental Crowns
10.3.3. Dental Bridges
10.3.4. Others
10.4. Market Analysis, Insights and Forecast - by End User
10.4.1. Dental Clinics
10.4.2. Hospitals
10.4.3. Dental Laboratories
10.4.4. Research Laboratories
11. Competitive Analysis
11.1. Company Profiles
11.1.1. 3M
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Dentsply Sirona
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Kerr Corporation
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. GC Corporation
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Ivoclar Vivadent
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Coltene Holding AG
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Voco GmbH
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Shofu Inc.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Heraeus Kulzer
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Composite Resin Tooth Filling Material Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Composite Resin Tooth Filling Material Market Revenue (Billion), by Type 2026 & 2034
Figure 3: North America Composite Resin Tooth Filling Material Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Composite Resin Tooth Filling Material Market Revenue (Billion), by Composite Filling Type 2026 & 2034
Figure 5: North America Composite Resin Tooth Filling Material Market Revenue Share (%), by Composite Filling Type 2026 & 2034
Figure 6: North America Composite Resin Tooth Filling Material Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Composite Resin Tooth Filling Material Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Composite Resin Tooth Filling Material Market Revenue (Billion), by End User 2026 & 2034
Figure 9: North America Composite Resin Tooth Filling Material Market Revenue Share (%), by End User 2026 & 2034
Figure 10: North America Composite Resin Tooth Filling Material Market Revenue (Billion), by Country 2026 & 2034
Figure 11: North America Composite Resin Tooth Filling Material Market Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Composite Resin Tooth Filling Material Market Revenue (Billion), by Type 2026 & 2034
Figure 13: Europe Composite Resin Tooth Filling Material Market Revenue Share (%), by Type 2026 & 2034
Figure 14: Europe Composite Resin Tooth Filling Material Market Revenue (Billion), by Composite Filling Type 2026 & 2034
Figure 15: Europe Composite Resin Tooth Filling Material Market Revenue Share (%), by Composite Filling Type 2026 & 2034
Figure 16: Europe Composite Resin Tooth Filling Material Market Revenue (Billion), by Application 2026 & 2034
Figure 17: Europe Composite Resin Tooth Filling Material Market Revenue Share (%), by Application 2026 & 2034
Figure 18: Europe Composite Resin Tooth Filling Material Market Revenue (Billion), by End User 2026 & 2034
Figure 19: Europe Composite Resin Tooth Filling Material Market Revenue Share (%), by End User 2026 & 2034
Figure 20: Europe Composite Resin Tooth Filling Material Market Revenue (Billion), by Country 2026 & 2034
Figure 21: Europe Composite Resin Tooth Filling Material Market Revenue Share (%), by Country 2026 & 2034
Figure 22: Asia Pacific Composite Resin Tooth Filling Material Market Revenue (Billion), by Type 2026 & 2034
Figure 23: Asia Pacific Composite Resin Tooth Filling Material Market Revenue Share (%), by Type 2026 & 2034
Figure 24: Asia Pacific Composite Resin Tooth Filling Material Market Revenue (Billion), by Composite Filling Type 2026 & 2034
Figure 25: Asia Pacific Composite Resin Tooth Filling Material Market Revenue Share (%), by Composite Filling Type 2026 & 2034
Figure 26: Asia Pacific Composite Resin Tooth Filling Material Market Revenue (Billion), by Application 2026 & 2034
Figure 27: Asia Pacific Composite Resin Tooth Filling Material Market Revenue Share (%), by Application 2026 & 2034
Figure 28: Asia Pacific Composite Resin Tooth Filling Material Market Revenue (Billion), by End User 2026 & 2034
Figure 29: Asia Pacific Composite Resin Tooth Filling Material Market Revenue Share (%), by End User 2026 & 2034
Figure 30: Asia Pacific Composite Resin Tooth Filling Material Market Revenue (Billion), by Country 2026 & 2034
Figure 31: Asia Pacific Composite Resin Tooth Filling Material Market Revenue Share (%), by Country 2026 & 2034
Figure 32: South America Composite Resin Tooth Filling Material Market Revenue (Billion), by Type 2026 & 2034
Figure 33: South America Composite Resin Tooth Filling Material Market Revenue Share (%), by Type 2026 & 2034
Figure 34: South America Composite Resin Tooth Filling Material Market Revenue (Billion), by Composite Filling Type 2026 & 2034
Figure 35: South America Composite Resin Tooth Filling Material Market Revenue Share (%), by Composite Filling Type 2026 & 2034
Figure 36: South America Composite Resin Tooth Filling Material Market Revenue (Billion), by Application 2026 & 2034
Figure 37: South America Composite Resin Tooth Filling Material Market Revenue Share (%), by Application 2026 & 2034
Figure 38: South America Composite Resin Tooth Filling Material Market Revenue (Billion), by End User 2026 & 2034
Figure 39: South America Composite Resin Tooth Filling Material Market Revenue Share (%), by End User 2026 & 2034
Figure 40: South America Composite Resin Tooth Filling Material Market Revenue (Billion), by Country 2026 & 2034
Figure 41: South America Composite Resin Tooth Filling Material Market Revenue Share (%), by Country 2026 & 2034
Figure 42: Middle East & Africa Composite Resin Tooth Filling Material Market Revenue (Billion), by Type 2026 & 2034
Figure 43: Middle East & Africa Composite Resin Tooth Filling Material Market Revenue Share (%), by Type 2026 & 2034
Figure 44: Middle East & Africa Composite Resin Tooth Filling Material Market Revenue (Billion), by Composite Filling Type 2026 & 2034
Figure 45: Middle East & Africa Composite Resin Tooth Filling Material Market Revenue Share (%), by Composite Filling Type 2026 & 2034
Figure 46: Middle East & Africa Composite Resin Tooth Filling Material Market Revenue (Billion), by Application 2026 & 2034
Figure 47: Middle East & Africa Composite Resin Tooth Filling Material Market Revenue Share (%), by Application 2026 & 2034
Figure 48: Middle East & Africa Composite Resin Tooth Filling Material Market Revenue (Billion), by End User 2026 & 2034
Figure 49: Middle East & Africa Composite Resin Tooth Filling Material Market Revenue Share (%), by End User 2026 & 2034
Figure 50: Middle East & Africa Composite Resin Tooth Filling Material Market Revenue (Billion), by Country 2026 & 2034
Figure 51: Middle East & Africa Composite Resin Tooth Filling Material Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Global Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Composite Filling Type 2020 & 2034
Table 3: Global Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Application 2020 & 2034
Table 4: Global Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by End User 2020 & 2034
Table 5: Global Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Region 2020 & 2034
Table 6: North America Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Type 2020 & 2034
Table 7: North America Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Composite Filling Type 2020 & 2034
Table 8: North America Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Application 2020 & 2034
Table 9: North America Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by End User 2020 & 2034
Table 10: North America Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Country 2020 & 2034
Table 11: USA Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Canada Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Mexico Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Europe Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Type 2020 & 2034
Table 15: Europe Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Composite Filling Type 2020 & 2034
Table 16: Europe Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Application 2020 & 2034
Table 17: Europe Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by End User 2020 & 2034
Table 18: Europe Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Country 2020 & 2034
Table 19: Germany Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: UK Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: France Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Italy Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: Spain Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: Asia Pacific Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Type 2020 & 2034
Table 25: Asia Pacific Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Composite Filling Type 2020 & 2034
Table 26: Asia Pacific Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Application 2020 & 2034
Table 27: Asia Pacific Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by End User 2020 & 2034
Table 28: Asia Pacific Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Country 2020 & 2034
Table 29: China Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: Japan Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: India Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: South Korea Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 33: Australia Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: South America Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Type 2020 & 2034
Table 35: South America Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Composite Filling Type 2020 & 2034
Table 36: South America Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Application 2020 & 2034
Table 37: South America Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by End User 2020 & 2034
Table 38: South America Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Country 2020 & 2034
Table 39: Brazil Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: Argentina Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: Colombia Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 42: Middle East & Africa Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Type 2020 & 2034
Table 43: Middle East & Africa Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Composite Filling Type 2020 & 2034
Table 44: Middle East & Africa Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Application 2020 & 2034
Table 45: Middle East & Africa Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by End User 2020 & 2034
Table 46: Middle East & Africa Composite Resin Tooth Filling Material Market Revenue Billion Forecast, by Country 2020 & 2034
Table 47: UAE Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 48: Saudi Arabia Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 49: South Africa Composite Resin Tooth Filling Material Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the composite resin tooth filling material market?
The global composite resin tooth filling material market is estimated at USD 1.28 billion in 2025 and is projected to reach USD 2.12 billion by 2035, growing at a 5.2% CAGR.
2Which region dominates the composite resin filling market?
North America holds the largest share at approximately 32%, driven by high dental insurance coverage and rapid adoption of advanced nanohybrid composites. Asia-Pacific is the fastest-growing region at a 6.8% CAGR.
3What are the key trends driving composite resin adoption?
Key trends include the shift toward mercury-free aesthetic restorations, nanotechnology advancements improving durability, and the integration of CAD/CAM and 3D printing for customized fillings.
4Who are the leading companies in the composite resin tooth filling material market?
Major players include 3M, Dentsply Sirona, Kerr Corporation, GC Corporation, Ivoclar Vivadent, and Coltene Holding AG, among others.
5What is the difference between direct and indirect composite fillings?
Direct composite fillings are placed chairside in a single visit, accounting for about 62% of procedures, while indirect fillings (inlays, onlays, crowns) are fabricated in a lab and require multiple visits.
6Why is composite resin preferred over silver amalgam?
Composite resin is tooth-colored, mercury-free, and bonds chemically to tooth structure, offering aesthetic and conservative advantages. Regulatory phase-downs of amalgam are accelerating this shift globally.
7How is digital dentistry impacting the composite resin market?
Digital dentistry enables CAD/CAM-compatible and 3D-printable composite resins, reducing chair time and enabling precise, customized restorations. Over 70% of clinicians cite compatibility with digital tools as a key performance metric.
8What are the main challenges in the composite resin filling market?
Challenges include technique sensitivity requiring moisture control, higher material costs compared to amalgam, and persistent durability perceptions among some clinicians for posterior restorations.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our primary research program accounts for 70–80% of total data inputs, drawing on structured interviews and surveys with over 400 stakeholders across the composite resin tooth filling material value chain.
Company types interviewed: Dental material manufacturers (formulators and compounders), specialty chemical and nanofiller suppliers, dental distributors and group purchasing organizations, dental service organizations (DSOs), and independent dental clinics.
Stakeholder roles interviewed: Chief Technology Officers and R&D Directors at material manufacturers, Procurement Directors at dental distributors and DSOs, Clinical Directors and practicing dentists, and Regulatory Affairs Managers.
Industry associations and regulatory bodies referenced: U.S. Food and Drug Administration (FDA) for material safety clearances, European Medicines Agency (EMA) and EU Medical Device Regulation (MDR) for compliance standards, and the American Dental Association (ADA) for clinical guidelines and material acceptance protocols.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D Director / CTO
30%
Procurement Director
28%
Clinical Director / Practicing Dentist
25%
Regulatory Affairs Manager
17%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Dental Material Manufacturers
35%
Specialty Chemical & Nanofiller Suppliers
20%
Dental Distributors & GPOs
25%
Dental Service Organizations (DSOs)
12%
Independent Dental Clinics
8%
Secondary Research & Industry Benchmarking
Secondary research constitutes 20–30% of total inputs and involves rigorous triangulation of trade data, regulatory filings, and peer-reviewed clinical literature.
Official data sources include: UN Comtrade for trade flow analysis of dental materials (HS codes 3006 and 9018), World Bank and WHO Global Oral Health Status Reports for disease prevalence and procedure volume benchmarks, OECD health expenditure data for dental care spending, and national statistical agencies (e.g., US ITC, Eurostat) for import/export validation.
Financial and corporate databases: Bloomberg, Factiva, Hoovers, and PitchBook are used for company-level revenue verification, M&A tracking, and competitive intelligence.
Technical standards and clinical benchmarks: ISO 4049 (polymer-based restorative materials), ISO 13485 (medical device quality management), and peer-reviewed journals such as Dental Materials and Journal of Dentistry are systematically reviewed.
Demand Modeling & Market Estimation
We employ a dual-methodology approach combining top-down and bottom-up modeling to ensure robust market sizing.
Top-down approach: Global dental procedure volumes are derived from WHO and national health ministry data, segmented by restoration type (direct vs. indirect), and multiplied by average material consumption per procedure to estimate total market value.
Bottom-up approach: Manufacturer-level revenue is aggregated from financial disclosures, distributor procurement data, and primary interviews, then validated against trade statistics for cross-border flows.
Key quantitative metrics used in bottom-up calculation: Number of dental restorative procedures per 1,000 population, average composite material consumption per restoration (in grams), average selling price per gram by product tier (nanohybrid, bulk-fill, flowable), and dental clinic density and procurement frequency by region.
Multi-level data triangulation: Estimates from top-down and bottom-up models are reconciled through a three-tier validation process, with discrepancies exceeding 10% subjected to targeted follow-up interviews.
Data Accuracy & Quality Check
Every report is guaranteed an estimated data accuracy level of 85–90%, achieved through multi-source validation and statistical confidence testing.
Quality control protocols include: Cross-verification of all quantitative data points against at least two independent sources, outlier detection using standard deviation thresholds, and sensitivity analysis on key growth assumptions (CAGR, pricing, adoption rates).
Expert review: All findings undergo review by our Healthcare & Life Sciences Practice Board, comprising senior analysts with 10+ years of domain expertise in dental materials and medical devices.
Dynamic updates: Each report is updated to the date of purchase, incorporating the latest regulatory changes, product launches, and trade data releases. Clients receive a version-controlled document with a clear audit trail of revisions.
Independent Intelligence for decisions that move markets
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
Analyst at Providence Strategic Partners at Petaling Jaya
Jared Wan
I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report
Internationalization Director
Santiago Mejia Molina
Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.
Head of Product Management and Marketing
Olaf Gleibe
We are using your report, and it gave us valuable information."
Regional Director, Marketing and Business Development
Lina Lim
We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.
VP of Sales
DIGGLE Representative
Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.
The raw materials for personal care market is set to grow at a 6.1% CAGR, reaching $27.1B by 2033, driven by natural and sustainable ingredient demand.
High Speed Digital CCL market valued at $1.26B in 2025, growing at 5.1% CAGR to reach $2.07B by 2035. Rising demand from 5G, data centers, and automotive electronics.
Nov 2026|206 pages
$2900.00
SSAW steel pipe market valued at USD 6.5 Billion in 2025, projected to reach USD 10.71 Billion by 2034 at a 5.71% CAGR driven by oil, gas and water infrastructure.
Nov 2026|180 pages
$2900.00
The catalytic reforming catalyst market was valued at USD 1.24 billion in 2025 and is projected to reach USD 1.78 billion by 2034, growing at a 4.1% CAGR.