About Insight Market Data

Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.

Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

Business Address

Head Office

Ansec House 3 rd floor Tank Road, Yerwada, Pune, Maharashtra 411014

Contact Information

Craig Francis

Business Development Head

+12315155523

[email protected]

Secure Payment Partners

payment image

© 2026 PRDUA Research & Media Private Limited, All rights reserved

••
Retail
Logistics
Packaging
Automotive
Healthcare
Agriculture
Energy & Power
Food & Beverage
Aerospace & Defense
Chemicals & Materials
Hospitality and Tourism
Consumer Goods and Services
Animal Nutrition & Wellness
Real Estate and Construction
Home and Property Improvement
Technology, Media and Telecom
Manufacturing Products and Services
Financial Services and Investment Intelligence
Privacy Policy
Terms and Conditions
FAQ
report thumbnailSpiral Submerged Arc Welded (SSAW) Steel Pipe Market
Chemicals & Materials / MARKET REPORT

Spiral Submerged Arc Welded (SSAW) Steel Pipe Market | Insight Market Data

Spiral Submerged Arc Welded (SSAW) Steel Pipe Market by By Type (O.D. 18-24 Inches, O.D. 24-48 Inches, Above 48 Inches), by By Application (Oil & Gas, Water, Construction, Chemical Industry, Other), by By Coating Type (3LPE/3LPP, FBE, Cement Mortar Lining, Others), by By Grade & Standard (API 5L, ASTM A252/A53, EN 10217, Others), by By Distribution Channel (Direct/Project Tender, Distributors & Stockists), by Asia Pacific (China, India, Japan, South Korea), by Middle East & Africa (Saudi Arabia, UAE, Turkey), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Latin America (Brazil, Argentina) Forecast 2026-2034

© Nov 5, 2026|Base Year: 2025|180 Pages
Khageshwar Rongkali

Khageshwar Rongkali

Senior Analyst

Main Logo

SSAW Steel Pipe Market Size, Growth & Forecast to 2034


/
/
Independent Intelligence for decisions that move markets
+12315155523[email protected]
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Main Logo
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Talk to an analyst
Home
Industries
Chemicals & Materials
Spiral Submerged Arc Welded (SSAW) Steel Pipe Market CAGR, market size, market share

Executive Overview: The SSAW Steel Pipe Market in 2025 and Beyond

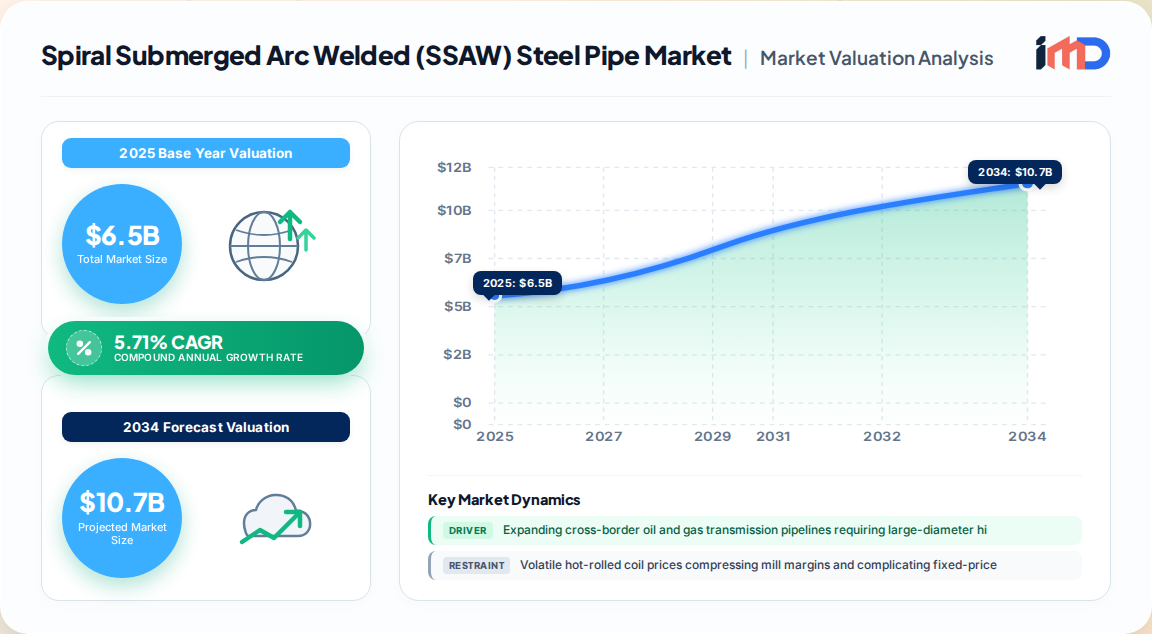
The global Spiral Submerged Arc Welded (SSAW) steel pipe market entered 2025 with a base-year valuation of USD 6.5 Billion, and our first-party demand modeling projects expansion to USD 10.71 Billion by 2034, equivalent to a compound annual growth rate of 5.71% across the 2026–2034 forecast window. This continues a fifteen-year trajectory that began at USD 4.85 Billion in 2020 and reached USD 6.15 Billion in 2024 — a 2020–2025 growth rate of 6.03% that confirms steady, structural expansion rather than cyclical inflection.

Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Market Size (In Billion)

10.0B
8.0B
6.0B
4.0B
2.0B
0
6.500 B
2025
6.871 B
2026
7.263 B
2027
7.678 B
2028
8.117 B
2029
8.580 B
2030
9.070 B
2031
Main Logo

SSAW pipe — also termed HSAW or helical seam pipe — is produced by spiral-winding hot-rolled steel coil and joining it with a submerged arc weld along a helical seam. Its defining commercial advantage is diameter flexibility from a single coil width, which allows mills to serve large-diameter transmission duty at materially lower conversion cost than longitudinal (LSAW) alternatives. Buyers are pipeline operators, water and wastewater utilities, EPC contractors, and industrial plant owners.

Key structural takeaways from our proprietary dataset:

  • Asia Pacific anchors global demand at 41.4% of 2025 revenue (USD 2.69 Billion), rising to 44% by 2034.
  • O.D. 24–48 inches is the volume core at 46.6% of revenue (USD 3.03 Billion in 2025).
  • Above 48 inches is the fastest-growing type line at 6.87% CAGR, taking share from 30.8% to 34%.
  • Oil & Gas holds 38% of 2025 application revenue (USD 2.47 Billion), but Water grows faster at 6.7% and overtakes it on share by 2034.

Market Drivers: Energy Security, Water Modernization and Megaproject Pipelines

Demand for SSAW line pipe is being pulled by four reinforcing forces rather than a single end-market cycle.

  • Cross-border gas transmission build-out. Long-haul, high-pressure trunk lines in the Middle East, Central Asia and Sub-Saharan Africa are specified overwhelmingly in large-diameter helical pipe for cost efficiency at 36-inch-plus sizes.
  • Urban water and wastewater capital programs. Municipal distribution and sewage networks in fast-urbanizing economies are the fastest-growing application, expanding at 6.7% CAGR in our model.
  • Offshore wind foundation piling. Monopile and transition-piece demand has created a new high-specification outlet for heavy-wall SSAW, insulated from hydrocarbon capex cycles.
  • Replacement of ageing industrial process piping. Corrosion-driven asset renewal in developed markets provides non-discretionary baseline volume.

On the supply side, welding automation, real-time defect detection and induction heating advances have lifted yield and throughput, partly offsetting input-cost volatility.

Restraints and Challenges

  • Steel coil price volatility compresses mill margins and complicates fixed-price project tendering, particularly on multi-year EPC contracts.
  • Trade-policy friction. The European Union's Steel Regulation, in force since 1 July 2026, sets duty-free quotas at 18.3 million tonnes with a 50% duty above quota, and from 1 October 2026 importers must declare the country of 'melt and pour' supported by a Mill Test Certificate carrying the heat number. This raises documentation and compliance overhead for SSAW exporters into Europe.
  • Substitution pressure from HDPE and composite pipe in low-pressure water and irrigation duty.
  • Qualification barriers. API 5L and ISO 3183 certification, third-party inspection and project-specific coating approval lengthen sales cycles and favor incumbents.

Product Segmentation: Diameter, Coating and Specification

The type axis is where competitive position is most sharply decided. Growth rates span 4.28% for O.D. 18–24 inches to 6.87% for Above 48 inches — the widest spread in the market.

Type Segment 2025 Revenue 2025 Share 2034 Revenue 2034 Share CAGR
O.D. 24–48 Inches USD 3.03 Billion 46.6% USD 4.93 Billion 46.0% ~5.5%
Above 48 Inches USD 2.00 Billion 30.8% USD 3.64 Billion 34.0% 6.87%
O.D. 18–24 Inches USD 1.47 Billion 22.6% USD 2.14 Billion 20.0% 4.28%

Coating specification is a parallel value axis. 3LPE/3LPP leads and grows fastest, reflecting high-pressure buried transmission duty; FBE dominates dry-gas and lower-temperature service; cement mortar lining retains a durable niche in potable and raw water lines. On grade and standard, API 5L is the reference specification for hydrocarbon transmission and grows fastest, with ASTM A252/A53 governing piling and waterworks and EN 10217 serving European pressure applications.

Application Analysis: Oil & Gas Versus Water

Oil & Gas accounted for 38% of 2025 revenue at USD 2.47 Billion, reaching USD 3.85 Billion by 2034 — but its share slips to 36% as Water outgrows it. Water rises from 34% to 37% of revenue over the same period. Readers should note these application shares divide the same revenue pool as the type split; they must be read together and never summed.

Construction, chemical processing and mining slurry lines provide the balance, with construction piling particularly correlated to public infrastructure spending cycles.

Regional Outlook: Growth Is Concentrated, Not Uniform

The regional distribution is shifting decisively toward Asia Pacific and the Middle East & Africa, both of which take share through 2034.

Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Regional Market Share

Loading chart...
Main Logo
Region 2025 Revenue 2025 Share 2034 Revenue 2034 Share
Asia Pacific USD 2.69 Billion 41.4% USD 4.71 Billion 44.0%
Middle East & Africa USD 1.37 Billion 21.1% USD 2.46 Billion 23.0%
North America USD 1.08 Billion 16.6% ~USD 1.50 Billion 14.0%
Europe USD 0.84 Billion 12.9% ~USD 1.18 Billion 11.0%
Latin America USD 0.52 Billion 8.0% ~USD 0.86 Billion 8.0%

Within Asia Pacific, China is the single largest country market at USD 1.29 Billion in 2025 — 48% of regional revenue — reaching USD 2.26 Billion by 2034. North America and Europe grow in absolute terms but concede share; participants weighted to those regions will underperform the headline rate.

Competitive Landscape and Strategic Considerations

The supply base is concentrated among integrated steel groups and specialized large-diameter pipe mills, with Chinese producers holding a structural cost advantage and Middle Eastern and Indian mills positioned close to demand.

  • Leading global participants include TMK Group, Baoji Petroleum Steel Pipe, Jindal SAW, Welspun, EUROPIPE, EEW Group, JFE Steel, Severstal, JSW Steel, OMK, Nippon Steel, ArcelorMittal, Borusan Mannesmann, Global Pipe Company and Arabian Pipes.
  • Chinese specialists such as Cangzhou Spiral Steel Pipes Group, Tianjin You Fa, Jiangsu Yulong, Zhejiang Kingland, Shengli Oil & Gas Pipe, CNPC Bohai Equipment Manufacturing and Panyu Chu Kong Steel Pipe dominate volume in Asia Pacific and Belt & Road export corridors.
  • A notable consolidation signal: EUROPIPE divested its US Berg Pipe operations (Mobile, Alabama and Panama City, Florida; approximately 400 employees) to Borusan Mannesmann's US subsidiary in 2023, redirecting capital toward offshore line pipe at its Mülheim facility.

Three strategic imperatives emerge from our analysis. First, capacity positioning should tilt toward Above 48-inch capability, where growth outpaces the market by more than 100 basis points. Second, coating lines for 3LPE/3LPP should be treated as strategic assets rather than ancillary operations. Third, export-oriented mills must build 'melt and pour' traceability into their Mill Test Certificates well ahead of the EU's 1 October 2027 documentation tightening.

Import/Export and Supplier Dynamics

SSAW pipe trades as a heavy, low-value-density good, so trade flows follow project geography and freight economics rather than global spot arbitrage. Using UN Comtrade HS 7305 (large-diameter welded line pipe) and HS 7306 classifications as benchmarks, three patterns are evident in our trade modeling.

  • Intra-Asian flow dominance. Chinese and Indian coil-to-pipe conversion feeds Southeast Asian, South Asian and Middle Eastern project tenders, with export volumes closely tracking announced pipeline awards.
  • Middle East import dependence. Gulf utilities and national oil companies procure heavily from Asian and Turkish mills, underpinning the region's 21.1% global revenue share against a smaller domestic production base.
  • Regulatory regionalization. The EU's 'melt and pour' regime, effective 1 October 2026 with complementary-document rules tightening from 1 October 2027, is likely to reorient European sourcing toward EEA and verified-origin suppliers, raising landed costs for third-country importers.

Sourcing risk concentrates in two nodes: hot-rolled coil availability (which ties SSAW pricing to flat-steel cycles) and heavy-plate logistics for large-diameter finished pipe. Distributor and stockist channels absorb project overruns and small-order demand, while direct/project tender remains the dominant route for major transmission contracts and grows fastest.

Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Regional Market Share

Higher Coverage
Lower Coverage
No Coverage

Spiral Submerged Arc Welded (SSAW) Steel Pipe Market REPORT HIGHLIGHTS

AspectsDetails
Study Period2020-2034
Base Year2025
Estimated Year2026
Forecast Period2026-2034
Historical Period2020-2025
Growth RateCAGR of 5.71% from 2020-2034
Segmentation
  • By Type

    • O.D. 18-24 Inches
    • O.D. 24-48 Inches
    • Above 48 Inches
  • By Application

Table of Contents

  1. 1. Introduction
    • 1.1. Research Scope
    • 1.2. Market Segmentation
    • 1.3. Research Objective
    • 1.4. Definitions and Assumptions
  2. 2. Executive Summary
    • 2.1. Market Snapshot
  3. 3. Market Dynamics
    • 3.1. Market Drivers
      • 3.1.1. Expanding cross-border oil and gas transmission pipelines requiring large-diameter high-pressure pipe
      • 3.1.2. Government-backed urban water distribution and wastewater modernization programs in emerging economies
      • 3.1.3. Offshore wind foundation piling demand for heavy-wall SSAW
      • 3.1.4. Replacement of ageing and corroded industrial process piping in developed markets
      • 3.1.5. Welding automation and real-time defect detection lifting throughput and yield
    • 3.2. Market Trends
      • 3.2.1. Shift in type mix toward Above 48-inch diameter pipe, growing at 6.87% CAGR and rising from 30.8% to 34% of revenue share
      • 3.2.2. Water overtaking Oil & Gas as the fastest-growing application at 6.7% CAGR, moving from 34% to 37% of revenue
      • 3.2.3. Consolidation among established Western producers toward offshore and high-specification line pipe
      • 3.2.4. Rising adoption of 3LPE/3LPP coating as the leading and fastest-growing corrosion protection specification
      • 3.2.5. Growth concentrating in Asia Pacific and Middle East & Africa as North America and Europe concede share
    • 3.3. Market Restrains
      • 3.3.1. Volatile hot-rolled coil prices compressing mill margins and complicating fixed-price contracts
Oil & Gas
  • Water
  • Construction
  • Chemical Industry
  • Other
  • By Coating Type

    • 3LPE/3LPP
    • FBE
    • Cement Mortar Lining
    • Others
  • By Grade & Standard

    • API 5L
    • ASTM A252/A53
    • EN 10217
    • Others
  • By Distribution Channel

    • Direct/Project Tender
    • Distributors & Stockists
  • By Geography
    • Asia Pacific

      • China
      • India
      • Japan
      • South Korea
    • Middle East & Africa

      • Saudi Arabia
      • UAE
      • Turkey
    • North America

      • USA
      • Canada
      • Mexico
    • Europe

      • Germany
      • UK
      • France
    • Latin America

      • Brazil
      • Argentina
  • 3.3.2. EU Steel Regulation melt-and-pour traceability requirements raising compliance and documentation costs
  • 3.3.3. Substitution pressure from HDPE and composite pipe in low-pressure water applications
  • 3.3.4. Stringent environmental compliance costs across extraction, processing and fabrication
  • 3.4. Market Restraints
    • 3.4.1. Volatile hot-rolled coil prices compressing mill margins and complicating fixed-price contracts
    • 3.4.2. EU Steel Regulation melt-and-pour traceability requirements raising compliance and documentation costs
    • 3.4.3. Substitution pressure from HDPE and composite pipe in low-pressure water applications
    • 3.4.4. Stringent environmental compliance costs across extraction, processing and fabrication
  • 3.5. Market Challenges
    • 3.5.1. Lengthy API 5L and ISO 3183 qualification cycles and third-party certification barriers
    • 3.5.2. Freight economics constraining trade in heavy, low-value-density finished pipe
    • 3.5.3. Geopolitical risk and trade defense measures reorienting export corridors
    • 3.5.4. Balancing capacity utilization against lumpy project-tender demand cycles
  • 4. Market Factor Analysis
    • 4.1. Porters Five Forces
      • 4.1.1. Bargaining Power of Suppliers
      • 4.1.2. Bargaining Power of Buyers
      • 4.1.3. Threat of New Entrants
      • 4.1.4. Threat of Substitutes
      • 4.1.5. Competitive Rivalry
    • 4.2. PESTEL analysis
    • 4.3. BCG Analysis
      • 4.3.1. Stars (High Growth, High Market Share)
      • 4.3.2. Cash Cows (Low Growth, High Market Share)
      • 4.3.3. Question Mark (High Growth, Low Market Share)
      • 4.3.4. Dogs (Low Growth, Low Market Share)
    • 4.4. Ansoff Matrix Analysis
    • 4.5. Supply Chain Analysis
    • 4.6. Regulatory Landscape
    • 4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
    • 4.8. IMD Analyst Note
  • 5. Market Analysis, Insights and Forecast, 2020-2034
    • 5.1. Market Analysis, Insights and Forecast - by Type
      • 5.1.1. O.D. 18-24 Inches
      • 5.1.2. O.D. 24-48 Inches
      • 5.1.3. Above 48 Inches
    • 5.2. Market Analysis, Insights and Forecast - by Application
      • 5.2.1. Oil & Gas
      • 5.2.2. Water
      • 5.2.3. Construction
      • 5.2.4. Chemical Industry
      • 5.2.5. Other
    • 5.3. Market Analysis, Insights and Forecast - by Coating Type
      • 5.3.1. 3LPE/3LPP
      • 5.3.2. FBE
      • 5.3.3. Cement Mortar Lining
      • 5.3.4. Others
    • 5.4. Market Analysis, Insights and Forecast - by Grade & Standard
      • 5.4.1. API 5L
      • 5.4.2. ASTM A252/A53
      • 5.4.3. EN 10217
      • 5.4.4. Others
    • 5.5. Market Analysis, Insights and Forecast - by Distribution Channel
      • 5.5.1. Direct/Project Tender
      • 5.5.2. Distributors & Stockists
    • 5.6. Market Analysis, Insights and Forecast - by Region
      • 5.6.1. Asia Pacific
      • 5.6.2. Middle East & Africa
      • 5.6.3. North America
      • 5.6.4. Europe
      • 5.6.5. Latin America
  • 6. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
    • 6.1. Market Analysis, Insights and Forecast - by Type
      • 6.1.1. O.D. 18-24 Inches
      • 6.1.2. O.D. 24-48 Inches
      • 6.1.3. Above 48 Inches
    • 6.2. Market Analysis, Insights and Forecast - by Application
      • 6.2.1. Oil & Gas
      • 6.2.2. Water
      • 6.2.3. Construction
      • 6.2.4. Chemical Industry
      • 6.2.5. Other
    • 6.3. Market Analysis, Insights and Forecast - by Coating Type
      • 6.3.1. 3LPE/3LPP
      • 6.3.2. FBE
      • 6.3.3. Cement Mortar Lining
      • 6.3.4. Others
    • 6.4. Market Analysis, Insights and Forecast - by Grade & Standard
      • 6.4.1. API 5L
      • 6.4.2. ASTM A252/A53
      • 6.4.3. EN 10217
      • 6.4.4. Others
    • 6.5. Market Analysis, Insights and Forecast - by Distribution Channel
      • 6.5.1. Direct/Project Tender
      • 6.5.2. Distributors & Stockists
  • 7. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
    • 7.1. Market Analysis, Insights and Forecast - by Type
      • 7.1.1. O.D. 18-24 Inches
      • 7.1.2. O.D. 24-48 Inches
      • 7.1.3. Above 48 Inches
    • 7.2. Market Analysis, Insights and Forecast - by Application
      • 7.2.1. Oil & Gas
      • 7.2.2. Water
      • 7.2.3. Construction
      • 7.2.4. Chemical Industry
      • 7.2.5. Other
    • 7.3. Market Analysis, Insights and Forecast - by Coating Type
      • 7.3.1. 3LPE/3LPP
      • 7.3.2. FBE
      • 7.3.3. Cement Mortar Lining
      • 7.3.4. Others
    • 7.4. Market Analysis, Insights and Forecast - by Grade & Standard
      • 7.4.1. API 5L
      • 7.4.2. ASTM A252/A53
      • 7.4.3. EN 10217
      • 7.4.4. Others
    • 7.5. Market Analysis, Insights and Forecast - by Distribution Channel
      • 7.5.1. Direct/Project Tender
      • 7.5.2. Distributors & Stockists
  • 8. North America Market Analysis, Insights and Forecast, 2020-2034
    • 8.1. Market Analysis, Insights and Forecast - by Type
      • 8.1.1. O.D. 18-24 Inches
      • 8.1.2. O.D. 24-48 Inches
      • 8.1.3. Above 48 Inches
    • 8.2. Market Analysis, Insights and Forecast - by Application
      • 8.2.1. Oil & Gas
      • 8.2.2. Water
      • 8.2.3. Construction
      • 8.2.4. Chemical Industry
      • 8.2.5. Other
    • 8.3. Market Analysis, Insights and Forecast - by Coating Type
      • 8.3.1. 3LPE/3LPP
      • 8.3.2. FBE
      • 8.3.3. Cement Mortar Lining
      • 8.3.4. Others
    • 8.4. Market Analysis, Insights and Forecast - by Grade & Standard
      • 8.4.1. API 5L
      • 8.4.2. ASTM A252/A53
      • 8.4.3. EN 10217
      • 8.4.4. Others
    • 8.5. Market Analysis, Insights and Forecast - by Distribution Channel
      • 8.5.1. Direct/Project Tender
      • 8.5.2. Distributors & Stockists
  • 9. Europe Market Analysis, Insights and Forecast, 2020-2034
    • 9.1. Market Analysis, Insights and Forecast - by Type
      • 9.1.1. O.D. 18-24 Inches
      • 9.1.2. O.D. 24-48 Inches
      • 9.1.3. Above 48 Inches
    • 9.2. Market Analysis, Insights and Forecast - by Application
      • 9.2.1. Oil & Gas
      • 9.2.2. Water
      • 9.2.3. Construction
      • 9.2.4. Chemical Industry
      • 9.2.5. Other
    • 9.3. Market Analysis, Insights and Forecast - by Coating Type
      • 9.3.1. 3LPE/3LPP
      • 9.3.2. FBE
      • 9.3.3. Cement Mortar Lining
      • 9.3.4. Others
    • 9.4. Market Analysis, Insights and Forecast - by Grade & Standard
      • 9.4.1. API 5L
      • 9.4.2. ASTM A252/A53
      • 9.4.3. EN 10217
      • 9.4.4. Others
    • 9.5. Market Analysis, Insights and Forecast - by Distribution Channel
      • 9.5.1. Direct/Project Tender
      • 9.5.2. Distributors & Stockists
  • 10. Latin America Market Analysis, Insights and Forecast, 2020-2034
    • 10.1. Market Analysis, Insights and Forecast - by Type
      • 10.1.1. O.D. 18-24 Inches
      • 10.1.2. O.D. 24-48 Inches
      • 10.1.3. Above 48 Inches
    • 10.2. Market Analysis, Insights and Forecast - by Application
      • 10.2.1. Oil & Gas
      • 10.2.2. Water
      • 10.2.3. Construction
      • 10.2.4. Chemical Industry
      • 10.2.5. Other
    • 10.3. Market Analysis, Insights and Forecast - by Coating Type
      • 10.3.1. 3LPE/3LPP
      • 10.3.2. FBE
      • 10.3.3. Cement Mortar Lining
      • 10.3.4. Others
    • 10.4. Market Analysis, Insights and Forecast - by Grade & Standard
      • 10.4.1. API 5L
      • 10.4.2. ASTM A252/A53
      • 10.4.3. EN 10217
      • 10.4.4. Others
    • 10.5. Market Analysis, Insights and Forecast - by Distribution Channel
      • 10.5.1. Direct/Project Tender
      • 10.5.2. Distributors & Stockists
  • 11. Competitive Analysis
    • 11.1. Company Profiles
      • 11.1.1. TMK Group
        • 11.1.1.1. Company Overview
        • 11.1.1.2. Products
        • 11.1.1.3. Company Financials
        • 11.1.1.4. SWOT Analysis
      • 11.1.2. Baoji Petroleum Steel Pipe
        • 11.1.2.1. Company Overview
        • 11.1.2.2. Products
        • 11.1.2.3. Company Financials
        • 11.1.2.4. SWOT Analysis
      • 11.1.3. Jindal SAW Ltd.
        • 11.1.3.1. Company Overview
        • 11.1.3.2. Products
        • 11.1.3.3. Company Financials
        • 11.1.3.4. SWOT Analysis
      • 11.1.4. Welspun
        • 11.1.4.1. Company Overview
        • 11.1.4.2. Products
        • 11.1.4.3. Company Financials
        • 11.1.4.4. SWOT Analysis
      • 11.1.5. EUROPIPE GmbH
        • 11.1.5.1. Company Overview
        • 11.1.5.2. Products
        • 11.1.5.3. Company Financials
        • 11.1.5.4. SWOT Analysis
      • 11.1.6. EEW Group
        • 11.1.6.1. Company Overview
        • 11.1.6.2. Products
        • 11.1.6.3. Company Financials
        • 11.1.6.4. SWOT Analysis
      • 11.1.7. JFE Steel Corporation
        • 11.1.7.1. Company Overview
        • 11.1.7.2. Products
        • 11.1.7.3. Company Financials
        • 11.1.7.4. SWOT Analysis
      • 11.1.8. SEVERSTAL
        • 11.1.8.1. Company Overview
        • 11.1.8.2. Products
        • 11.1.8.3. Company Financials
        • 11.1.8.4. SWOT Analysis
      • 11.1.9. JSW Steel Ltd.
        • 11.1.9.1. Company Overview
        • 11.1.9.2. Products
        • 11.1.9.3. Company Financials
        • 11.1.9.4. SWOT Analysis
      • 11.1.10. OMK
        • 11.1.10.1. Company Overview
        • 11.1.10.2. Products
        • 11.1.10.3. Company Financials
        • 11.1.10.4. SWOT Analysis
      • 11.1.11. Cangzhou Spiral Steel Pipes Group Co. Ltd.
        • 11.1.11.1. Company Overview
        • 11.1.11.2. Products
        • 11.1.11.3. Company Financials
        • 11.1.11.4. SWOT Analysis
      • 11.1.12. Tianjin You Fa Steel Pipe Group
        • 11.1.12.1. Company Overview
        • 11.1.12.2. Products
        • 11.1.12.3. Company Financials
        • 11.1.12.4. SWOT Analysis
      • 11.1.13. Jiangsu Yulong Steel Pipe Technology Co. Ltd.
        • 11.1.13.1. Company Overview
        • 11.1.13.2. Products
        • 11.1.13.3. Company Financials
        • 11.1.13.4. SWOT Analysis
      • 11.1.14. Nippon Steel Corporation
        • 11.1.14.1. Company Overview
        • 11.1.14.2. Products
        • 11.1.14.3. Company Financials
        • 11.1.14.4. SWOT Analysis
      • 11.1.15. Panyu Chu Kong Steel Pipe
        • 11.1.15.1. Company Overview
        • 11.1.15.2. Products
        • 11.1.15.3. Company Financials
        • 11.1.15.4. SWOT Analysis
      • 11.1.16. ArcelorMittal
        • 11.1.16.1. Company Overview
        • 11.1.16.2. Products
        • 11.1.16.3. Company Financials
        • 11.1.16.4. SWOT Analysis
      • 11.1.17. Zhejiang Kingland & Pipeline Technologies Co. Ltd.
        • 11.1.17.1. Company Overview
        • 11.1.17.2. Products
        • 11.1.17.3. Company Financials
        • 11.1.17.4. SWOT Analysis
      • 11.1.18. Shengli Oil & Gas Pipe
        • 11.1.18.1. Company Overview
        • 11.1.18.2. Products
        • 11.1.18.3. Company Financials
        • 11.1.18.4. SWOT Analysis
      • 11.1.19. Global Pipe Company
        • 11.1.19.1. Company Overview
        • 11.1.19.2. Products
        • 11.1.19.3. Company Financials
        • 11.1.19.4. SWOT Analysis
      • 11.1.20. Arabian Pipes Company
        • 11.1.20.1. Company Overview
        • 11.1.20.2. Products
        • 11.1.20.3. Company Financials
        • 11.1.20.4. SWOT Analysis
      • 11.1.21. Borusan Mannesmann
        • 11.1.21.1. Company Overview
        • 11.1.21.2. Products
        • 11.1.21.3. Company Financials
        • 11.1.21.4. SWOT Analysis
      • 11.1.22. American SpiralWeld Pipe Company
        • 11.1.22.1. Company Overview
        • 11.1.22.2. Products
        • 11.1.22.3. Company Financials
        • 11.1.22.4. SWOT Analysis
      • 11.1.23. Essar Steel
        • 11.1.23.1. Company Overview
        • 11.1.23.2. Products
        • 11.1.23.3. Company Financials
        • 11.1.23.4. SWOT Analysis
      • 11.1.24. CNPC Bohai Equipment Manufacturing
        • 11.1.24.1. Company Overview
        • 11.1.24.2. Products
        • 11.1.24.3. Company Financials
        • 11.1.24.4. SWOT Analysis
      • 11.1.25. Baosteel
        • 11.1.25.1. Company Overview
        • 11.1.25.2. Products
        • 11.1.25.3. Company Financials
        • 11.1.25.4. SWOT Analysis
    • 11.2. Market Entropy
      • 11.2.1. Company's Key Areas Served
      • 11.2.2. Recent Developments
    • 11.3. Company Market Share Analysis, 2026
      • 11.3.1. Top 5 Companies Market Share Analysis
      • 11.3.2. Top 3 Companies Market Share Analysis
    • 11.4. List of Potential Customers
  • List of Figures

    1. Figure 1: Global Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
    2. Figure 2: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Type 2026 & 2034
    3. Figure 3: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Type 2026 & 2034
    4. Figure 4: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Application 2026 & 2034
    5. Figure 5: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Application 2026 & 2034
    6. Figure 6: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Coating Type 2026 & 2034
    7. Figure 7: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Coating Type 2026 & 2034
    8. Figure 8: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Grade & Standard 2026 & 2034
    9. Figure 9: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Grade & Standard 2026 & 2034
    10. Figure 10: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Distribution Channel 2026 & 2034
    11. Figure 11: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Distribution Channel 2026 & 2034
    12. Figure 12: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Country 2026 & 2034
    13. Figure 13: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Country 2026 & 2034
    14. Figure 14: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Type 2026 & 2034
    15. Figure 15: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Type 2026 & 2034
    16. Figure 16: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Application 2026 & 2034
    17. Figure 17: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Application 2026 & 2034
    18. Figure 18: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Coating Type 2026 & 2034
    19. Figure 19: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Coating Type 2026 & 2034
    20. Figure 20: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Grade & Standard 2026 & 2034
    21. Figure 21: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Grade & Standard 2026 & 2034
    22. Figure 22: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Distribution Channel 2026 & 2034
    23. Figure 23: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Distribution Channel 2026 & 2034
    24. Figure 24: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Country 2026 & 2034
    25. Figure 25: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Country 2026 & 2034
    26. Figure 26: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Type 2026 & 2034
    27. Figure 27: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Type 2026 & 2034
    28. Figure 28: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Application 2026 & 2034
    29. Figure 29: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Application 2026 & 2034
    30. Figure 30: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Coating Type 2026 & 2034
    31. Figure 31: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Coating Type 2026 & 2034
    32. Figure 32: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Grade & Standard 2026 & 2034
    33. Figure 33: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Grade & Standard 2026 & 2034
    34. Figure 34: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Distribution Channel 2026 & 2034
    35. Figure 35: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Distribution Channel 2026 & 2034
    36. Figure 36: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Country 2026 & 2034
    37. Figure 37: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Country 2026 & 2034
    38. Figure 38: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Type 2026 & 2034
    39. Figure 39: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Type 2026 & 2034
    40. Figure 40: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Application 2026 & 2034
    41. Figure 41: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Application 2026 & 2034
    42. Figure 42: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Coating Type 2026 & 2034
    43. Figure 43: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Coating Type 2026 & 2034
    44. Figure 44: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Grade & Standard 2026 & 2034
    45. Figure 45: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Grade & Standard 2026 & 2034
    46. Figure 46: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Distribution Channel 2026 & 2034
    47. Figure 47: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Distribution Channel 2026 & 2034
    48. Figure 48: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Country 2026 & 2034
    49. Figure 49: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Country 2026 & 2034
    50. Figure 50: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Type 2026 & 2034
    51. Figure 51: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Type 2026 & 2034
    52. Figure 52: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Application 2026 & 2034
    53. Figure 53: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Application 2026 & 2034
    54. Figure 54: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Coating Type 2026 & 2034
    55. Figure 55: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Coating Type 2026 & 2034
    56. Figure 56: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Grade & Standard 2026 & 2034
    57. Figure 57: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Grade & Standard 2026 & 2034
    58. Figure 58: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Distribution Channel 2026 & 2034
    59. Figure 59: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Distribution Channel 2026 & 2034
    60. Figure 60: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion), by Country 2026 & 2034
    61. Figure 61: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Share (%), by Country 2026 & 2034

    List of Tables

    1. Table 1: Global Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Type 2020 & 2034
    2. Table 2: Global Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Application 2020 & 2034
    3. Table 3: Global Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Coating Type 2020 & 2034
    4. Table 4: Global Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Grade & Standard 2020 & 2034
    5. Table 5: Global Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    6. Table 6: Global Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Region 2020 & 2034
    7. Table 7: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Type 2020 & 2034
    8. Table 8: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Application 2020 & 2034
    9. Table 9: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Coating Type 2020 & 2034
    10. Table 10: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Grade & Standard 2020 & 2034
    11. Table 11: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    12. Table 12: Asia Pacific Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Country 2020 & 2034
    13. Table 13: China Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion) Forecast, by Application 2020 & 2034
    14. Table 14: India Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion) Forecast, by Application 2020 & 2034
    15. Table 15: Japan Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion) Forecast, by Application 2020 & 2034
    16. Table 16: South Korea Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion) Forecast, by Application 2020 & 2034
    17. Table 17: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Type 2020 & 2034
    18. Table 18: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Application 2020 & 2034
    19. Table 19: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Coating Type 2020 & 2034
    20. Table 20: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Grade & Standard 2020 & 2034
    21. Table 21: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    22. Table 22: Middle East & Africa Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Country 2020 & 2034
    23. Table 23: Saudi Arabia Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion) Forecast, by Application 2020 & 2034
    24. Table 24: UAE Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion) Forecast, by Application 2020 & 2034
    25. Table 25: Turkey Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion) Forecast, by Application 2020 & 2034
    26. Table 26: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Type 2020 & 2034
    27. Table 27: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Application 2020 & 2034
    28. Table 28: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Coating Type 2020 & 2034
    29. Table 29: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Grade & Standard 2020 & 2034
    30. Table 30: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    31. Table 31: North America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Country 2020 & 2034
    32. Table 32: USA Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion) Forecast, by Application 2020 & 2034
    33. Table 33: Canada Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion) Forecast, by Application 2020 & 2034
    34. Table 34: Mexico Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion) Forecast, by Application 2020 & 2034
    35. Table 35: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Type 2020 & 2034
    36. Table 36: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Application 2020 & 2034
    37. Table 37: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Coating Type 2020 & 2034
    38. Table 38: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Grade & Standard 2020 & 2034
    39. Table 39: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    40. Table 40: Europe Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Country 2020 & 2034
    41. Table 41: Germany Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion) Forecast, by Application 2020 & 2034
    42. Table 42: UK Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion) Forecast, by Application 2020 & 2034
    43. Table 43: France Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion) Forecast, by Application 2020 & 2034
    44. Table 44: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Type 2020 & 2034
    45. Table 45: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Application 2020 & 2034
    46. Table 46: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Coating Type 2020 & 2034
    47. Table 47: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Grade & Standard 2020 & 2034
    48. Table 48: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    49. Table 49: Latin America Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue Billion Forecast, by Country 2020 & 2034
    50. Table 50: Brazil Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion) Forecast, by Application 2020 & 2034
    51. Table 51: Argentina Spiral Submerged Arc Welded (SSAW) Steel Pipe Market Revenue (Billion) Forecast, by Application 2020 & 2034

    Frequently Asked Questions

    1What is the SSAW steel pipe market size in 2025?

    Our proprietary modeling values the global Spiral Submerged Arc Welded steel pipe market at USD 6.5 Billion in 2025, with a projected rise to USD 10.71 Billion by 2034 at a 5.71% CAGR.

    2Which region dominates the SSAW steel pipe market?

    Asia Pacific leads with 41.4% of global 2025 revenue (USD 2.69 Billion), rising to 44% by 2034. China alone accounts for USD 1.29 Billion, or 48% of regional revenue.

    3Which SSAW pipe diameter segment grows fastest?

    Above 48 inches is the fastest-growing type line at 6.87% CAGR, moving from 30.8% to 34% of revenue share, while O.D. 24–48 inches remains the largest segment at 46.6%.

    4Why is water overtaking oil and gas in SSAW pipe demand?

    Water applications grow at 6.7% CAGR versus 5.05% for Oil & Gas, lifting water's share from 34% to 37% by 2034 as municipal and irrigation infrastructure programs expand.

    5How does the EU 'melt and pour' rule affect SSAW pipe exporters?

    From 1 October 2026, EU importers must declare the steel's country of melt and pour with a Mill Test Certificate and heat number, under a framework setting 18.3 million tonnes of duty-free quota and 50% duty above it.

    6Who are the leading manufacturers of SSAW steel pipe?

    Key producers include TMK Group, Baoji Petroleum Steel Pipe, Jindal SAW, Welspun, EUROPIPE, EEW Group, JFE Steel, Borusan Mannesmann, Arabian Pipes, and Chinese specialists such as Jiangsu Yulong and Cangzhou Spiral Steel Pipes.

    Methodology

    Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.

    Primary Research

    • Between 70% and 80% of the evidence base for this report derives from primary research conducted directly by our analyst teams, with the remaining 20% to 30% sourced from secondary benchmarking.
    • We conducted structured interviews and surveys with 4–5 distinct company types in the SSAW value chain: integrated steel coil producers supplying pipe mills, large-diameter SSAW/HSAW pipe manufacturers, coating applicators specializing in 3LPE/3LPP and FBE systems, EPC contractors and pipeline construction firms, and distributors and stockists serving utility and industrial demand.
    • Interviewee job titles included Procurement Directors, Pipeline Engineering Managers, Commercial Directors at pipe mills, and Supply Chain Heads at EPC contractors.
    • We benchmarked specifications and quality practices against bodies including the American Petroleum Institute (API 5L), the International Organization for Standardization (ISO 3183), the American Society for Testing and Materials (ASTM), and the European Committee for Standardization (EN 10217).
    • Primary fieldwork was complemented by channel checks along the coil-to-pipe conversion chain, including mill utilization tracking and project tender monitoring.

    Key Stakeholders Interviewed

    Main Logo
    Key Stakeholders Interviewed
    Stakeholder RoleInterview Share (%)
    Procurement Director30%
    Pipeline Engineering Manager26%
    Commercial Director (Pipe Mill)24%
    Supply Chain Head (EPC)20%

    Industry Ecosystem Breakdown

    Main Logo
    Industry Ecosystem Breakdown
    Company TypeRepresentation (%)
    SSAW/HSAW Pipe Manufacturers32%
    Steel Coil Suppliers & Integrated Mills22%
    EPC Contractors & Pipeline Operators20%
    Coating & Corrosion Protection Applicators14%
    Distributors & Stockists12%

    Secondary Research & Industry Benchmarking

    • Official trade statistics from UN Comtrade (HS 7305 and HS 7306) and the World Bank World Integrated Trade Solution were triangulated against national customs data to establish cross-border flow baselines.
    • Regulatory and policy filings, including the European Commission's Steel Regulation implementing act on 'melt and pour' evidence (DG Trade and Economic Security), were reviewed to model compliance-driven sourcing shifts.
    • Financial databases — Bloomberg, Factiva, Hoovers and PitchBook — were used to validate participant revenue, capacity and ownership structures across publicly listed and private pipe producers.
    • Standards and technical documentation from recognized non-profit trade and technical associations informed the specification segmentation and qualification-barrier analysis.
    • All secondary figures were normalized to a 2025 base year and USD denomination before triangulation.

    Demand Modeling & Market Estimation

    • We applied top-down and bottom-up methodologies simultaneously. The top-down approach allocated global and regional revenue envelopes across five segmentation axes (type, application, coating, grade and standard, and distribution channel).
    • The bottom-up approach built market size from unit-level quantitative metrics: installed SSAW mill capacity in tonnes per annum, average realized price per tonne by diameter band and coating specification, project-level pipeline award volumes in kilometers converted to tonnage, and utility water-distribution capital expenditure translated into large-diameter pipe consumption.
    • Every segment's revenue was verified to reconcile within the same total pool — application and type splits divide the same revenue and were never summed.
    • Regional estimates were developed as five independently modeled geographies, each with its own driver set, then reconciled to the global total via multi-level data triangulation.
    • Bear, base and bull scenarios were constructed around USD 9.42 Billion and USD 12 Billion bounds against the USD 10.71 Billion 2034 base case, with distinct steel-price, capex and policy assumptions for each.

    Data Accuracy & Quality Check

    • The dataset carries a guaranteed estimated accuracy level of 85–90%, validated through multi-level data triangulation across primary interviews, official trade statistics and financial disclosures.
    • Cross-consistency checks confirmed that 2020–2025 actuals align with reported 6.03% historical growth, and that forward rates reconcile with bottom-up capacity additions.
    • Country-level allocations were sense-checked against regional share trajectories, and all outlier responses were re-verified with a second independent respondent.
    • Every report is updated to the date of purchase, ensuring projections reflect the latest policy changes, tender awards and steel-price conditions.
    Author
    Khageshwar Rongkali

    Khageshwar Rongkali

    Senior Analyst

    As a Senior Analyst operating across Chemicals & Materials (including Bulk, Specialty & Fine Chemicals), Industrials, and Industrial Automation & Equipment, I deliver robust commercial due diligence and market-sizing projects. My expertise also spans Professional and Commercial Services, executing strategic research initiatives that break down intricate supply chain dynamics and competitive landscapes. Leveraging my experience in managing focused research teams, I ensure data-driven analysis that strengthens market positioning for global enterprises across industrial and consumer sectors.

    Get In Touch
    WHY IMD

    Verified research

    Analyst-reviewed data

    Updated Nov 05, 2026

    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    CUSTOM INTELLIGENCE

    Tailored for you

    • In-depth Analysis Tailored to Specified Regions or Segments
    • Company Profiles Customized to User Preferences
    • Customized Evaluation of Competitive Landscape to Meet Your Needs
    Ask for customization
    avatar

    Analyst at Providence Strategic Partners at Petaling Jaya

    Jared Wan

    I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

    avatar

    Internationalization Director

    Santiago Mejia Molina

    Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

    avatar

    Head of Product Management and Marketing

    Olaf Gleibe

    We are using your report, and it gave us valuable information."

    avatar

    Regional Director, Marketing and Business Development

    Lina Lim

    We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

    avatar

    VP of Sales

    DIGGLE Representative

    Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.

    artwork spiralartwork spiralRelated Reports
    artwork underline

    The raw materials for personal care market is set to grow at a 6.1% CAGR, reaching $27.1B by 2033, driven by natural and sustainable ingredient demand.

    Nov 2026|250 pages
    $2900.00

    High Speed Digital CCL market valued at $1.26B in 2025, growing at 5.1% CAGR to reach $2.07B by 2035. Rising demand from 5G, data centers, and automotive electronics.

    Nov 2026|206 pages
    $2900.00

    Composite resin tooth filling material market to reach $2.1B by 2035 at 5.2% CAGR, driven by aesthetic dentistry and nanohybrid innovations.

    Nov 2026|223 pages
    $2900.00

    The catalytic reforming catalyst market was valued at USD 1.24 billion in 2025 and is projected to reach USD 1.78 billion by 2034, growing at a 4.1% CAGR.

    Nov 2026|242 pages
    $2900.00
    Raw Materials for Personal Care Future Market Report 2026-2035
    View report
    High Speed Digital Copper Clad Laminate (CCL) Market 2025-2035
    View report
    Composite Resin Tooth Filling Material Market Report 2025-2035
    View report
    Catalytic Reforming Catalyst Market Size & Forecast 2026-2034
    View report