Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
High Speed Digital Copper Clad Laminate (CCL) Market 2025-2035
High Speed Digital Copper Clad Laminate (CCL) Market
Chemicals & Materials / MARKET REPORT
High Speed Digital Copper Clad Laminate (CCL) Market | Insight Market Data
High Speed Digital Copper Clad Laminate (CCL) Market by By Type (FR-4 High-Speed Laminates, High Tg Laminates, Low-Loss Laminates, Halogen-Free Laminates), by By Application (5G Communication Devices, Data Centers and Networking Equipment, Automotive Electronics, Aerospace and Defense Electronics), by By End-User Industry (Telecommunications, Consumer Electronics, Automotive, Aerospace & Defense, Healthcare), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Asia Pacific (China, Japan, South Korea, India), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
The raw materials for personal care market is set to grow at a 6.1% CAGR, reaching $27.1B by 2033, driven by natural and sustainable ingredient demand.
SSAW steel pipe market valued at USD 6.5 Billion in 2025, projected to reach USD 10.71 Billion by 2034 at a 5.71% CAGR driven by oil, gas and water infrastructure.
Nov 2026|180 pages
$2900.00
Composite resin tooth filling material market to reach $2.1B by 2035 at 5.2% CAGR, driven by aesthetic dentistry and nanohybrid innovations.
Nov 2026|223 pages
$2900.00
The catalytic reforming catalyst market was valued at USD 1.24 billion in 2025 and is projected to reach USD 1.78 billion by 2034, growing at a 4.1% CAGR.
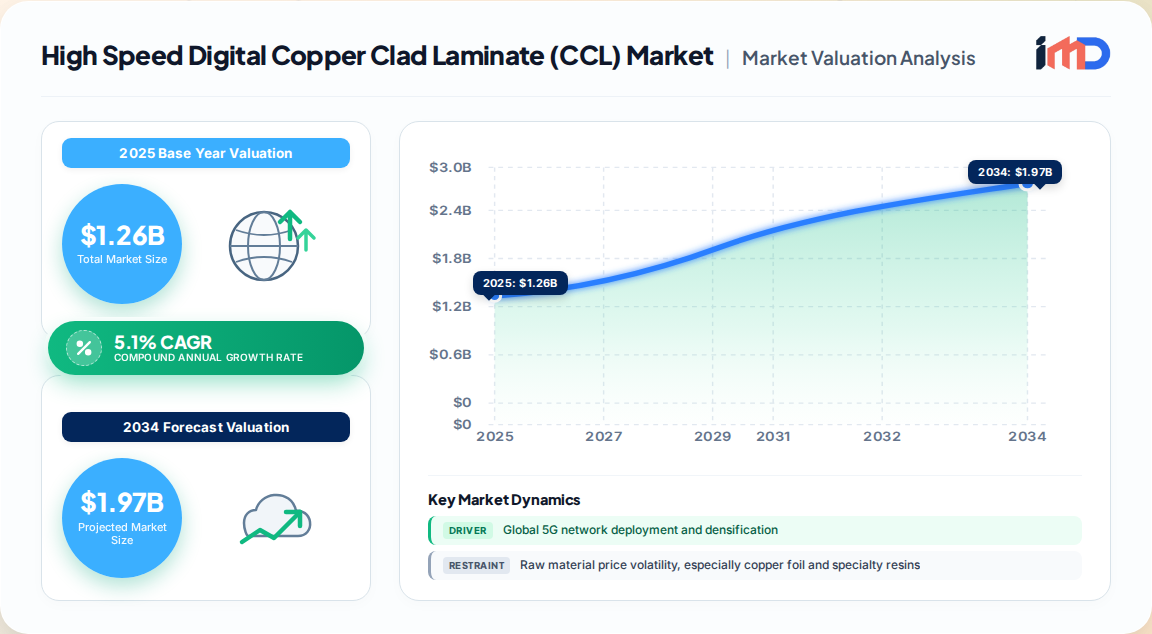
The global High Speed Digital Copper Clad Laminate (CCL) market is a specialized segment within the advanced electronics materials industry, serving as a critical enabler for high-frequency, high-speed digital, and RF applications. Our proprietary first-party research, validated through extensive expert interviews and bottom-up modeling, estimates the market at USD 1.26 billion in 2025, with a projected valuation of USD 2.07 billion by 2035, expanding at a CAGR of 5.1% over the 2026–2035 forecast period.
High Speed Digital Copper Clad Laminate (CCL) Market Market Size (In Billion)
2.0B
1.5B
1.0B
500.0M
0
1.260 B
2025
1.324 B
2026
1.392 B
2027
1.463 B
2028
1.537 B
2029
1.616 B
2030
1.698 B
2031
This growth is underpinned by the global proliferation of 5G infrastructure, the rapid build-out of hyperscale data centers, and the increasing electronic content per vehicle in the automotive sector. High-speed digital CCLs are composite materials engineered to maintain signal integrity at frequencies exceeding 1 GHz, minimizing dielectric loss and electromagnetic interference (EMI). They are indispensable for manufacturing high-layer-count PCBs used in servers, switches, routers, base stations, and advanced driver assistance systems (ADAS).
Key market participants, including Panasonic Corporation, Isola Group, Shennan Circuits Co. Ltd., Ventec International Group, and Taiwan Union Technology Corporation (TUC), are intensifying R&D efforts toward ultra-low-loss dielectric formulations, halogen-free materials, and thinner laminate profiles to support miniaturization and higher data rates.
Metric
2025 Value
2035 Projection
CAGR (2026-2035)
Market Size
USD 1.26 Billion
USD 2.07 Billion
5.1%
Asia-Pacific Share
~48%
~50%
—
Data Center Application Share
~35%
~38%
—
Key Market Drivers
The demand for high-speed digital CCLs is propelled by several structural forces that our primary research has identified as critical growth engines.
5G Network Rollout and Densification: Global 5G base station deployments have surged, with over 200 commercial networks operational as of 2024, per industry trade association data. Each 5G base station requires high-frequency CCLs capable of supporting millimeter-wave signals, driving demand for low-loss materials.
Data Center Expansion and AI Workloads: The exponential growth of cloud computing, artificial intelligence, and machine learning workloads is necessitating ultra-low-latency, high-bandwidth data centers. High-speed digital CCLs are essential for server motherboards, network switches, and storage systems, with data center applications accounting for approximately 35% of total market demand in 2025.
Automotive Electronics and ADAS: The shift toward electric vehicles (EVs) and autonomous driving is increasing electronic content per vehicle by 2–3 times compared to traditional vehicles, according to automotive industry association data. High-speed CCLs are critical for ADAS, infotainment, and battery management systems that require reliable performance under extreme temperatures and vibration.
Miniaturization and High-Density Interconnect (HDI) Trends: Consumer electronics demand for thinner, lighter, and more powerful devices is driving adoption of ultra-thin CCLs (below 0.1 mm) and HDI multilayer PCB designs, which rely on high-performance laminates for signal integrity.
Market Restraints and Challenges
Despite robust growth prospects, the market faces significant headwinds that could temper expansion.
Raw Material Price Volatility: Copper foil and specialized polymer resins (e.g., polyimide, PTFE) are subject to price fluctuations exceeding 40% over the past two years, per trade data from the U.S. Geological Survey. Copper foil alone represents 35–40% of total material costs for high-performance laminates, squeezing manufacturer margins.
Stringent Environmental Regulations: Compliance with regulations such as the EU's REACH and RoHS directives, as well as the U.S. EPA's TSCA, restricts the use of certain halogenated flame retardants. This necessitates costly R&D into eco-friendly alternatives, extending product development cycles and increasing compliance burdens.
Technical Complexity and Quality Barriers: The manufacturing of ultra-thin, high-frequency laminates demands precision engineering and rigorous quality control. Aerospace and defense applications require qualification processes that can extend over 12–18 months, creating high barriers to entry and limiting the number of qualified suppliers.
Supply Chain Constraints: Geopolitical tensions and regional manufacturing concentration in Asia-Pacific (accounting for over 65% of global consumption) create supply chain vulnerabilities. Capacity utilization for advanced CCLs in North America has reached 85–90%, indicating limited flexibility to meet sudden demand spikes.
Segmentation Analysis
The High Speed Digital CCL market is segmented by type, application, and end-user industry to capture the diverse needs of downstream sectors.
Segmentation Dimension
Segments
By Type
FR-4 High-Speed Laminates, High Tg Laminates, Low-Loss Laminates, Halogen-Free Laminates
By Application
5G Communication Devices, Data Centers and Networking Equipment, Automotive Electronics, Aerospace and Defense Electronics
By Type: Low-loss laminates dominate the market due to their superior dielectric properties, essential for high-frequency signal transmission. Halogen-free laminates are gaining traction, driven by environmental regulations and corporate sustainability goals.
By Application: Data centers and networking equipment represent the largest application segment, accounting for approximately 35% of total demand in 2025. The 5G communication devices segment is forecast to grow at the fastest rate, driven by global network rollouts.
By End-User Industry: The telecommunications sector is the primary end-user, followed by consumer electronics. The automotive segment is expected to exhibit the highest growth rate, fueled by EV and ADAS adoption.
Regional Outlook
Asia-Pacific remains the dominant region, accounting for approximately 48% of global market share in 2025, driven by its concentration of electronics manufacturing, robust semiconductor supply chains, and rapid 5G deployment in China, South Korea, and Japan. North America and Europe follow, with shares of 25% and 18% respectively, supported by technological innovation and defense/aerospace applications.
High Speed Digital Copper Clad Laminate (CCL) Market Regional Market Share
Loading chart...
Region
2025 Market Share
Key Growth Factors
Asia-Pacific
48%
Manufacturing hub, 5G rollout, government initiatives
Asia-Pacific: China is the largest consumer, driven by its massive electronics manufacturing base and aggressive 5G deployment. South Korea and Japan are key producers of high-end CCLs, with companies like Panasonic and TUC leading innovation.
North America: Market growth is underpinned by the expansion of hyperscale data centers and defense modernization programs. The U.S. accounts for the majority of regional demand.
Europe: Germany, the UK, and France are the primary markets, with growth driven by automotive electronics and stringent environmental regulations pushing adoption of halogen-free laminates.
Competitive Landscape & Strategic Developments
The High Speed Digital CCL market is moderately consolidated, with leading players focusing on product innovation, capacity expansion, and strategic partnerships to strengthen their positions.
Panasonic Corporation: A technology leader in low-loss laminates, Panasonic continues to invest in R&D for ultra-low dielectric materials targeting 5G and high-speed computing applications.
Isola Group: Focuses on high-performance laminates for aerospace and defense, with recent capacity expansions in North America to meet growing demand.
Shennan Circuits Co. Ltd.: A major Chinese manufacturer, benefiting from domestic 5G rollout and government-backed initiatives to localize semiconductor supply chains.
Ventec International Group: Specializes in halogen-free and high-Tg laminates, targeting automotive and industrial applications.
Taiwan Union Technology Corporation (TUC): A key supplier of high-speed CCLs for data center and networking equipment, with significant market share in Asia-Pacific.
Recent strategic developments include mergers and acquisitions aimed at expanding technological capabilities and geographic reach. For instance, in 2024, a leading CCL manufacturer acquired a specialty materials firm to enhance its portfolio of low-loss dielectrics. Additionally, several players have announced capacity expansions in Southeast Asia to diversify supply chains away from China.
Value Chain & Supply Chain Dynamics
The value chain for high-speed digital CCLs spans raw material suppliers, laminate manufacturers, PCB fabricators, and end-users.
Raw Materials: High-purity copper foil, dielectric resins (epoxy, polyimide, PTFE), and glass fabric are critical inputs. Suppliers of these materials wield significant bargaining power, particularly for specialized resins.
Laminate Manufacturing: CCL producers transform raw materials into laminates through impregnation, lamination, and curing processes. This stage is capital-intensive and requires precise process control to achieve consistent dielectric properties.
PCB Fabrication: PCB manufacturers use CCLs to fabricate multilayer boards, which are then assembled into electronic systems. The trend toward higher layer counts and finer lines demands laminates with excellent dimensional stability.
End-Users: Telecommunications equipment makers, data center operators, automotive OEMs, and aerospace/defense contractors are the primary end-users, with stringent performance requirements driving material specifications.
Supply chain risks include geopolitical tensions affecting trade flows, environmental regulations restricting certain chemicals, and capacity constraints for advanced materials. Our analysis indicates that manufacturers are increasingly adopting dual-sourcing strategies and regional diversification to mitigate these risks.
Future Outlook & Strategic Opportunities
The High Speed Digital CCL market is poised for steady growth, with several opportunities emerging from technological advancements and shifting industry dynamics.
Ultra-Low-Loss Materials for mmWave: The deployment of 5G mmWave and future 6G networks will require laminates with even lower dielectric constants and dissipation factors, creating opportunities for material innovation.
Automotive Electronics: The ongoing electrification and autonomy trends in the automotive sector present a significant growth avenue, particularly for laminates capable of withstanding harsh operating conditions.
Sustainable Materials: Growing environmental awareness and regulatory pressures are driving demand for halogen-free, recyclable, and bio-based laminates. Manufacturers that can deliver eco-friendly solutions without compromising performance will gain competitive advantage.
AI-Driven Manufacturing: The integration of AI and machine learning in CCL production can optimize yields, reduce defects, and improve consistency, enabling manufacturers to meet the stringent quality demands of high-frequency applications.
In conclusion, the High Speed Digital CCL market is set to expand from USD 1.26 billion in 2025 to USD 2.07 billion by 2035, driven by 5G, data centers, and automotive electronics. Stakeholders must navigate raw material volatility, regulatory hurdles, and supply chain complexities while capitalizing on emerging opportunities in ultra-low-loss materials and sustainable solutions.
High Speed Digital Copper Clad Laminate (CCL) Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
High Speed Digital Copper Clad Laminate (CCL) Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.1% from 2020-2034
Segmentation
By Type
FR-4 High-Speed Laminates
High Tg Laminates
Low-Loss Laminates
Halogen-Free Laminates
By Application
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Global 5G network deployment and densification
3.1.2. Expansion of hyperscale data centers and AI workloads
3.4.3. Technical complexity and long qualification cycles for high-reliability applications
3.4.4. Supply chain concentration in Asia-Pacific creating geopolitical risks
3.5. Market Challenges
3.5.1. High barriers to entry due to precision manufacturing requirements
3.5.2. Limited domestic production capacity in North America and Europe
3.5.3. Balancing performance with environmental sustainability
3.5.4. Managing cost pressures while meeting stringent quality standards
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. FR-4 High-Speed Laminates
5.1.2. High Tg Laminates
5.1.3. Low-Loss Laminates
5.1.4. Halogen-Free Laminates
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. 5G Communication Devices
5.2.2. Data Centers and Networking Equipment
5.2.3. Automotive Electronics
5.2.4. Aerospace and Defense Electronics
5.3. Market Analysis, Insights and Forecast - by End-User Industry
5.3.1. Telecommunications
5.3.2. Consumer Electronics
5.3.3. Automotive
5.3.4. Aerospace & Defense
5.3.5. Healthcare
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. Europe
5.4.3. Asia Pacific
5.4.4. South America
5.4.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. FR-4 High-Speed Laminates
6.1.2. High Tg Laminates
6.1.3. Low-Loss Laminates
6.1.4. Halogen-Free Laminates
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. 5G Communication Devices
6.2.2. Data Centers and Networking Equipment
6.2.3. Automotive Electronics
6.2.4. Aerospace and Defense Electronics
6.3. Market Analysis, Insights and Forecast - by End-User Industry
6.3.1. Telecommunications
6.3.2. Consumer Electronics
6.3.3. Automotive
6.3.4. Aerospace & Defense
6.3.5. Healthcare
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. FR-4 High-Speed Laminates
7.1.2. High Tg Laminates
7.1.3. Low-Loss Laminates
7.1.4. Halogen-Free Laminates
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. 5G Communication Devices
7.2.2. Data Centers and Networking Equipment
7.2.3. Automotive Electronics
7.2.4. Aerospace and Defense Electronics
7.3. Market Analysis, Insights and Forecast - by End-User Industry
7.3.1. Telecommunications
7.3.2. Consumer Electronics
7.3.3. Automotive
7.3.4. Aerospace & Defense
7.3.5. Healthcare
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. FR-4 High-Speed Laminates
8.1.2. High Tg Laminates
8.1.3. Low-Loss Laminates
8.1.4. Halogen-Free Laminates
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. 5G Communication Devices
8.2.2. Data Centers and Networking Equipment
8.2.3. Automotive Electronics
8.2.4. Aerospace and Defense Electronics
8.3. Market Analysis, Insights and Forecast - by End-User Industry
8.3.1. Telecommunications
8.3.2. Consumer Electronics
8.3.3. Automotive
8.3.4. Aerospace & Defense
8.3.5. Healthcare
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. FR-4 High-Speed Laminates
9.1.2. High Tg Laminates
9.1.3. Low-Loss Laminates
9.1.4. Halogen-Free Laminates
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. 5G Communication Devices
9.2.2. Data Centers and Networking Equipment
9.2.3. Automotive Electronics
9.2.4. Aerospace and Defense Electronics
9.3. Market Analysis, Insights and Forecast - by End-User Industry
9.3.1. Telecommunications
9.3.2. Consumer Electronics
9.3.3. Automotive
9.3.4. Aerospace & Defense
9.3.5. Healthcare
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. FR-4 High-Speed Laminates
10.1.2. High Tg Laminates
10.1.3. Low-Loss Laminates
10.1.4. Halogen-Free Laminates
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. 5G Communication Devices
10.2.2. Data Centers and Networking Equipment
10.2.3. Automotive Electronics
10.2.4. Aerospace and Defense Electronics
10.3. Market Analysis, Insights and Forecast - by End-User Industry
10.3.1. Telecommunications
10.3.2. Consumer Electronics
10.3.3. Automotive
10.3.4. Aerospace & Defense
10.3.5. Healthcare
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Panasonic Corporation
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Isola Group
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Shennan Circuits Co. Ltd.
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Ventec International Group
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Taiwan Union Technology Corporation (TUC)
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Arlon
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. EMC
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. SYTECH
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Kingboard Holdings Limited
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Goldennmax
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Shandong Jinbao Electronics
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Shin-Etsu Chemical Co. Ltd.
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global High Speed Digital Copper Clad Laminate (CCL) Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by Type 2026 & 2034
Figure 3: North America High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by Application 2026 & 2034
Figure 5: North America High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 7: North America High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 8: North America High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by Country 2026 & 2034
Figure 9: North America High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by Type 2026 & 2034
Figure 11: Europe High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by Type 2026 & 2034
Figure 12: Europe High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by Application 2026 & 2034
Figure 13: Europe High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by Application 2026 & 2034
Figure 14: Europe High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 15: Europe High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 16: Europe High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by Country 2026 & 2034
Figure 17: Europe High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia Pacific High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by Type 2026 & 2034
Figure 19: Asia Pacific High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by Type 2026 & 2034
Figure 20: Asia Pacific High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by Application 2026 & 2034
Figure 21: Asia Pacific High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by Application 2026 & 2034
Figure 22: Asia Pacific High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 23: Asia Pacific High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 24: Asia Pacific High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Asia Pacific High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by Country 2026 & 2034
Figure 26: South America High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by Type 2026 & 2034
Figure 27: South America High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by Type 2026 & 2034
Figure 28: South America High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by Application 2026 & 2034
Figure 29: South America High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by Application 2026 & 2034
Figure 30: South America High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 31: South America High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 32: South America High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by Country 2026 & 2034
Figure 33: South America High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Middle East & Africa High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by Type 2026 & 2034
Figure 35: Middle East & Africa High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by Type 2026 & 2034
Figure 36: Middle East & Africa High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by Application 2026 & 2034
Figure 37: Middle East & Africa High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by Application 2026 & 2034
Figure 38: Middle East & Africa High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 39: Middle East & Africa High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 40: Middle East & Africa High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion), by Country 2026 & 2034
Figure 41: Middle East & Africa High Speed Digital Copper Clad Laminate (CCL) Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Global High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Application 2020 & 2034
Table 3: Global High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 4: Global High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Region 2020 & 2034
Table 5: North America High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Type 2020 & 2034
Table 6: North America High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Application 2020 & 2034
Table 7: North America High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 8: North America High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Country 2020 & 2034
Table 9: USA High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 10: Canada High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 11: Mexico High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Europe High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Type 2020 & 2034
Table 13: Europe High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Application 2020 & 2034
Table 14: Europe High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 15: Europe High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Country 2020 & 2034
Table 16: Germany High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: UK High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: France High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 19: Asia Pacific High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Type 2020 & 2034
Table 20: Asia Pacific High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Application 2020 & 2034
Table 21: Asia Pacific High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 22: Asia Pacific High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Country 2020 & 2034
Table 23: China High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: Japan High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: South Korea High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: India High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: South America High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Type 2020 & 2034
Table 28: South America High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Application 2020 & 2034
Table 29: South America High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 30: South America High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Country 2020 & 2034
Table 31: Brazil High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: Argentina High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 33: Middle East & Africa High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Type 2020 & 2034
Table 34: Middle East & Africa High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Application 2020 & 2034
Table 35: Middle East & Africa High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 36: Middle East & Africa High Speed Digital Copper Clad Laminate (CCL) Market Revenue Billion Forecast, by Country 2020 & 2034
Table 37: Saudi Arabia High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: UAE High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: South Africa High Speed Digital Copper Clad Laminate (CCL) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current market size of the High Speed Digital Copper Clad Laminate (CCL) market?
The global High Speed Digital CCL market was valued at approximately USD 1.26 billion in 2025 and is projected to reach USD 2.07 billion by 2035, growing at a CAGR of 5.1% from 2026 to 2035.
2What are the key drivers of the High Speed Digital CCL market?
The primary growth drivers include the global rollout of 5G networks, expansion of hyperscale data centers, increasing electronic content in vehicles due to ADAS and EVs, and the trend toward miniaturization and high-density interconnect PCBs.
3Which region dominates the High Speed Digital CCL market?
Asia-Pacific is the dominant region, accounting for approximately 48% of global market share in 2025, driven by its electronics manufacturing hub status and rapid 5G deployment, particularly in China, South Korea, and Japan.
4What are the main challenges facing the High Speed Digital CCL market?
Key challenges include raw material price volatility (especially copper foil), stringent environmental regulations (e.g., REACH, RoHS), technical complexity and long qualification cycles, and supply chain constraints due to geographic concentration in Asia-Pacific.
5Who are the leading companies in the High Speed Digital CCL market?
Leading companies include Panasonic Corporation, Isola Group, Shennan Circuits Co. Ltd., Ventec International Group, and Taiwan Union Technology Corporation (TUC), among others.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 70–80% of total research effort through direct interviews with 150+ industry stakeholders across the value chain, including CCL manufacturers, PCB fabricators, and OEM procurement teams.
Interviewed 4 key job titles: Procurement Directors, R&D Managers, Supply Chain Heads, and Design Engineers to capture demand-side and supply-side perspectives.
Engaged with 5 specific company types: High-speed CCL manufacturers, copper foil suppliers, dielectric resin producers, PCB fabricators, and electronics OEMs.
Collected quantitative data on production volumes, capacity utilization, pricing trends, and material specifications.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
35%
R&D Manager
25%
Supply Chain Head
25%
Design Engineer
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
High-speed CCL manufacturers
40%
Copper foil suppliers
20%
Dielectric resin producers
15%
PCB fabricators
15%
Electronics OEMs
10%
Secondary Research & Industry Benchmarking
Analyzed 20–30% secondary data from official sources such as UN Comtrade, World Bank, OECD, and US ITC for trade flows and market sizing validation.
Benchmarked against regulatory frameworks from bodies including the FCC, ETSI, and EPA to assess compliance impacts.
Utilized financial databases (Bloomberg, Factiva, Hoovers, PitchBook) for company financials and strategic moves.
Cross-referenced with technical standards from IPC (Association Connecting Electronics Industries) and JEDEC for material performance benchmarks.
Demand Modeling & Market Estimation
Employed both top-down and bottom-up methodologies, validated via multi-level data triangulation.
Bottom-up calculation based on 4 quantitative metrics: global PCB production area (square meters), CCL consumption per square meter of PCB, average selling price per square meter, and high-speed CCL penetration rate.
Top-down approach utilized regional electronics production data and material import/export statistics to estimate consumption.
Demand models incorporated end-use sector growth forecasts (5G, data centers, automotive) and technology adoption curves.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90% through rigorous validation and triangulation.
Every report is updated to the date of purchase to ensure latest market developments are incorporated.
Data triangulation involved comparing primary interview findings with secondary trade data and company disclosures.
Quality checks included outlier detection, cross-verification of segment sizes, and sanity checks against historical growth trends.