1What is the current size of the thermal insulation materials market?
The global thermal insulation materials market is estimated at USD 77.57 Bn in 2026 and is expected to reach USD 121.34 Bn by 2033, growing at a CAGR of 6.6%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Thermal Insulation Materials Market
 by Material Type (Plastic Foam(Polystyrene Foam(XPS, EPS), Polyurethane Foam, Polyisocyanurate Foam, Others), Stone Wool, Fiberglass, Wood Fiber, Others(Perlite, Aerogel, Cellulose, Ceramic)), by Temperature Range (-160 °C to -50 °C, -49 °C to 0 °C, 1 °C to 100 °C, 1 °C to 650 °C), by End-Use Industry (Construction(Residential(Wall Insulation, Floor Insulation, Roof Insulation), Non-Residential(Wall Insulation, Floor Insulation, Roof Insulation)), Automotive, HVAC, Industrial, Others), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Russia, Rest of Europe), by Asia Pacific (China, Japan, India, Rest of Asia Pacific), by Latin America (Brazil, Mexico, Rest of Latin America), by Middle East & Africa (Saudi Arabia, UAE, Rest of MEA) Forecast 2026-2034

Senior Analyst


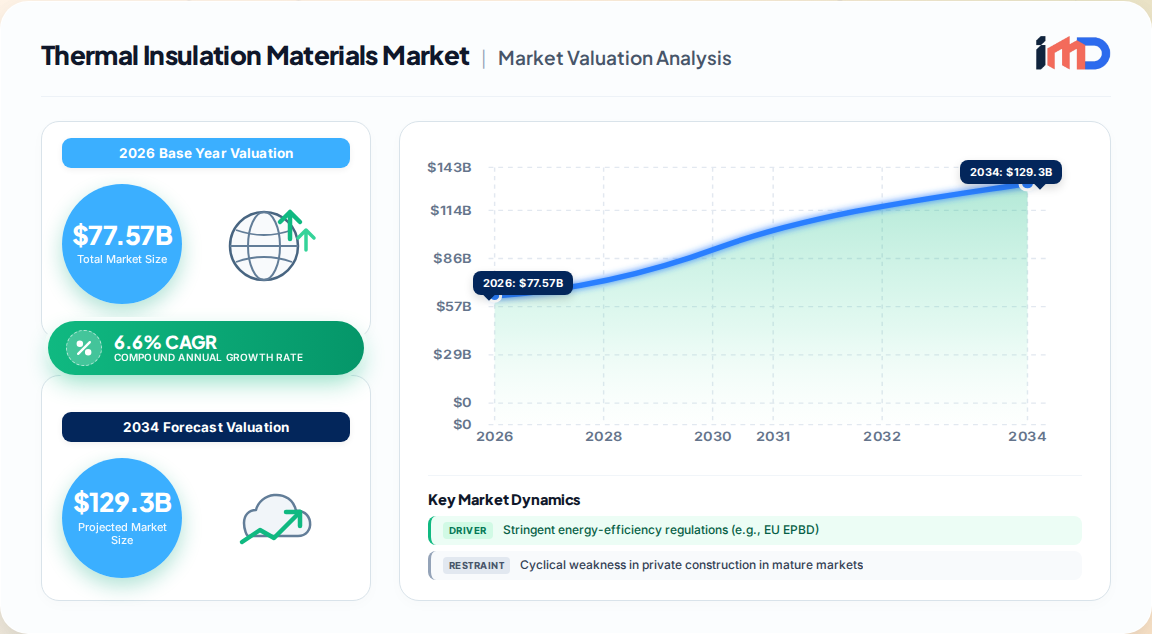
The global thermal insulation materials market is estimated at USD 77.57 Bn in 2026 and is projected to reach USD 121.34 Bn by 2033, expanding at a CAGR of 6.6% over the forecast period. This growth is underpinned by tightening energy-efficiency regulations, accelerating construction activity in emerging economies, and a growing retrofit pipeline in mature markets. Our proprietary bottom-up modeling, validated through multi-level data triangulation, suggests that value growth will increasingly be driven by specification intensity rather than material throughput alone, as project teams select higher-performance products to meet stricter thermal targets within constrained building envelopes.
| Material Type | Estimated Share (2026) | Key Characteristics |
|---|---|---|
| Plastic Foam | 46% | Exceptional thermal resistance, lightweight, cost-effective; includes PU, EPS, XPS, PIR |
| Stone Wool | ~25% | Fire resistance, sound absorption, high-temperature stability |
| Fiberglass | ~18% | Cost-effective, widely used in residential and commercial insulation |
| Others (Wood Fiber, Perlite, Aerogel, Cellulose, Ceramic) | ~11% | Niche applications, bio-based and high-performance segments |
Plastic foam's dominance is reinforced by ongoing innovation. In January 2025, researchers demonstrated a plant-based alternative to fossil fuels for plastic foam production, replacing up to 20% of petroleum-derived chemicals in polyurethane foams with lignin extracted from pine. This development is expected to accelerate the shift toward bio-based insulation materials.
Asia Pacific leads the global thermal insulation materials market with a 37% share in 2026, driven by rapid urbanization, infrastructure development, and formal housing programs in China, India, and Southeast Asia. China remains the largest individual market, supported by extensive construction activity and government-led energy-efficiency initiatives.
North America, holding a 23% share in 2026, is projected to be the fastest-growing region, with a CAGR above the global average. Growth is supported by stringent building codes, retrofit activity, and a recovery in residential construction from cyclical lows.
Europe represents a mature but policy-driven market, where the EPBD and Renovation Wave create a large, funded pipeline for deep retrofits. The region is expected to see above-global-average growth from 2026 onward, contingent on the execution of national renovation plans and accessible financing.
Latin America and the Middle East & Africa are smaller but growing markets, supported by urbanization, infrastructure investment, and increasing awareness of energy efficiency.
The thermal insulation materials market is moderately consolidated, with the top five players collectively holding a significant share. Key global players include Saint-Gobain, Owens Corning, Rockwool Group, Knauf Insulation, and Johns Manville. These companies are investing in capacity expansion, eco-friendly product innovation, and digitalized production lines to meet evolving demand for energy-efficient buildings.
Recent strategic developments include:
Global trade in thermal insulation materials is concentrated among a few key exporters. Between October 2023 and September 2024, a total of 1,181 shipments were exported globally, involving 375 exporters and 382 buyers, reflecting a 20% increase compared to the previous twelve-month period. China leads exports with 962 shipments, followed by Russia (384) and Poland (200). The majority of global exports were directed to Russia, Vietnam, and Kazakhstan.
Supply chain dynamics are increasingly shaped by sustainability requirements and regional trade policies. Manufacturers are investing in local production capacity to reduce logistics costs and carbon footprints, while also securing access to raw materials.
The thermal insulation materials value chain comprises raw material suppliers, manufacturers, distributors, contractors, and end-users. Key raw materials include petrochemicals for foam plastics, basalt and slag for stone wool, and silica sand for fiberglass. Manufacturers are increasingly integrating digital tools to optimize production and supply chain efficiency. Distributors and contractors play a critical role in specification and installation, particularly for retrofit projects where application engineering and contractor training are essential to achieve prescribed thermal outcomes.
Several white-space opportunities exist for market participants:
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.6% from 2020-2034 |
| Segmentation |
|
By Temperature Range
By End-Use Industry
| By Geography |
|
The global thermal insulation materials market is estimated at USD 77.57 Bn in 2026 and is expected to reach USD 121.34 Bn by 2033, growing at a CAGR of 6.6%.
Plastic foam holds the dominant share of 46% in 2026, owing to its exceptional thermal resistance, lightweight nature, and cost-effectiveness.
Asia Pacific leads the market with a 37% share in 2026, driven by rapid urbanization and construction activity in China, India, and Southeast Asia.
Key drivers include stricter energy-efficiency regulations (such as the EU EPBD), urbanization and new construction in Asia Pacific, rising energy costs, and technological advancements in materials like vacuum insulation panels.
Major players include Saint-Gobain, Owens Corning, Rockwool Group, Knauf Insulation, and Johns Manville, which collectively hold a significant market share.
North America is projected to be the fastest-growing region, with a CAGR above the global average, supported by stringent building codes and retrofit activity.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Product Manager | 25% |
| Technical/Engineering Manager | 25% |
| CEO/VP | 20% |
| Company Type | Representation (%) |
|---|---|
| Insulation Manufacturers | 40% |
| Raw Material Suppliers | 20% |
| Distributors and Retailers | 15% |
| Contractors and Installers | 15% |
| End-Users (Construction, HVAC, Industrial) | 10% |
 Related Reports
