1What is the size of the United Kingdom packaging market?
The UK packaging market is estimated at USD 62.26 billion in 2026 and is projected to reach USD 69.27 billion by 2031, growing at a CAGR of 2.16%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 United Kingdom Packaging Market
 by Packaging Type (Plastic, Paper, Container Glass, Metal Cans), by Packaging Format (Flexible, Rigid), by End-Use Industry (Food, Beverage, Pharmaceuticals, Personal Care, Industrial, E-Commerce), by England, by Scotland, by Wales, by Northern Ireland Forecast 2026-2034
Research Associate


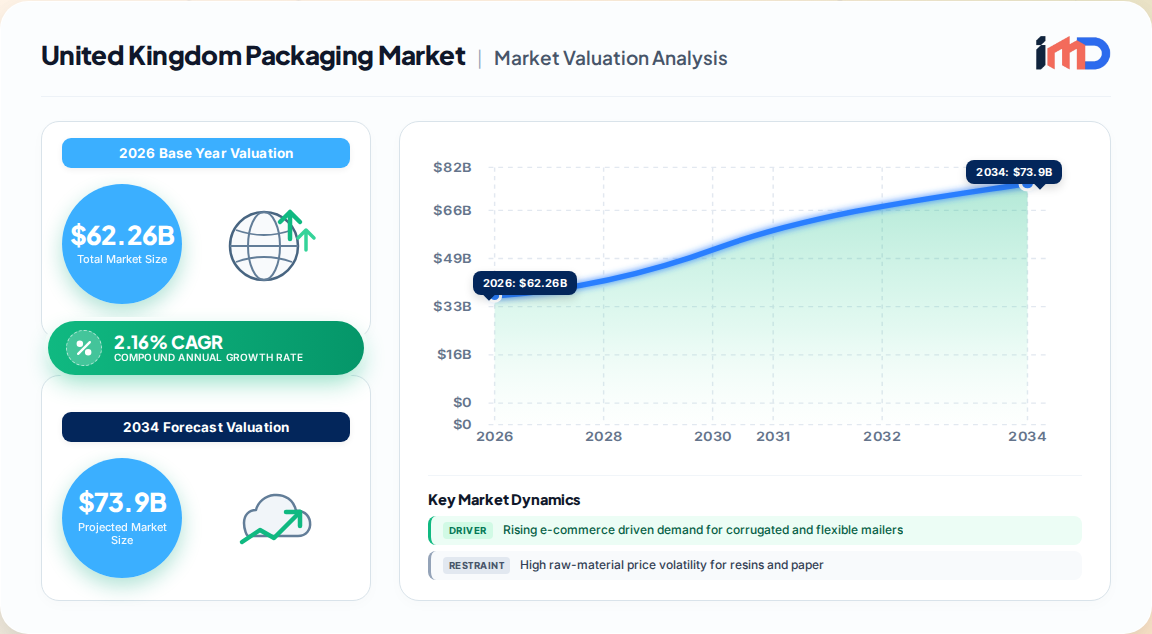
The United Kingdom packaging market is estimated at USD 62.26 billion in 2026, up from USD 60.94 billion in 2025, and is forecast to reach USD 69.27 billion by 2031, expanding at a CAGR of 2.16% over the forecast period. This growth reflects a mature but rapidly evolving landscape shaped by post-Brexit border rules, tightening environmental mandates, e-commerce acceleration, and pronounced cost inflation.
Structural adjustments under the Border Target Operating Model have raised compliance workloads and stretched lead times, prompting producers to localize inputs and automate customs documentation. Simultaneously, the expansion of the UK Plastic Packaging Tax and the full roll-out of Extended Producer Responsibility (EPR) have sharpened the focus on recyclability, driving rapid substitution toward paper, mono-material plastics, and bio-based films. Flexible formats have gained share as online retail reached 31.3% of national sales, and value-added printing capabilities helped brands target niche audiences cost-effectively.
Consolidation continues, highlighted by International Paper's USD 7.54 billion acquisition of DS Smith, which created the region's largest corrugated supplier but intensified antitrust scrutiny. The market concentration is medium, with the top five players—International Paper, Smurfit WestRock, Amcor, Mondi, and Ball Corporation—accounting for a significant share of revenues.
The UK packaging market is being reshaped by several powerful trends:
E-commerce driven demand for corrugated and flexible mailers: Online retail sales surged to 31.3% of national turnover in 2024, lifting shipment volumes for corrugated boxes and flexible mailers by 23%. Quick-commerce operators such as Getir stimulated single-portion packaging that combines tamper evidence with thermal integrity. Amazon's automated packing lines cut packaging material intensity 15% and accelerated outbound throughput, setting new efficiency benchmarks. Subscription models from HelloFresh amplified demand for returnable insulation, while marketplace sellers gravitated toward right-sized mailers that curb dimensional-weight charges.
Shift toward recyclable and biobased materials: The Plastic Packaging Tax extension in 2024 imposed a GBP 200 (USD 263) per-tonne levy on polymers lacking 30% recycled content, encouraging a 35% jump in reclaimed feedstock adoption. Unilever achieved 50% recycled plastic in UK personal-care lines, while Nestlé pledged fully recyclable solutions by 2025. Rising virgin resin differentials 18% above recycled inputs favor vertically integrated recyclers. Average compliance outlays reached GBP 2.3 million (USD 3.02 million) for large converters, prompting capital flows into wash-flake capacity and chemical recycling pilots.
Premiumization and luxury packaging demand: Luxury packaging volumes climbed 28% in 2024 as tourist arrivals rebounded to 85% of pre-pandemic levels. Brands such as Burberry shifted toward eco-certified specialty papers and decorative finishes that convey exclusivity without compromising recyclability. Digital print workflows enabled profitable micro-runs, with average batch sizes falling 35% while unit margins rose. Heathrow's duty-free outlets recorded 22% growth in high-value merchandise, raising demand for impact-resistant gift packs.
FMCG private label expansion in discount channels: Private label penetration reached 52% of grocery sales in 2024, propelled by discounters Aldi and Lidl. Tesco sought 15-20% unit-cost reductions through substrate light-weighting and supplier consolidation, catalyzing design-to-value initiatives. Inflation-driven bulk purchases lifted average pack sizes 12%, increasing corrugated transit packaging needs. Stricter allergen labeling heightened print complexity, favoring converters with inline variable-data capability.
Digital printing for short runs: Adoption of digital printing for short runs is enabling SME customization, with a +0.2% impact on CAGR forecast over the medium term. This trend is particularly pronounced in London, Bristol, and Leeds clusters.
Despite positive fundamentals, the market faces several headwinds:
High raw-material price volatility: Resin and paper prices have been volatile, particularly affecting manufacturing bases in the Midlands and North England. This restraint is expected to have a -0.7% impact on CAGR in the short term (≤ 2 years).
Strict UK regulations on single-use plastics and EPR costs: Compliance costs are highest in England and Wales, with a -0.5% impact on CAGR over the long term (≥ 4 years). The EPR scheme requires producers to cover the full net cost of managing packaging waste, adding significant financial burden.
Supply-chain disruptions post-Brexit: Import flows through Dover, Felixstowe, and Southampton ports have been affected, with a -0.4% impact on CAGR over the medium term (2-4 years). Customs delays and additional paperwork continue to challenge just-in-time supply chains.
Labor shortages: Manufacturing and logistics sectors face persistent labor shortages, with a -0.3% impact on CAGR nationally. This is exacerbated by post-Brexit immigration rules and an aging workforce.
Plastic held 48.02% of UK packaging market share in 2025, driven by its lightweight, durable, and versatile properties. However, environmental concerns and regulatory pressures are prompting a shift toward recycled content and alternatives.
Paper is projected to expand at a 4.62% CAGR through 2031, fueled by e-commerce demand for corrugated boxes and sustainable packaging initiatives. The segment benefits from high recycling rates and consumer preference for paper-based solutions.
Container glass remains important for premium beverages and food, though its weight and fragility limit growth.
Metal cans maintain steady demand in beverages and canned foods, with recycling infrastructure well-established.
Flexible solutions accounted for 54.40% of the UK packaging market size in 2025, favored for cost-efficiency, lightweight properties, and convenience. Stand-up pouches, sachets, and wrappers dominate food and personal care applications.
Rigid alternatives are forecast to grow at a 3.58% CAGR to 2031, driven by premiumization and the need for product protection in e-commerce.
Food applications led with 28.60% revenue share in 2025, supported by the growing demand for processed and convenience foods.
E-commerce packaging is advancing at a 5.28% CAGR through 2031, the fastest-growing end-use segment, as online retail continues to penetrate all categories.
Beverage, pharmaceuticals, personal care, and industrial segments also contribute significantly, with pharmaceuticals requiring specialized protective packaging.
The UK packaging market is moderately concentrated, with leading players pursuing strategies of consolidation, sustainability innovation, and digital transformation. Key companies include:
International Paper Company (including DS Smith): The acquisition of DS Smith for USD 7.54 billion created the region's largest corrugated supplier, with a strong focus on sustainable packaging solutions.
Smurfit WestRock: A global leader in paper-based packaging, formed through the merger of Smurfit Kappa and WestRock, with a significant presence in the UK corrugated market.
Amcor plc: A global packaging giant with a diverse portfolio spanning flexible and rigid plastics, specializing in healthcare and food packaging.
Mondi plc: A leading producer of sustainable paper and packaging solutions, with a strong focus on innovation and circular economy principles.
Ball Corporation: A major supplier of metal packaging for beverages, leveraging aluminum's infinite recyclability.
Other notable players include Owens Illinois, Crown Holdings, Sealed Air, Sonoco Products, Graphic Packaging International, Greif, Silgan Holdings, Can-Pack UK, Huhtamaki, Tetra Pak, Ardagh Group, AptarGroup, Stora Enso, and ProAmpac.
Recent developments include ProAmpac's launch of ProActive PCR Retort pouches in April 2022, designed for pet and human food packaging with post-consumer recycled content.
England dominates the UK packaging market, accounting for an estimated 62% share, driven by its dense population, high e-commerce penetration, and concentration of manufacturing and retail hubs in London, Manchester, and Birmingham. Scotland follows with 14%, Wales with 12%, and Northern Ireland with 12%.
England: The leading region, home to major packaging converters and brand owners. London and the South East are hotspots for premium and e-commerce packaging, while the Midlands is a manufacturing stronghold.
Scotland: Strong growth in food and beverage packaging, particularly Scotch whisky and seafood, with a focus on premium and sustainable solutions. The Scottish Government's deposit return scheme (DRS) is expected to drive innovation.
Wales: Consistent expansion, supported by food and drink manufacturing and a growing emphasis on circular economy initiatives. The Welsh Government's beyond recycling strategy is shaping packaging design.
Northern Ireland: Demand underpinned by agri-food sector and cross-border trade with the Republic of Ireland. The NI Protocol has created unique supply chain dynamics, with packaging flows requiring careful management.
The UK packaging value chain is complex and interconnected, spanning raw material suppliers, converters, brand owners, retailers, and waste management companies.
Raw material suppliers: Major chemical and paper companies supply resins, paperboard, glass, and metal. Price volatility in these inputs directly impacts converter margins.
Converters: Companies like Amcor, Mondi, and Smurfit WestRock transform raw materials into packaging formats. They invest in automation and digital printing to enhance efficiency and customization.
Brand owners and retailers: FMCG companies, food and beverage producers, and retailers drive demand, increasingly specifying sustainable packaging attributes.
Logistics and distribution: Packaging flows through complex logistics networks, with e-commerce fulfillment centers and retail distribution centers playing critical roles.
Waste management and recycling: The EPR scheme and Plastic Packaging Tax have elevated the importance of recycling infrastructure. Investment in mechanical and chemical recycling is accelerating to meet recycled content targets.
While the UK is a net importer of packaging materials, it also exports significant volumes of paper-based packaging. According to World Bank WITS data, the UK exported USD 19.69 million worth of plastic packaging articles to Ireland in 2024, representing a substantial share of Ireland's imports of such products. This underscores the strong trade relationship between the two countries.
Key supplier dynamics include:
Paper and board: The UK imports significant volumes from Scandinavia and mainland Europe, with Smurfit WestRock and Mondi being major suppliers. Domestic production is supplemented by imports to meet demand.
Plastics: The UK relies on imports of virgin and recycled polymers from Europe, the Middle East, and Asia. The Plastic Packaging Tax has incentivized domestic recycling capacity, reducing import dependence for recycled content.
Glass: Domestic glass manufacturing has declined, with imports from Europe filling the gap. Ardagh Group and Owens Illinois operate major facilities in the UK.
Metal: Ball Corporation and Crown Holdings dominate domestic metal packaging production, with raw materials sourced globally.
Post-Brexit border controls have added complexity to import/export flows, with customs documentation and regulatory checks increasing lead times. The Border Target Operating Model introduced in 2024 has necessitated advanced planning and automation to mitigate delays.
The UK packaging market presents several strategic opportunities:
Sustainable packaging innovation: With the Plastic Packaging Tax and EPR driving demand for recyclable and recycled-content packaging, companies investing in mono-material solutions, paper-based alternatives, and advanced recycling technologies stand to gain. The custom packaging segment, valued at USD 5.68 billion in 2025, is projected to reach USD 8.74 billion by 2035 at a 4.4% CAGR, with paper and paperboard accounting for 48.5% of demand.
E-commerce packaging optimization: As online retail continues to grow, demand for right-sized, protective, and sustainable e-commerce packaging will surge. Businesses offering automated packaging solutions and digital printing for personalization can capture value.
Smart and active packaging: The integration of QR codes, freshness indicators, and temperature-sensitive packaging is enhancing food safety and traceability, creating opportunities for technology providers and converters.
Circular economy collaborations: Partnerships across the value chain—from material suppliers to recyclers—will be essential to meet regulatory targets and consumer expectations. Deposit return schemes for beverage containers are expected to drive design changes.
The future outlook for the UK packaging market is one of steady, value-driven growth, with sustainability and digitalization as key pillars. Companies that proactively adapt to regulatory changes and invest in innovative, eco-friendly solutions will be best positioned to thrive.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 2.16% from 2020-2034 |
| Segmentation |
|

Analyst at Providence Strategic Partners at Petaling Jaya
I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

Internationalization Director
Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

Head of Product Management and Marketing
We are using your report, and it gave us valuable information."

Regional Director, Marketing and Business Development
We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

VP of Sales
Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.
By End-Use Industry
| By Geography |
|
The UK packaging market is estimated at USD 62.26 billion in 2026 and is projected to reach USD 69.27 billion by 2031, growing at a CAGR of 2.16%.
Plastic holds the largest share at 48.02% in 2025, but paper is the fastest-growing segment with a CAGR of 4.62% through 2031 due to sustainability trends.
Rising e-commerce demand, the shift toward recyclable and biobased materials due to the Plastic Packaging Tax, and premiumization are major drivers, contributing +0.8%, +0.6%, and +0.4% to CAGR respectively.
Leading companies include International Paper (including DS Smith), Smurfit WestRock, Amcor plc, Mondi plc, and Ball Corporation, among others.
Food applications lead with 28.60% revenue share in 2025, while e-commerce packaging is the fastest-growing segment at a CAGR of 5.28% through 2031.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Directors | 30% |
| Packaging Development Managers | 25% |
| Supply Chain Heads | 25% |
| Sustainability Officers | 20% |
| Company Type | Representation (%) |
|---|---|
| Packaging Converters | 40% |
| Raw Material Suppliers | 25% |
| Brand Owners & Retailers | 20% |
| Waste Management & Recycling Firms | 10% |
| Logistics & Distribution Providers | 5% |
 Related Reports
