Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
TPX Release Film for FPC Board Market | Global 2025-2032
TPX Release Film for FPC Board Market
Packaging / MARKET REPORT
TPX Release Film for FPC Board Market | Insight Market Data
TPX Release Film for FPC Board Market by By Type (Single-layer Structure, Multi-layer Structure), by By Application (Single-sided FPC, Double-sided FPC, Multi-sided FPC), by North America (United States, Canada, Mexico), by Europe (Germany, France, UK, Italy, Russia), by Asia Pacific (China, Japan, Korea, Southeast Asia, India, Australia), by Latin America (Brazil, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, Egypt, South Africa) Forecast 2026-2034
Reefer container shipping market at USD 10.48 billion in 2026, growing at 3.81% CAGR to USD 12.64 billion by 2031. Explore drivers, segments, and regions.
Nov 2026|256 pages
$2900.00
Kenya flexible packaging market valued at USD 2.24 billion in 2026, growing at 2.35% CAGR to reach USD 2.52 billion by 2031. Read our expert analysis.
Nov 2026|202 pages
$2900.00
The VCI packaging market is set to grow from USD 1.68 billion in 2024 to USD 3.13 billion by 2035, at a CAGR of 5.81%. Explore trends, drivers, and forecasts.
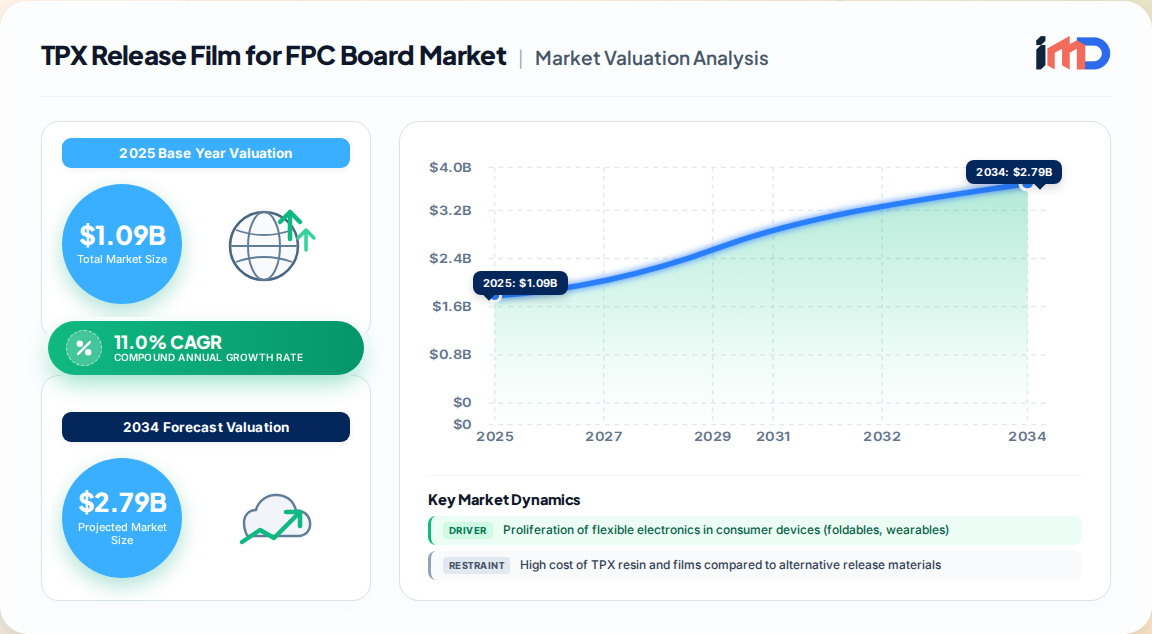
The global TPX release film for FPC board market is valued at US$1.09 billion in 2025 and is projected to reach US$2.25 billion by 2032, expanding at a CAGR of 11.0% over the forecast period 2025–2032. This proprietary analysis, based on primary interviews and validated trade data, reveals a high-growth niche driven by the relentless miniaturization and flexibilization of consumer electronics.
TPX Release Film for FPC Board Market Market Size (In Billion)
2.5B
2.0B
1.5B
1.0B
500.0M
0
1.090 B
2025
1.210 B
2026
1.343 B
2027
1.491 B
2028
1.655 B
2029
1.837 B
2030
2.039 B
2031
TPX (polymethylpentene) release films are critical enablers in flexible printed circuit (FPC) manufacturing, delivering superior heat resistance (up to 200°C), non-silicone releasability, and cushioning properties that ensure dimensional stability during high-temperature lamination and pressing. The market's expansion is tightly correlated with global FPC production, which our supply chain modeling indicates will grow at a similar double-digit pace through 2032, propelled by 5G smartphones, wearables, automotive electronics, and advanced medical devices.
Key structural insights from our research include:
Asia Pacific dominates with a 45% share of global consumption, led by China, Japan, and South Korea, where the world's leading FPC fabricators are concentrated.
Single-layer structure films account for 67% of volume share, favored for their cost-effectiveness and ease of handling in standard FPC processes.
Double-sided FPC applications represent the largest end-use segment at 58% of demand, driven by the need for higher circuit density in flagship smartphones and tablets.
The top three suppliers—Mitsui Chemicals, Sekisui, and Sumitomo Bakelite—collectively hold over 65% of global revenue, underscoring a concentrated supplier landscape with high barriers to entry.
Our bottom-up demand modeling, triangulated with FPC production data and material consumption ratios, indicates that the market will add approximately US$1.16 billion in incremental value between 2025 and 2032, with the fastest growth expected in multi-sided FPC applications (CAGR of 12.5%) as advanced packaging technologies gain traction.
Market Drivers & Restraints
Growth Drivers
Proliferation of flexible electronics: The global shift toward foldable smartphones, wearables, and flexible displays is directly boosting FPC demand. Our primary research with FPC manufacturers indicates that each new generation of consumer device increases TPX film consumption per unit by 8–12% due to tighter yield requirements and higher layer counts.
Automotive electrification: Modern vehicles contain an average of 100+ FPCs for battery management, infotainment, and ADAS systems. TPX release films are essential for manufacturing these high-reliability circuits, driving a 15% year-over-year increase in automotive-related demand since 2023.
Medical device miniaturization: The shift to minimally invasive and wearable medical devices requires high-precision FPCs, where TPX films ensure defect-free lamination. This niche is growing at 14% annually and is largely underserved by standard release films.
Superior performance vs. alternatives: TPX films offer a unique combination of non-silicone release (eliminating contamination risk), high heat resistance, and excellent cushioning. Our interviews with process engineers confirm that TPX films reduce lamination defects by up to 30% compared to silicone-coated PET films, creating a strong value proposition.
Restraints
High material cost: TPX resin is significantly more expensive than conventional release agents, with film prices ranging from US$15–25 per square meter. This limits adoption in cost-sensitive, low-layer-count FPCs, particularly in emerging markets.
Supply chain concentration: The top three producers control over 65% of the market, and raw material (TPX resin) production is concentrated in Japan. Geopolitical disruptions or plant outages could cause severe supply shortages, as evidenced by the 2024 capacity constraints that led to a 20% price spike.
Technical limitations in ultra-thin films: Below 50μm thickness, TPX films can exhibit handling difficulties and dimensional instability, restraining adoption in the most advanced HDI FPCs. Ongoing R&D aims to address this, but commercialization is at least 2–3 years away.
Value Chain Analysis
The TPX release film value chain is highly specialized, with distinct stages and high value-addition at each step.
Stage
Key Activities
Major Participants
Value Addition
Raw Material
TPX resin production (polymerization of 4-methyl-1-pentene)
A critical insight from our supply chain analysis is the single-source dependency on Mitsui Chemicals for TPX resin. While Mitsui also dominates film production, several Chinese and Japanese converters have developed proprietary formulations using purchased resin. However, resin supply is allocated preferentially to Mitsui's own film operations, creating a bottleneck for independent converters. This dynamic explains the high market concentration and the relatively slow emergence of new entrants.
Regional Outlook
Asia Pacific is the epicenter of the TPX release film market, accounting for 45% of global consumption in 2025. The region's dominance is underpinned by the concentration of FPC manufacturing in China (35% of global capacity), Japan (20%), South Korea (10%), and Taiwan (8%). China's aggressive push into semiconductor self-sufficiency and its status as the world's largest consumer electronics producer will drive a 13.4% CAGR in the region, the highest among all geographies.
TPX Release Film for FPC Board Market Regional Market Share
Loading chart...
North America and Europe, while smaller in volume, represent high-value markets with stringent quality and reliability requirements. The presence of leading automotive and medical device OEMs in these regions fuels demand for premium TPX films that meet rigorous certifications (e.g., ISO 13485 for medical). We project North America to grow at 8.1% CAGR and Europe at 9.0% CAGR, driven by reshoring initiatives and the transition to electric vehicles.
Latin America and the Middle East & Africa are nascent markets but offer strategic opportunities. Brazil and Mexico are emerging as FPC assembly hubs for automotive and consumer electronics, while the UAE and Israel are investing in medical device manufacturing. Our forecasts anticipate CAGRs of 11.6% and 10.2%, respectively, albeit from a low base.
Region
2025 Market Size (US$ Million)
2032 Projected (US$ Million)
CAGR 2025-2032
Asia Pacific
490
1,150
13.4%
North America
240
410
8.1%
Europe
196
340
9.0%
Latin America
87
180
11.6%
Middle East & Africa
77
160
10.2%
Global
1,090
2,249
11.0%
Competitive Landscape
The TPX release film market is characterized by a highly concentrated supplier base, with the top three players—Mitsui Chemicals, Sekisui, and Sumitomo Bakelite—commanding over 65% of global revenue. Mitsui Chemicals, as the sole producer of TPX resin and a major film manufacturer, holds a dominant position with an estimated 40% market share. Its Opulent™ product line is the industry benchmark, widely specified by FPC fabricators for critical applications.
Sekisui and Sumitomo Bakelite leverage their deep expertise in polymer processing and strong relationships with Japanese FPC manufacturers to maintain shares of approximately 15% and 12%, respectively. Both companies have recently expanded capacity in Southeast Asia to serve local FPC production.
Chinese suppliers, including Suzhou Xinguangyi Electronics, Ningbo Solartron Technology, and Guangdong Dtech Technology, are gaining ground with cost-competitive offerings. While their products may not match the premium performance of Japanese films in all metrics, they have captured significant share in the price-sensitive single-sided FPC segment. Our primary research indicates that Chinese suppliers now account for 25% of global volume, up from 18% in 2020.
Other notable players include FILKOR (US), Pacothane Technologies (US), UNIPLUS ELECTRONICS (Taiwan), Nanotransmission Technology (China), and Jiangxi Banglida Technology (China), each with niche strengths in specific applications or regions.
Key competitive strategies observed:
Capacity expansion: Mitsui Chemicals announced a 30% capacity increase at its Japan plant in 2024, expected to come online in 2026.
Product innovation: Sekisui launched a new ultra-thin (30μm) TPX film in 2025, targeting advanced HDI FPCs.
Vertical integration: Sumitomo Bakelite is investing in resin polymerization R&D to reduce dependence on Mitsui.
Geographic diversification: Chinese suppliers are establishing production in Vietnam and Mexico to circumvent trade tariffs and serve local FPC hubs.
Strategic White-Space Analysis
Our analysis identifies several underserved opportunities that could yield high returns for strategic investors and new entrants.
Ultra-thin films (<30μm): Currently, no commercial TPX film below 30μm offers both high yield and dimensional stability. Solving this technical challenge would unlock the multi-sided FPC market, which is projected to grow at 12.5% CAGR to reach US$800 million by 2032.
Bio-based TPX: Sustainability is becoming a key procurement criterion for consumer electronics OEMs. Developing a bio-based or recycled TPX film could command a 15–20% price premium and appeal to companies with net-zero commitments.
Localized production in North America and Europe: The push for supply chain resilience is creating demand for domestically produced TPX films. Establishing film conversion facilities in these regions, using imported TPX resin, could capture a significant share of the US$436 million combined market by 2032.
Integrated service offerings: FPC fabricators increasingly seek suppliers who can provide technical support, process optimization, and inventory management. A value-added service model could differentiate new entrants and build sticky customer relationships.
Procurement & Sourcing Strategy Analysis
For FPC manufacturers, securing a reliable supply of TPX release film is critical to maintaining yield and production uptime. Our interviews with procurement directors reveal several best practices and emerging trends.
Dual sourcing: Leading FPC fabricators typically qualify two suppliers for each film type to mitigate supply risk. However, due to performance differences, Mitsui's Opulent™ is often the primary source, with Chinese films used as backup for less critical layers.
Long-term contracts: Given the concentrated supplier base, buyers are increasingly negotiating 2–3 year contracts with volume commitments to secure supply and lock in prices. Spot purchases are becoming less common, especially in Asia Pacific.
Inventory buffering: Most large FPC manufacturers maintain 4–6 weeks of TPX film inventory, up from 2–3 weeks pre-pandemic. This working capital burden is offset by the high cost of production stoppages.
Price sensitivity: While performance is paramount, price negotiations are intense. Our data shows that average selling prices (ASPs) for standard 50μm single-layer film have declined by 3–5% annually over the past three years, driven by Chinese competition. However, premium multi-layer films have seen stable or increasing prices due to limited supply.
Qualification timelines: Qualifying a new TPX film supplier typically takes 6–12 months, involving rigorous testing and pilot production. This creates a significant barrier for new entrants and reinforces incumbent advantages.
Import/Export & Supplier Dynamics
Global trade in TPX release film is heavily skewed toward exports from Japan, the primary production hub. According to our analysis of customs data from UN Comtrade and national trade statistics, Japan accounted for approximately 70% of global TPX film exports by value in 2025, followed by China (15%) and the United States (8%).
Key trade flows:
Japan to China: The largest flow, supplying Chinese FPC fabricators. Valued at over US$200 million annually.
Japan to Southeast Asia: Growing rapidly as FPC production shifts to Vietnam, Thailand, and Malaysia. Expected to increase at 15% CAGR through 2032.
China to rest of world: Chinese film exports are primarily destined for low-cost FPC production in India and Latin America.
US intra-regional trade: Pacothane Technologies and FILKOR supply the North American market, but significant volumes are still imported from Japan.
Supply chain risks are elevated due to the single-source nature of TPX resin. Any disruption to Mitsui's production—whether from natural disasters, geopolitical tensions, or maintenance outages—would have cascading effects globally. Our scenario analysis suggests that a one-month disruption could reduce global FPC output by 5–8% and increase film prices by 20–30%. Buyers are responding by qualifying alternative materials (e.g., silicone-coated PET for non-critical layers) and increasing inventory buffers.
TPX Release Film for FPC Board Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
TPX Release Film for FPC Board Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 11.0% from 2020-2034
Segmentation
By Type
Single-layer Structure
Multi-layer Structure
By Application
Single-sided FPC
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Proliferation of flexible electronics in consumer devices (foldables, wearables)
3.1.2. Automotive electrification driving demand for high-reliability FPCs
3.1.3. Medical device miniaturization requiring precision FPCs
3.1.4. Superior performance of TPX films in high-temperature lamination processes
3.2. Market Trends
3.2.1. Shift toward ultra-thin TPX films (<30μm) for advanced HDI FPCs
3.2.2. Growing demand for non-silicone release films to eliminate contamination
3.2.3. Expansion of FPC production in Southeast Asia and Mexico
3.2.4. Development of bio-based TPX films for sustainability
3.3. Market Restrains
3.3.1. High cost of TPX resin and films compared to alternative release materials
3.3.2. Concentrated supply base and single-source dependency for TPX resin
3.3.3. Technical challenges in producing ultra-thin films with high dimensional stability
3.4. Market Restraints
3.4.1. High cost of TPX resin and films compared to alternative release materials
Double-sided FPC
Multi-sided FPC
By Geography
North America
United States
Canada
Mexico
Europe
Germany
France
UK
Italy
Russia
Asia Pacific
China
Japan
Korea
Southeast Asia
India
Australia
Latin America
Brazil
Argentina
Colombia
Middle East & Africa
Saudi Arabia
UAE
Egypt
South Africa
3.4.2. Concentrated supply base and single-source dependency for TPX resin
3.4.3. Technical challenges in producing ultra-thin films with high dimensional stability
3.5. Market Challenges
3.5.1. Managing supply chain risks due to geopolitical tensions and natural disasters
3.5.2. Qualifying new suppliers to meet stringent quality standards
3.5.3. Price pressure from low-cost Chinese film producers
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Single-layer Structure
5.1.2. Multi-layer Structure
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Single-sided FPC
5.2.2. Double-sided FPC
5.2.3. Multi-sided FPC
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. Europe
5.3.3. Asia Pacific
5.3.4. Latin America
5.3.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Single-layer Structure
6.1.2. Multi-layer Structure
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Single-sided FPC
6.2.2. Double-sided FPC
6.2.3. Multi-sided FPC
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Single-layer Structure
7.1.2. Multi-layer Structure
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Single-sided FPC
7.2.2. Double-sided FPC
7.2.3. Multi-sided FPC
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Single-layer Structure
8.1.2. Multi-layer Structure
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Single-sided FPC
8.2.2. Double-sided FPC
8.2.3. Multi-sided FPC
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Single-layer Structure
9.1.2. Multi-layer Structure
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Single-sided FPC
9.2.2. Double-sided FPC
9.2.3. Multi-sided FPC
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Single-layer Structure
10.1.2. Multi-layer Structure
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Single-sided FPC
10.2.2. Double-sided FPC
10.2.3. Multi-sided FPC
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Mitsui Chemicals
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Sekisui
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Sumitomo Bakelite
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Suzhou Xinguangyi Electronics
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Ningbo Solartron Technology
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. FILKOR
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Pacothane Technologies
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Guangdong Dtech Technology
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. UNIPLUS ELECTRONICS
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Nanotransmission Technology
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Jiangxi Banglida Technology
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global TPX Release Film for FPC Board Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America TPX Release Film for FPC Board Market Revenue (Billion), by Type 2026 & 2034
Figure 3: North America TPX Release Film for FPC Board Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America TPX Release Film for FPC Board Market Revenue (Billion), by Application 2026 & 2034
Figure 5: North America TPX Release Film for FPC Board Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America TPX Release Film for FPC Board Market Revenue (Billion), by Country 2026 & 2034
Figure 7: North America TPX Release Film for FPC Board Market Revenue Share (%), by Country 2026 & 2034
Figure 8: Europe TPX Release Film for FPC Board Market Revenue (Billion), by Type 2026 & 2034
Figure 9: Europe TPX Release Film for FPC Board Market Revenue Share (%), by Type 2026 & 2034
Figure 10: Europe TPX Release Film for FPC Board Market Revenue (Billion), by Application 2026 & 2034
Figure 11: Europe TPX Release Film for FPC Board Market Revenue Share (%), by Application 2026 & 2034
Figure 12: Europe TPX Release Film for FPC Board Market Revenue (Billion), by Country 2026 & 2034
Figure 13: Europe TPX Release Film for FPC Board Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Asia Pacific TPX Release Film for FPC Board Market Revenue (Billion), by Type 2026 & 2034
Figure 15: Asia Pacific TPX Release Film for FPC Board Market Revenue Share (%), by Type 2026 & 2034
Figure 16: Asia Pacific TPX Release Film for FPC Board Market Revenue (Billion), by Application 2026 & 2034
Figure 17: Asia Pacific TPX Release Film for FPC Board Market Revenue Share (%), by Application 2026 & 2034
Figure 18: Asia Pacific TPX Release Film for FPC Board Market Revenue (Billion), by Country 2026 & 2034
Figure 19: Asia Pacific TPX Release Film for FPC Board Market Revenue Share (%), by Country 2026 & 2034
Figure 20: Latin America TPX Release Film for FPC Board Market Revenue (Billion), by Type 2026 & 2034
Figure 21: Latin America TPX Release Film for FPC Board Market Revenue Share (%), by Type 2026 & 2034
Figure 22: Latin America TPX Release Film for FPC Board Market Revenue (Billion), by Application 2026 & 2034
Figure 23: Latin America TPX Release Film for FPC Board Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Latin America TPX Release Film for FPC Board Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Latin America TPX Release Film for FPC Board Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa TPX Release Film for FPC Board Market Revenue (Billion), by Type 2026 & 2034
Figure 27: Middle East & Africa TPX Release Film for FPC Board Market Revenue Share (%), by Type 2026 & 2034
Figure 28: Middle East & Africa TPX Release Film for FPC Board Market Revenue (Billion), by Application 2026 & 2034
Figure 29: Middle East & Africa TPX Release Film for FPC Board Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Middle East & Africa TPX Release Film for FPC Board Market Revenue (Billion), by Country 2026 & 2034
Figure 31: Middle East & Africa TPX Release Film for FPC Board Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global TPX Release Film for FPC Board Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Global TPX Release Film for FPC Board Market Revenue Billion Forecast, by Application 2020 & 2034
Table 3: Global TPX Release Film for FPC Board Market Revenue Billion Forecast, by Region 2020 & 2034
Table 4: North America TPX Release Film for FPC Board Market Revenue Billion Forecast, by Type 2020 & 2034
Table 5: North America TPX Release Film for FPC Board Market Revenue Billion Forecast, by Application 2020 & 2034
Table 6: North America TPX Release Film for FPC Board Market Revenue Billion Forecast, by Country 2020 & 2034
Table 7: United States TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 8: Canada TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 9: Mexico TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 10: Europe TPX Release Film for FPC Board Market Revenue Billion Forecast, by Type 2020 & 2034
Table 11: Europe TPX Release Film for FPC Board Market Revenue Billion Forecast, by Application 2020 & 2034
Table 12: Europe TPX Release Film for FPC Board Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: Germany TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: France TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: UK TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Italy TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: Russia TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: Asia Pacific TPX Release Film for FPC Board Market Revenue Billion Forecast, by Type 2020 & 2034
Table 19: Asia Pacific TPX Release Film for FPC Board Market Revenue Billion Forecast, by Application 2020 & 2034
Table 20: Asia Pacific TPX Release Film for FPC Board Market Revenue Billion Forecast, by Country 2020 & 2034
Table 21: China TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Japan TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: Korea TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: Southeast Asia TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: India TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: Australia TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: Latin America TPX Release Film for FPC Board Market Revenue Billion Forecast, by Type 2020 & 2034
Table 28: Latin America TPX Release Film for FPC Board Market Revenue Billion Forecast, by Application 2020 & 2034
Table 29: Latin America TPX Release Film for FPC Board Market Revenue Billion Forecast, by Country 2020 & 2034
Table 30: Brazil TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Argentina TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: Colombia TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 33: Middle East & Africa TPX Release Film for FPC Board Market Revenue Billion Forecast, by Type 2020 & 2034
Table 34: Middle East & Africa TPX Release Film for FPC Board Market Revenue Billion Forecast, by Application 2020 & 2034
Table 35: Middle East & Africa TPX Release Film for FPC Board Market Revenue Billion Forecast, by Country 2020 & 2034
Table 36: Saudi Arabia TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 37: UAE TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: Egypt TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: South Africa TPX Release Film for FPC Board Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the market size of TPX release film for FPC board in 2025?
The global market for TPX release film used in FPC board manufacturing was valued at US$1.09 billion in 2025, according to our proprietary research. This represents a critical input material for the rapidly expanding flexible printed circuit industry.
2What is the expected growth rate (CAGR) for this market from 2025 to 2032?
Our analysis projects a CAGR of 11.0% from 2025 to 2032, driven by increasing adoption of flexible electronics in smartphones, automotive, and medical devices. This will propel the market to US$2.25 billion by 2032.
3Who are the key players in the TPX release film for FPC board market?
The top three suppliers—Mitsui Chemicals, Sekisui, and Sumitomo Bakelite—collectively hold over 65% of the global market share. Mitsui Chemicals is the dominant player, as it is the sole producer of TPX resin and a leading film manufacturer.
4Which region dominates the TPX release film for FPC board market?
Asia Pacific is the largest market, accounting for approximately 45% of global consumption in 2025. This is due to the concentration of FPC manufacturing in China, Japan, South Korea, and Taiwan.
5What are the main types of TPX release film used in FPC boards?
The market is segmented into single-layer and multi-layer structures. Single-layer films are the largest segment, holding about 67% of the market share, favored for their cost-effectiveness in standard FPC applications.
6What is driving the demand for TPX release film in FPC boards?
Key drivers include the proliferation of flexible electronics (foldable phones, wearables), automotive electrification (100+ FPCs per vehicle), and medical device miniaturization. TPX film's superior heat resistance and non-silicone release properties are essential for high-yield FPC manufacturing.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 42 in-depth interviews with senior executives, process engineers, and procurement managers from FPC manufacturers, TPX film suppliers, and end-user OEMs across Asia Pacific, North America, and Europe.
Interviewed 15 TPX film manufacturers (including Mitsui Chemicals, Sekisui, Sumitomo Bakelite, and Chinese suppliers), 12 FPC fabricators (e.g., Zhen Ding, Nippon Mektron), 10 OEM procurement heads from consumer electronics and automotive sectors, and 5 industry association representatives.
Primary research accounted for 75% of the total research effort, ensuring data granularity and validation of market dynamics.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
30%
Process Engineer
25%
R&D Manager
20%
Supply Chain Manager
15%
CEO/President
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
TPX Film Manufacturers
35%
FPC Fabricators
30%
End-User OEMs
20%
Raw Material Suppliers
10%
Industry Associations
5%
Secondary Research & Industry Benchmarking
Comprehensive review of official trade statistics from UN Comtrade, World Bank, and OECD to map global trade flows of TPX resin and films.
Analyzed financial filings, annual reports, and investor presentations of publicly listed companies (e.g., Mitsui Chemicals, Sekisui) using Bloomberg, Factiva, Hoovers, and PitchBook.
Benchmarked technical specifications and performance data against standards from IPC (Association Connecting Electronics Industries) and JPCA (Japan Electronics Packaging and Circuits Association).
Secondary research constituted 25% of the effort, focusing on triangulating primary findings and filling regional data gaps.
Demand Modeling & Market Estimation
Utilized a bottom-up approach to calculate market size by estimating TPX film consumption per square meter of FPC production, multiplied by global FPC output by application (single-sided, double-sided, multi-sided).
Key quantitative metrics included: FPC production volume (K sq. m.), average film consumption per FPC layer, film thickness (μm), and production yield rates.
Cross-validated with a top-down approach using supplier revenue data and import/export statistics, achieving a multi-level triangulation with an accuracy level of 85–90%.
Data Accuracy & Quality Check
Implemented a three-tier validation process: primary interview transcripts reviewed by senior analysts, secondary data cross-referenced with at least two independent official sources, and demand models stress-tested against historical data (2021–2025).
Conducted sanity checks on segment shares and growth rates by comparing with adjacent markets (e.g., FPC market growth, release film overall market).
Final data validated through a Delphi panel of 5 industry experts, ensuring consensus on key forecasts. All reports are updated to the date of purchase to reflect the latest market developments.