1What is the size of the film formers in cosmetics market?
The global film formers in cosmetics market was valued at approximately USD 1.1 billion in 2023 and is projected to reach USD 1.8 billion by 2033, growing at a 5.7% CAGR from 2024 to 2033.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Film Formers in Cosmetics Market
 by Polymer Type (Acrylic, Polyurethane, Vinyl, Cellulosic, Silicone), by Application (Color Cosmetics, Skincare, Haircare, Sun Care), by Form (Liquid Dispersions, Powder, Emulsion), by Function (Primer, Binder, Adhesive, Long-Wear and Transfer Resistance), by Sales Channel (Direct to Brand and Formulators, Distributors), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Asia Pacific (China, India, South Korea, Japan), by South America (Brazil), by Middle East & Africa Forecast 2026-2034
Research Associate


 Related Reports


Analyst at Providence Strategic Partners at Petaling Jaya
I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

Internationalization Director
Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

Head of Product Management and Marketing
We are using your report, and it gave us valuable information."

Regional Director, Marketing and Business Development
We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

VP of Sales
Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.
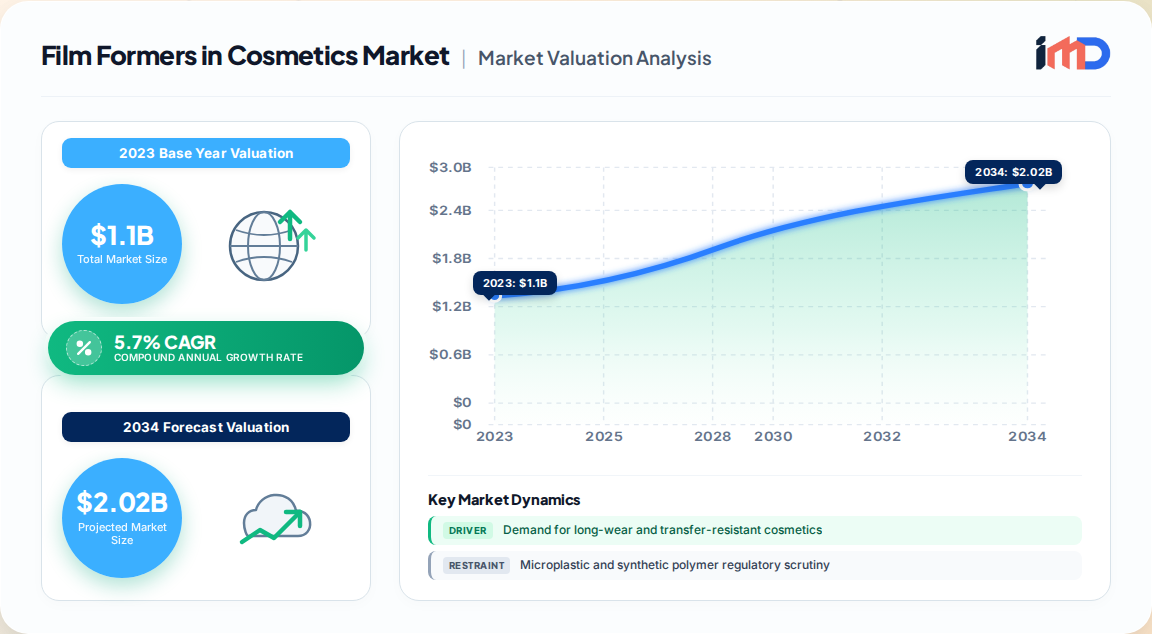
The global film formers in cosmetics market was valued at approximately USD 1.1 billion in 2023 and is projected to reach USD 1.8 billion by 2033, expanding at a 5.7% CAGR across the 2024–2033 forecast horizon. This growth trajectory reflects a structural shift in beauty formulation: film formers have migrated from auxiliary rheology modifiers to core performance ingredients that literally define the consumer claim.
Film formers are specialized polymers that create a cohesive, flexible layer on skin, hair, or nails. They deliver adherence, wear resistance, water resistance, transfer control, and controlled release of actives. Their commercial value is now measured less by volume and more by the claims they enable.
Our proprietary bottom-up modeling, triangulated against color cosmetics retail benchmarks exceeding USD 85 billion globally, indicates that film former intensity per finished formula is rising faster than unit volume — a classic value-over-volume signature that favors specialty suppliers.
Demand expansion is anchored in four measurable commercial forces.
| Driver | Primary Mechanism | Demand Impact |
|---|---|---|
| Wear-claim testing | Rub-off and transfer validation shortlists high-integrity polymers | High |
| SPF and hybrid skincare | Water resistance and filter distribution | High |
| Hair styling hold | Humidity resistance, low residue | Moderate |
| Clean-beauty claims | Bio-based and biodegradable architectures | Emerging |
Three constraints temper the growth curve and shape competitive behavior.
The commercial response is visible in accelerated reformulation toward water-based dispersions, bio-based alternatives, and hybrid systems that preserve performance while improving regulatory positioning. Brands are increasingly willing to pay a premium for polymers that carry both a claim file and a sustainability file.
Polymer chemistry, application, form, and function each reveal a distinct value concentration.
| Segment Dimension | Leading Position | Commercial Significance |
|---|---|---|
| Polymer type | Acrylic polymers | Broad compatibility and film integrity |
| Application | Color cosmetics | Pigment binding, transfer control |
| Form | Liquid dispersions | Faster screening, lower handling complexity |
| Function | Long-wear and transfer resistance | Claim differentiation |
| Sales channel | Direct to brand and formulators | Technical service and trial-led specification |
A notable structural feature is the dominance of direct-to-brand and formulator channels, reflecting the consultative nature of ingredient selection. Application labs, trial batches, and claim validation create switching costs that favor incumbents with strong technical service footprints.
North America and Europe hold mature, high-specification demand bases supported by established cosmetics industries and disciplined compliance frameworks. Asia-Pacific is the fastest-growing region, powered by beauty manufacturing concentration, digital retail expansion, and rising domestic brand activity.
| Region | Market Character | Growth Profile |
|---|---|---|
| North America | Mature, specification-led | Moderate, premium-weighted |
| Europe | Compliance-driven, premium | Steady |
| Asia-Pacific | Manufacturing hub, fast-evolving | Fastest |
| South America | Emerging, price-sensitive | Improving |
| Middle East & Africa | Nascent, import-dependent | Opportunistic |
The supplier base spans diversified specialty chemical majors and focused ingredient specialists. Competition centers on polymer innovation, formulation expertise, application laboratory capability, and sustainability positioning.
Strategic differentiation is shifting toward three battlegrounds: documentation readiness for synthetic polymer review, bio-based performance parity, and sensory optimization under long-wear constraints. Suppliers that pair reliable film performance with responsive technical service and claim-validation evidence are positioned to capture specification slots ahead of competitors.
Film formers sit mid-chain between monomer and specialty polymer producers and finished-goods formulators.
Procurement behavior is increasingly dual-tracked: brands qualify a primary polymer for performance and a secondary bio-based or water-based option for regulatory resilience. This dual-sourcing strategy creates white-space opportunities for suppliers offering documented bio-based alternatives with comparable wear performance.
The market is on track to add roughly USD 0.7 billion in absolute value between 2023 and 2033. Three white spaces merit attention:
Suppliers that convert these white spaces into documented, claim-ready product platforms will define the next phase of competitive advantage in the film formers in cosmetics market.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2023 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.7% from 2020-2034 |
| Segmentation |
|
By Form
By Function
By Sales Channel
| By Geography |
|
The global film formers in cosmetics market was valued at approximately USD 1.1 billion in 2023 and is projected to reach USD 1.8 billion by 2033, growing at a 5.7% CAGR from 2024 to 2033.
North America holds the leading share, supported by a mature cosmetics industry and high consumer preference for long-lasting, water-resistant products. Asia-Pacific is the fastest-growing region, with China and India expanding near 8% annually.
Leading suppliers include Dow, Ashland, BASF, Evonik, Momentive, Wacker Chemie, Lubrizol, Nouryon, Seppic, Croda, Grant Industries, and Kobo Products, competing on polymer innovation and technical service.
The market is expected to register a 5.7% CAGR between 2024 and 2033, driven by long-wear cosmetic demand, sun care formulation intensity, and documentation-led ingredient selection.
Key growth factors include rising demand for transfer-resistant and long-wear makeup, increasing use of film formers in sunscreen and hybrid skincare, and reformulation toward bio-based and water-based polymer systems.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D Director | 34% |
| Formulation Chemist | 27% |
| Procurement Manager | 22% |
| Technical Service Lead | 17% |
| Company Type | Representation (%) |
|---|---|
| Specialty Polymer Manufacturers | 32% |
| Cosmetic Ingredient Distributors | 24% |
| Contract Manufacturers | 19% |
| Brand-Owned Formulation Labs | 15% |
| Independent Formulators | 10% |