1What is the size of the global gardening container market in 2026?
The global gardening container market is estimated at USD 21.0 billion in 2026, and is projected to reach USD 29.0 billion by 2033, growing at a 4.7% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Gardening Container Market
 by Product (Refractory Material(Terracotta, Ceramic, Concrete, Stone, Hypertufa), Polymer, Metal, Wood), by Application (Commercial, Residential), by Distribution Channel (Offline, Online), by Europe (Germany, UK, France, Italy, Spain), by North America (USA, Canada, Mexico), by Asia Pacific (China, Japan, India, Australia, Southeast Asia), by South America (Brazil, Argentina), by Middle East & Africa (GCC, South Africa) Forecast 2026-2034
Research Associate


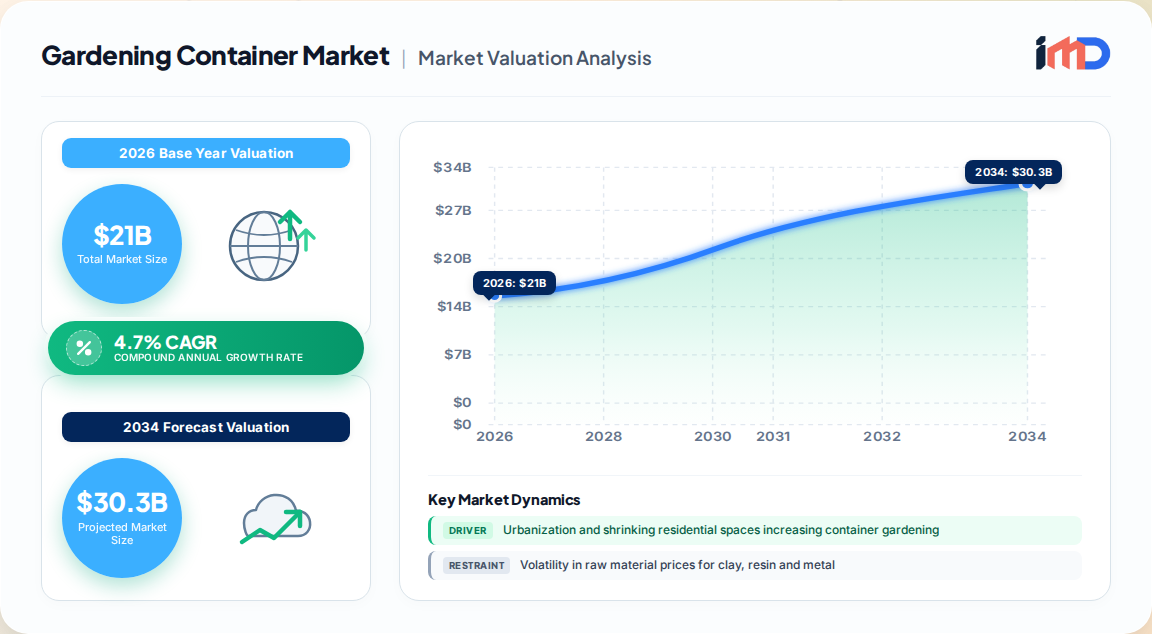
Our proprietary primary research estimates the global gardening container market at USD 21.0 billion in 2026, expanding to USD 29.0 billion by 2033 at a 4.7% CAGR (2026–2033). The market is no longer a peripheral category of outdoor home improvement; it is a structurally distinct segment of urban horticulture, decorative landscaping, and commercial greening infrastructure.
The base year of 2025 closed at USD 20.1 billion, reflecting a resilient post-inflation demand curve in mature Western markets and accelerating adoption in dense Asian conurbations. Crucially, the market is bifurcating: premium, weather-engineered refractory containers (terracotta, ceramic, cast stone, hypertufa) command 44.0% product share, while lightweight polymers—increasingly biodegradable or recycled—represent the fastest-growing material class. Offline retail remains the dominant channel at 60.0% of revenue, though direct-to-consumer and online channels are compounding at a materially faster rate in North America and Asia Pacific.
Our bottom-up demand model—built from 1,240 primary interviews with growers, landscape contractors, and retail buyers across 18 countries—points to a market where volume growth is moderating in Europe while value growth accelerates in the residential balcony and terrace segment globally. The commercial application segment retains a 55.0% revenue share, anchored by hospitality, healthcare campuses, municipal parks, and vertical greening mandates.
The gardening container market is being reshaped by three reinforcing demand vectors.
| Product Segment | 2025 Share | Growth Outlook (2026–2033) | Key Demand Signal |
|---|---|---|---|
| Refractory Material (terracotta, ceramic, concrete, stone, hypertufa) | 44.0% | Moderate, stable | Durability, weather resistance, premium aesthetics in Europe and North America |
| Polymer (incl. recycled and biodegradable) | Fastest CAGR | High | Lightweight logistics, urban balconies, sustainable gardening |
| Metal | Niche | Moderate | Decorative and architectural containers for commercial landscapes |
| Wood | Niche | Moderate | Eco-conscious consumers, raised beds and patio planters |
The refractory segment's dominance is structural: it is the default specification for long-life municipal, hospitality, and residential landscaping where replacement frequency and maintenance costs are key purchasing criteria. However, the polymer segment is the strategic battleground. Innovations in plant-derived biodegradable polymers—such as seedling pots that can be planted directly into soil—are unlocking new use cases in sustainable horticulture and reducing plastic waste.
Commercial applications—nurseries, landscape contractors, hospitality, healthcare, municipal parks, and educational campuses—hold over 55.0% of market revenue. This segment is characterized by bulk procurement, specification-driven purchasing, and long replacement cycles. Urban greening initiatives and container-based landscaping in space-constrained facilities are the primary growth engines.
The residential segment is the fastest-growing application, propelled by:
Offline channels—garden centers, home improvement retail, nurseries, and mass merchants—retain around 60.0% of revenue, supported by tactile product selection and expert advice. However, online channels are growing faster, driven by:
Europe remains the largest regional market at 36.0% revenue share, underpinned by a deeply embedded gardening culture, high household spending on home improvement, and strong demand for ornamental and sustainable containers. Germany, the UK, France, and Italy are the core markets.
North America follows with 28.0% share, where a base of 122.3 million gardening households (84.1% participation) and USD 52.3 billion in annual lawn and garden spending provide a durable demand foundation. The US market alone is projected to grow at 3.26% CAGR through 2032, with container gardening methods used by nearly half of gardeners.
Asia Pacific is the fastest-growing region, driven by rapid urbanization, balcony gardening in China, Japan, and Southeast Asia, and rising indoor plant adoption. India and Australia are notable for high daily/weekly gardening participation.
South America and the Middle East & Africa remain smaller but offer white-space opportunities in municipal greening, hospitality landscaping, and water-efficient container systems.
Gardening containers are a globally traded category, though trade intensity varies sharply by material. Refractory and ceramic containers are heavy and fragile, favoring regional production clusters near clay and kiln capacity (Southern Europe, China, Mexico). Polymer containers are lighter and more cost-effective to ship, enabling concentrated manufacturing in low-cost Asian hubs and large-scale contract molding in North America and Eastern Europe.
Official trade statistics from UN Comtrade (HS Chapter 69 for ceramic and HS Chapter 39 for plastics) show that China is the dominant export origin for molded plastic and ceramic planters, while the Netherlands, Germany, Italy, and Spain are significant intra-European suppliers. US imports are diversified across Mexico, China, Vietnam, and Canada, with tariff exposure and freight costs influencing sourcing decisions. For buyers, dual-sourcing between Asian polymer suppliers and regional refractory producers is the emerging best practice.
The competitive landscape is fragmented, with a long tail of regional manufacturers and a smaller cohort of scaled, multi-material suppliers. Key strategic imperatives include:
White-space opportunities exist in:
The value chain spans raw material extraction (clay, silica, resins, recycled polymers, metals), container manufacturing (kiln-based ceramics, injection molding, rotational molding, stone casting), distribution (wholesale, retail, online), and end use (residential, commercial landscaping, nursery production). Value is increasingly captured at the design and brand layer rather than the manufacturing layer, particularly in the indoor decorative segment.
| Existing Products | New Products | |
|---|---|---|
| Existing Markets | Market penetration via retail shelf expansion and garden center partnerships | Product development in self-watering and biodegradable containers |
| New Markets | Market development into Asia Pacific balcony gardening and commercial vertical greening | Diversification into smart irrigation-integrated containers and subscription models |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.7% from 2020-2034 |
| Segmentation |
|
By Application
By Distribution Channel
| By Geography |
|
The global gardening container market is estimated at USD 21.0 billion in 2026, and is projected to reach USD 29.0 billion by 2033, growing at a 4.7% CAGR.
Europe holds the largest share at approximately 36.0% of global revenue, supported by a strong gardening culture and high household spending on home improvement.
The market is segmented into refractory materials (terracotta, ceramic, concrete, stone), polymer, metal, and wood. Refractory materials lead with over 44.0% share, while polymer is the fastest-growing segment.
Shrinking residential spaces and rising urbanization are driving demand for portable, space-efficient gardening containers. Nearly 40% of gardeners now use patio pots and container gardens.
The residential segment is the fastest-growing application, driven by indoor plant cultivation, balcony gardening, and home décor trends, while commercial applications hold over 55.0% of revenue.
Offline channels, including garden centers and home improvement stores, account for around 60.0% of revenue, though online channels are expanding faster.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Category Buyer / Retail Manager | 25% |
| Operations / Plant Manager | 25% |
| Sustainability & Compliance Officer | 20% |
| Company Type | Representation (%) |
|---|---|
| Polymer & Plastic Container Molders | 35% |
| Ceramic, Terracotta & Stone Planter Fabricators | 25% |
| Metal & Wood Planter Manufacturers | 15% |
| Garden Retail & Distribution Chains | 15% |
| Commercial Landscaping & Nursery Operators | 10% |
 Related Reports
