1What is the China paper packaging market size in 2026?
Our proprietary model values the China paper packaging market at USD 96.13 billion in 2026, rising to USD 121.31 billion by 2031 at a 4.76% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 China Paper Packaging Industry
 by Product Type (Folding Cartons, Corrugated Boxes, Paper Bags and Sacks, Liquid Packaging Cartons, Others), by End-User Industry (Food, Beverage, Healthcare and Pharmaceuticals, Personal Care and Cosmetics, Consumer Goods, E-commerce and Retail, Industrial Packaging, Others), by Material Type (Virgin Fibre-Based, Recycled Fibre-Based), by Packaging Level (Primary Packaging, Secondary Packaging, Tertiary Packaging), by East China (Zhejiang, Jiangsu, Shanghai), by Central China (Hubei, Hunan, Henan), by North China (Hebei, Shandong, Beijing), by South China (Guangdong, Fujian), by Southwest China (Sichuan, Yunnan), by Northwest China (Shaanxi, Gansu) Forecast 2026-2034
Research Associate


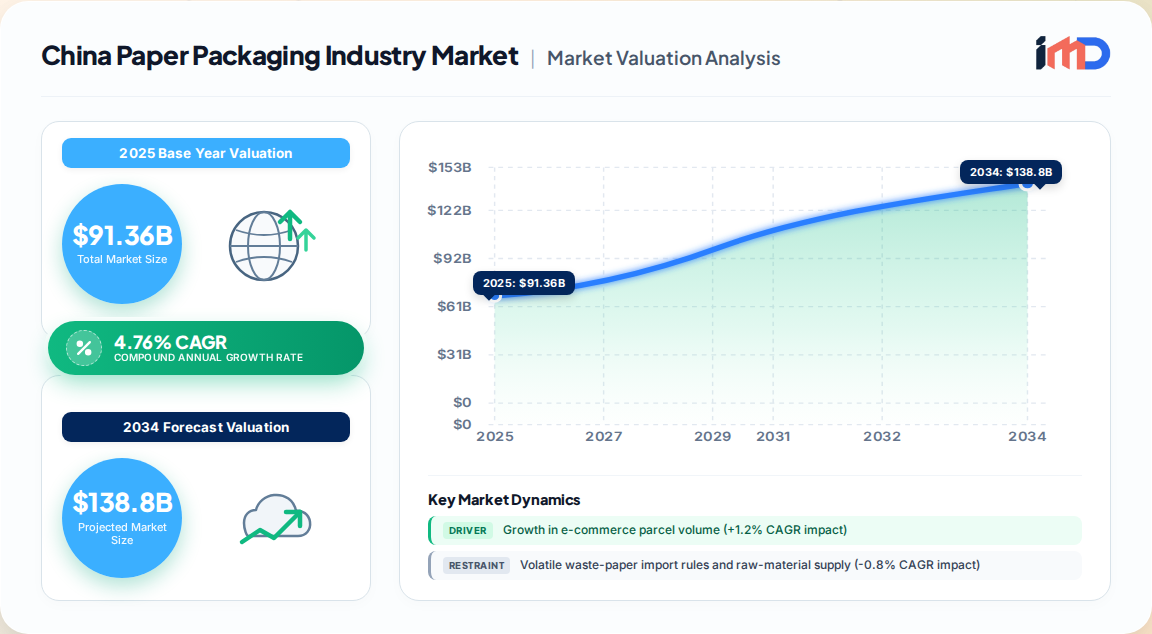
China's paper packaging industry is entering a phase of structural realignment. Our proprietary market model values the sector at USD 91.36 billion in 2025, rising to USD 96.13 billion in 2026 and projected to reach USD 121.31 billion by 2031, reflecting a steady 4.76% CAGR. This growth is not merely a function of volume expansion; it is being reshaped by regulatory mandates, e-commerce logistics sophistication, and a decisive shift in material sourcing.
Three forces dominate the narrative. First, the Green Packaging Law and provincial Extended Producer Responsibility (EPR) fees are creating a measurable cost advantage for fiber-based formats over plastics. Second, parcel volume surpassed 135 billion units in 2025, forcing corrugated suppliers to innovate in lightweighting and right-sizing. Third, raw-material strategy is being rewritten as waste-paper import quotas tightened in October 2025, accelerating capital flows into domestic recovered-fiber sorting and bamboo-pulp capacity.
Our bottom-up demand model, triangulated with trade-flow data from UN Comtrade and industry production indices, yields the following segment breakdown.
| Segment Dimension | Leading Category | 2025 Share | Fastest-Growing Category | CAGR (2026–2031) |
|---|---|---|---|---|
| Product Type | Corrugated Boxes | 43.23% | Liquid Packaging Cartons | 5.71% |
| End-User Industry | Food | 33.98% | Healthcare & Pharmaceuticals | 6.04% |
| Material Type | Recycled Fiber | 62.12% | Virgin Fiber | 5.09% |
| Packaging Level | Secondary Packaging | 47.12% | Primary Packaging | 5.32% |
Our primary interviews with packaging converters, brand owners, and logistics operators reveal five material drivers. The table below quantifies their estimated impact on the forecast CAGR.
| Driver | Estimated CAGR Impact | Geographic Relevance | Timeline |
|---|---|---|---|
| Growth in E-commerce Parcel Volume | +1.2% | National; Yangtze River Delta, Pearl River Delta | Medium term (2–4 years) |
| Expansion of Food-service & Delivery Ecosystem | +0.9% | National; Tier-1 and Tier-2 cities | Short term (≤2 years) |
| Government Plastic-reduction Mandates | +1.0% | National; provincial enforcement | Long term (≥4 years) |
| Advanced Digital Printing & Smart Packaging | +0.6% | Coastal hubs (Guangdong, Zhejiang, Jiangsu) | Medium term (2–4 years) |
| Cross-border E-commerce Consolidation | +0.7% | Export gateway cities (Shenzhen, Shanghai, Ningbo) | Medium term (2–4 years) |
The industry faces non-trivial headwinds that temper the growth trajectory without derailing it.
| Restraint | Estimated CAGR Impact | Geographic Relevance | Timeline |
|---|---|---|---|
| Volatile Waste-paper Import Rules & Raw-material Supply | -0.8% | Coastal provinces reliant on imported recovered paper | Short term (≤2 years) |
| Competition from Recyclable Mono-material Plastics | -0.5% | National; flexible-packaging applications | Medium term (2–4 years) |
| Escalating Energy Costs Amid Decarbonization | -0.4% | Heavy-industry provinces (Hebei, Shandong, Shanxi) | Long term (≥4 years) |
| Pulp Price Volatility | -0.3% | National | Short term (≤2 years) |
The China paper packaging market is low-concentration, with no single player commanding dominant share. Our competitive intelligence identifies a mix of domestic integrated mills and international converters.
Leading domestic players include Nine Dragons Paper, Lee & Man Paper, Shanying International, and Sun Paper, which benefit from vertical integration into pulp and recovered-fiber sourcing. International participants such as International Paper, WestRock, Smurfit Kappa, Mondi, DS Smith, Stora Enso, Oji Holdings, Nippon Paper Industries, and Rengo are active in high-value segments including liquid packaging, pharmaceutical cartons, and premium corrugated.
Recent strategic developments observed through our primary channel checks:
China's paper packaging demand is geographically concentrated but gradually diversifying.
| Region | 2025 Share | Key Characteristics |
|---|---|---|
| East China | 38% | Manufacturing heartland (Zhejiang, Jiangsu, Shanghai); digital printing hubs; export gateway |
| Central China | 18% | Rising e-commerce fulfillment centers; lower energy costs |
| North China | 16% | Heavy-industry base; energy-cost exposure; policy-driven plastic substitution |
| South China | 15% | Pearl River Delta export cluster; food-service packaging innovation |
| Southwest China | 8% | Emerging logistics corridors; bamboo-pulp capacity development |
| Northwest China | 5% | Early-stage infrastructure; lower per-capita packaging consumption |
The paper packaging value chain in China is undergoing vertical integration and digitalization.
| Value Chain Stage | Key Activities | Margin Pressure | Strategic Shift |
|---|---|---|---|
| Raw Material Sourcing | Recovered fiber sorting, virgin pulp, bamboo pulp | High (import quota volatility) | Investment in domestic sorting lines; bamboo-pulp diversification |
| Paper & Board Production | Containerboard, boxboard, liquid packaging board | Medium (energy cost exposure) | Renewable PPAs; efficiency upgrades |
| Conversion & Printing | Corrugated box assembly, folding carton printing, digital printing | Medium (labor, ink costs) | Digital press adoption (HP Indigo installations up 34% in 2025) |
| Brand Owner & Retailer | Packaging specification, compliance | Low (brand power) | Shift to recyclable formats; smart-label integration |
| End Consumer & Recovery | Consumption, recycling, disposal | N/A | Blockchain traceability; EPR fee structures |
China is a net importer of virgin pulp and a net exporter of finished paper packaging, though the trade balance is shifting.
Our analysis identifies three high-conviction strategic opportunities for participants in the China paper packaging market.
Risk factors to monitor include the trajectory of waste-paper import policy, energy price volatility, and the speed of mono-material plastic innovation. However, the regulatory tailwind behind fiber-based packaging is strong and durable, positioning the China paper packaging market for sustained value creation through 2031.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.76% from 2020-2034 |
| Segmentation |
|
By End-User Industry
By Material Type
By Packaging Level
| By Geography |
|
Our proprietary model values the China paper packaging market at USD 96.13 billion in 2026, rising to USD 121.31 billion by 2031 at a 4.76% CAGR.
Corrugated boxes led with 43.23% of market share in 2025, driven by e-commerce parcel volume exceeding 135 billion units.
Healthcare and pharmaceuticals recorded the highest projected annual growth at 6.04% through 2031, fueled by serialization and tamper-evident requirements.
The Green Packaging Law requires 75% of express packaging to be recyclable or reusable by end-2027, and pilot EPR fees of CNY 0.15–0.30 per kilogram on non-recyclable packaging are accelerating the shift to paper.
Key players include Nine Dragons Paper, Lee & Man Paper, Shanying International, Sun Paper, International Paper, WestRock, Smurfit Kappa, and Rengo.
Tightened import quotas since October 2025 have reduced recovered-paper imports, prompting mills to invest in domestic sorting infrastructure and bamboo-pulp capacity, with a short-term negative impact of -0.8% on CAGR.
East China accounts for approximately 38% of national demand, driven by its concentration of converters, brand owners, and logistics infrastructure.
Key trends include the shift to recycled fiber (62.12% share), digital printing adoption (HP Indigo installations up 34% in 2025), smart packaging integration via NFC, and lightweight corrugated innovation for e-commerce.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Packaging Development Manager | 25% |
| Supply Chain Director | 25% |
| Sustainability Compliance Officer | 20% |
| Company Type | Representation (%) |
|---|---|
| Recovered-fiber sorting operators | 20% |
| Containerboard and boxboard mills | 25% |
| Corrugated box converters | 25% |
| Folding carton printers | 15% |
| Brand-owner packaging procurement teams | 15% |
 Related Reports
