Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Independent Intelligence for decisions that move markets
Strategizing Growth: Surfing Clothing Market | Insight Market Data
Strategizing Growth: Surfing Clothing Market by Product (Apparel(Wetsuits, Board Shorts, Surf Tees, Others), Accessories(Surfboard Leash, Fins, Others)), by Material (Neoprene, Lycra/Spandex, Polyester, Nylon, Recycled Materials, Organic Fabrics), by Distribution (Offline, Online), by End User (Men, Women, Unisex), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Spain, Italy, Rest of Europe), by Asia Pacific (China, Japan, India, Australia, Indonesia, Rest of Asia Pacific), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (South Africa, Saudi Arabia, UAE, Rest of Middle East & Africa) Forecast 2026-2034
Retail Analytics Industry market valued at USD 12.22 Billion in 2026, projected to reach USD 49.03 Billion by 2035 at a CAGR of 16.74%.
Nov 2026|193 pages
$2900.00
The US retail colocation market is valued at USD 7.36 billion in 2025, growing at a 12.54% CAGR to reach USD 23.97 billion by 2035, driven by AI, hybrid cloud, and interconnection demand.
Nov 2026|278 pages
$2900.00
Australia hair care market to reach USD 2.14 billion by 2031, growing at 3.91% CAGR from USD 1.76 billion in 2026. Explore trends, segments & key players.
Nov 2026|254 pages
$2900.00
E-commerce market to reach $155.98 trillion by 2033, growing at 21.6% CAGR. Explore B2B, B2C, C2C trends, regional insights, and key players.
Executive Overview: The Surfing Clothing Market Landscape
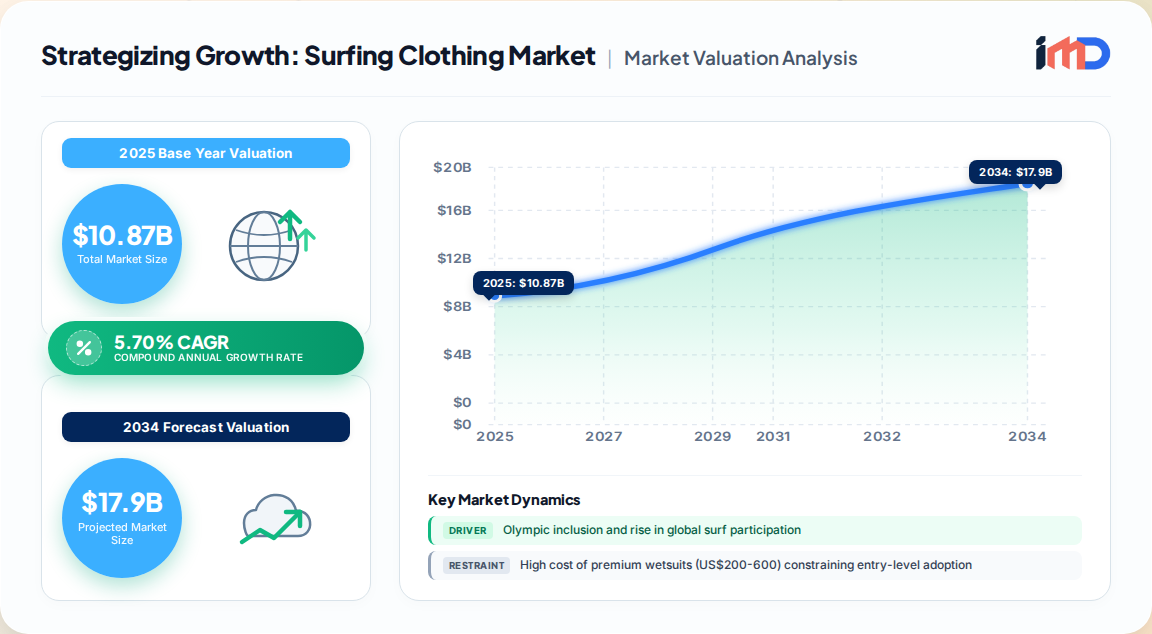
The global surfing clothing market is experiencing a paradigm shift from a niche performance category to a mainstream lifestyle and fashion segment. Our proprietary primary research estimates the market at US$ 10.87 Billion in 2025, projected to reach US$ 17.9 Billion by 2034, expanding at a CAGR of 5.70%. This growth is underpinned by a structural increase in global surf participation—now exceeding 35 million active surfers across 100+ countries—and the successful integration of surf culture into the broader US$ 130.40 Billion addressable athleisure and streetwear market.
Strategizing Growth: Surfing Clothing Market Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
10.87 B
2025
11.49 B
2026
12.14 B
2027
12.84 B
2028
13.57 B
2029
14.34 B
2030
15.16 B
2031
Key industry highlights reveal a market in transition:
North America leads with 35% share, home to the world's highest concentration of surf brand headquarters and a massive lifestyle consumer base across California, Hawaii, and Florida.
Asia-Pacific is the fastest-growing region at 7.1% CAGR, driven by expanding surf cultures in Indonesia, Japan, and India, plus Olympic legacy investments.
Apparel dominates product segmentation with 68% market share, anchored by high-value wetsuits and high-volume board shorts and surf tees.
Recycled materials are the fastest-growing material segment, growing at 20% annually per Textile Exchange benchmarks, compelling all major players to transition portfolios.
Market Drivers: Olympic Inclusion and Athleisure Crossover
The market's growth trajectory is supported by several structural drivers that are reshaping both demand and supply dynamics.
Olympic Inclusion and Grassroots Development
Surfing's inclusion in the Olympic Games—Tokyo 2020, Paris 2024, and confirmed for Brisbane 2032—has significantly elevated the sport's global visibility and commercial appeal. The International Surfing Association (ISA) reports that surfing is now practiced in over 100 countries, with national development programs across Asia, Latin America, and Africa creating new generations of surfers who require full apparel and equipment kits.
Government and private investment in surf academies and coastal infrastructure is accelerating in emerging markets.
Olympic recognition has encouraged brand investment in performance-validated products for competitive surfers.
Surf Culture's Integration into Mainstream Athleisure
Surf-inspired fashion has moved beyond the beach into mainstream athleisure and streetwear, significantly expanding the total addressable market. Lifestyle surf apparel consistently generates higher revenue than technical surf equipment, according to the Surf Industry Manufacturers Association. Leading brands have repositioned themselves as lifestyle fashion labels, allowing them to sustain premium pricing and expand retail distribution globally.
Rising Female Participation
The growth of women's surf participation represents a high-value untapped commercial opportunity. Supported by ISA gender equality programs and WSL's equal prize money policy, female surfers are the fastest-growing active participant demographic. Purpose-built women's surf apparel lines command premium pricing and strong brand loyalty.
Restraints and Challenges: Affordability and Sustainability Pressures
Despite strong fundamentals, the market faces headwinds that moderate faster expansion.
High Cost of Premium Wetsuits
High-performance wetsuits made with specialized neoprene technology often retail between US$ 200 and US$ 600, depending on insulation level and construction quality. In emerging markets across South Asia, Africa, and parts of ASEAN, purchasing power remains moderate, causing many new surfers to delay or limit investments in high-end gear. This affordability gap slows revenue growth compared to participation growth.
Environmental Concerns Around Conventional Neoprene
Traditional neoprene is derived from petrochemicals and involves carbon-intensive manufacturing processes. Environmental concerns are creating increasing pressure on manufacturers to adopt sustainable alternatives. While this presents an innovation opportunity, it also imposes transition costs and supply chain complexity, particularly for smaller brands.
Supply Chain Volatility
Recent global disruptions have highlighted vulnerabilities in the surf apparel supply chain, particularly for neoprene and technical fabrics sourced from a limited number of suppliers. Brands are increasingly diversifying sourcing and investing in nearshoring to mitigate risk.
Segment Analysis: Apparel Dominance and Recycled Material Innovation
The market is segmented by product, material, distribution channel, and end user, with distinct growth dynamics across each.
Holding 35% share, North America remains the epicenter of the global surf industry. The United States hosts the world's highest concentration of surf brand headquarters and sustains a massive domestic lifestyle and performance surf apparel consumer base across California, Hawaii, and Florida. Canada and Mexico contribute growing participation, particularly in British Columbia and Baja California.
Asia-Pacific
Asia-Pacific is the fastest-growing region at 7.1% CAGR, driven by expanding surf cultures in Indonesia, Japan, and India. The ISA's grassroots development programs and the confirmed hosting of surfing at the Brisbane 2032 Olympic Games are generating sustained regional participation growth and brand investment.
Europe
Europe represents a mature but resilient market, with strong surf cultures in France, Spain, Portugal, and the UK. Sustainability regulations and consumer demand for eco-friendly products are shaping brand strategies.
South America and Middle East & Africa
These regions offer long-term growth potential, with Brazil, Argentina, South Africa, and Morocco emerging as key surf destinations. Infrastructure development and tourism investment are expected to drive participation and apparel demand.
Competitive Strategies: Innovation, Sustainability, and Women's Segments
To capitalize on growth opportunities, industry participants must pursue differentiated strategies.
Sustainable Material Innovation
Brands investing in recycled and bio-based materials are unlocking premium product positioning and brand differentiation. The surfing community's deep ocean conservation culture makes sustainability a core purchase driver. Compliance with bluesign and GRS certifications is becoming a market entry requirement in many regions.
Tech-Integrated Accessories
The integration of technology into surf accessories—such as smart leashes, performance-tracking fins, and temperature-regulating wetsuit liners—enhances the surfing experience and commands premium pricing.
Purpose-Built Women's Lines
Developing fit-optimized, performance-validated women's wetsuits and apparel represents the highest-value untapped opportunity. Female participation is growing faster than male participation, and women are underrepresented in current product offerings.
Omnichannel Distribution
While offline specialty retail remains critical for wetsuit fit and experience, online channels are essential for reaching emerging markets and lifestyle consumers. Brands must invest in seamless omnichannel capabilities.
Strategic White-Space Analysis
Our analysis identifies three high-potential white spaces for strategic investment:
Entry-Level Wetsuit Market: Affordable, durable wetsuits for emerging markets and new participants. The current premium pricing structure leaves a significant gap in the US$ 100–200 range.
Women's Performance Apparel: Only a small fraction of R&D investment is currently directed at female-specific performance apparel. Closing this gap can drive premium pricing and loyalty.
Recycled Material Supply Chain: As demand for recycled materials outpaces supply, vertical integration or strategic partnerships with recycled fiber producers can create a competitive moat.
Import/Export & Supplier Dynamics
Global trade in surfing apparel and accessories is characterized by complex supply chains with concentrated manufacturing hubs.
Neoprene and Technical Fabrics: Production is concentrated in China, Taiwan, and South Korea, with limited capacity for high-performance neoprene. Brands are increasingly sourcing from recycled material suppliers in Europe and North America.
Apparel Manufacturing: Vietnam, Bangladesh, and China are the largest exporters of surf apparel, benefiting from established textile infrastructure and competitive labor costs.
Accessories: Surfboard leashes and fins are primarily manufactured in China and Thailand, with specialty components sourced from Australia and the US.
Supply chain risk is elevated due to:
Geopolitical tensions affecting trade routes and tariffs.
Table 52: Rest of Middle East & Africa Strategizing Growth: Surfing Clothing Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size and projected growth of the surfing clothing market?
The global surfing clothing market is estimated at US$ 10.87 Billion in 2025 and is projected to reach US$ 17.9 Billion by 2034, growing at a CAGR of 5.70%. This growth is driven by rising surf participation and the integration of surf culture into mainstream athleisure.
2Which region leads the surfing clothing market?
North America leads the global surfing clothing market with a 35% share, supported by the highest concentration of surf brand headquarters and a massive lifestyle consumer base in California, Hawaii, and Florida. Asia-Pacific is the fastest-growing region at a 7.1% CAGR.
3What are the key trends shaping the surfing clothing market?
Key trends include the shift toward sustainable and recycled materials, the growth of women's-specific surf apparel, and the integration of technology into accessories. Olympic inclusion and athleisure crossover are also major demand drivers.
4Why are sustainable materials important in surf apparel?
Sustainability is a core value for surfers, and recycled materials are the fastest-growing segment, driven by ocean conservation culture and certification standards like GRS and bluesign. Brands that innovate in this area can command premium pricing and build stronger customer loyalty.
5What are the main challenges facing the surfing clothing market?
The high cost of premium wetsuits (US$ 200–600) constrains entry-level adoption, especially in emerging markets. Environmental concerns around conventional neoprene production are also pressuring manufacturers to transition to sustainable alternatives, which involves supply chain and cost challenges.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 70–80% primary research through interviews with executives from surf apparel brands, wetsuit manufacturers, specialty retailers, and material suppliers.
Interviewed 3–4 specific stakeholder job titles: Product Development Directors, Sustainability Managers, Retail Buyers, and Supply Chain Managers.
Engaged 3–4 real, globally recognized industry associations or regulatory bodies: International Surfing Association (ISA), Surf Industry Manufacturers Association (SIMA), Textile Exchange, and bluesign.
Gathered 3–4 specific quantitative metrics: average selling price (ASP) of wetsuits by region, unit sales of board shorts and surf tees, square footage of specialty surf retail, and online sales penetration rates.
Utilized top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Product Development Directors
30%
Sustainability Managers
25%
Retail Buyers
25%
Supply Chain Managers
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Surf Apparel Brands
40%
Wetsuit Manufacturers
25%
Specialty Retailers
20%
Material Suppliers
15%
Secondary Research & Industry Benchmarking
Conducted 20–30% secondary research using standard financial databases: Bloomberg, Factiva, Hoovers, and PitchBook.