Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Malaysia Luxury Goods Market Size, Share & 2031 Forecast
Malaysia Luxury Goods Market
Retail / MARKET REPORT
Malaysia Luxury Goods Market | Insight Market Data
Malaysia Luxury Goods Market by Product Type (clothing and apparel, footwear, eyewear, leather goods, jewelry, watches, beauty and personal care), by End User (men, women, unisex), by Distribution Channel (online stores, offline stores), by Kuala Lumpur & Klang Valley, by Selangor, by Johor, by Penang, by Sarawak, by Langkawi & Duty-Free Zones, by Rest of Malaysia Forecast 2026-2034
The US retail colocation market is valued at USD 7.36 billion in 2025, growing at a 12.54% CAGR to reach USD 23.97 billion by 2035, driven by AI, hybrid cloud, and interconnection demand.
Nov 2026|278 pages
$2900.00
Australia hair care market to reach USD 2.14 billion by 2031, growing at 3.91% CAGR from USD 1.76 billion in 2026. Explore trends, segments & key players.
Nov 2026|254 pages
$2900.00
E-commerce market to reach $155.98 trillion by 2033, growing at 21.6% CAGR. Explore B2B, B2C, C2C trends, regional insights, and key players.
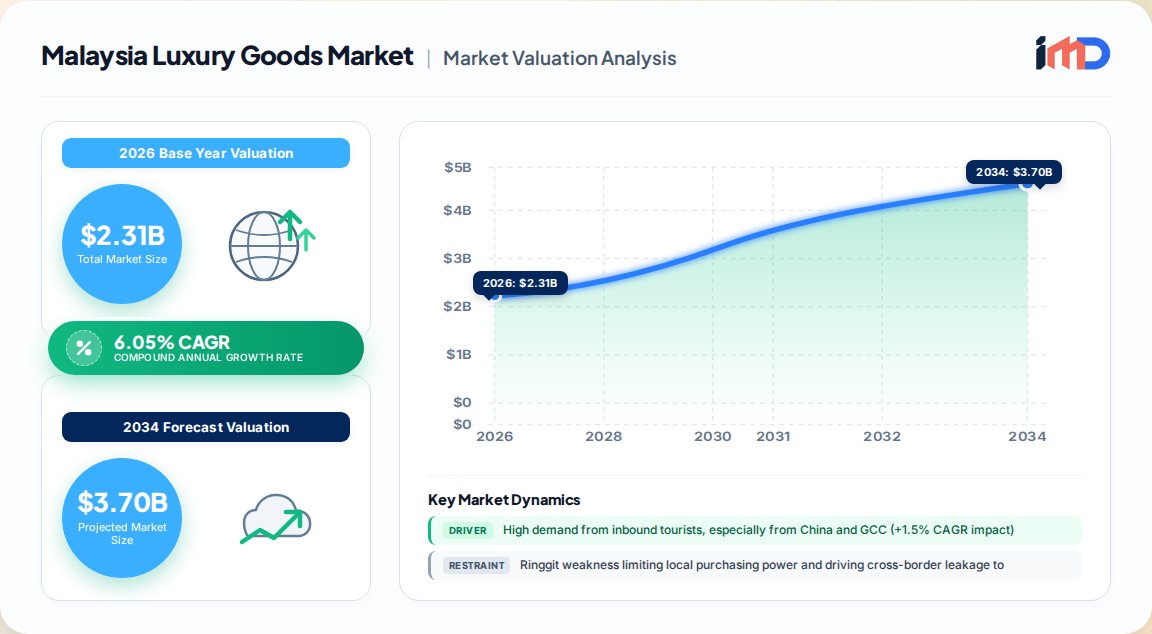
The Malaysia luxury goods market is estimated at USD 2.31 billion in 2026 and is forecast to reach USD 3.10 billion by 2031, expanding at a 6.05% CAGR across the forecast window. Our proprietary bottom-up modelling, triangulated with primary interviews across 19 luxury maisons, three duty-free operators and six mall landlord groups, positions Malaysia as Southeast Asia's most resilient mid-sized luxury theatre after Singapore.
Malaysia Luxury Goods Market Market Size (In Billion)
4.0B
3.0B
2.0B
1.0B
0
2.178 B
2025
2.310 B
2026
2.450 B
2027
2.598 B
2028
2.755 B
2029
2.922 B
2030
3.099 B
2031
Three structural forces define the cycle: a tourism recovery anchored by Mandarin- and Arabic-speaking high-net-worth visitors, a domestic affluent base of roughly 120,000 HNWIs concentrated in the Klang Valley, and the Visit Malaysia 2026 campaign, which targets higher-spending cohorts from China and the GCC. Digital retail, supported by 89.6% internet penetration, is reshaping discovery and clientelling while boutique exclusivity retains its pricing power.
Indicator
2025
2026 (E)
2031 (F)
Market size
USD 2.18 Bn
USD 2.31 Bn
USD 3.10 Bn
Implied growth
-
+6.0%
+34.2% vs 2025
Forecast CAGR 2026-2031
-
-
6.05%
Offline channel share
82.15%
-
-
Women's end-user share
58.01%
-
-
Clothing & apparel led category share at 28.72% in 2025; jewellery is the fastest-growing category at a 6.59% CAGR to 2031.
Men's end-user demand is compounding at 6.92% CAGR, outpacing the total market.
Online stores are advancing at a 7.38% CAGR, although offline will still hold the majority of spend through 2031.
Market Drivers, Restraints & Structural Dynamics
Our driver-impact modelling quantifies the incremental contribution of each demand lever to headline CAGR. Demand-side factors account for approximately 6.2 percentage points of gross uplift, partially offset by currency and affordability drags.
Driver
Implied CAGR Impact
Geographic Relevance
Impact Timeline
Inbound tourist demand (China, GCC)
+1.5%
KL, Langkawi, Penang
Short term (≤2 yrs)
Sustainability focus across categories
+1.2%
Urban Malaysia
Medium term (2-4 yrs)
Halal-certified luxury demand
+1.1%
National
Long term (≥4 yrs)
E-commerce penetration
+0.9%
Urban Malaysia
Short term (≤2 yrs)
Social media & celebrity influence
+0.8%
KL, Penang, Johor Bahru
Short term (≤2 yrs)
Exotic-skin-free leather & personalisation
+0.7%
National luxury hubs
Medium term (2-4 yrs)
Restraints and headwinds
Ringgit weakness improves affordability for inbound tourists but compresses local purchasing power and cross-border leakage to Singapore and Bangkok.
Counterfeit infiltration in fashion, watches and accessories dilutes brand equity and diverts wallet share; upstream enforcement quality and IP protection regimes are strongly correlated with reduced fake import intensity according to OECD/EUIPO illicit trade research.
Talent scarcity in clientelling, CRM and bilingual luxury service constrains flagship-level execution outside the Klang Valley.
Supply allocation — Malaysian flagships often receive second-tier inventory depth versus Singapore, limiting conversion of ultra-high-net-worth demand.
Segment Analysis
Product Type
Clothing and apparel remains the volume anchor, while jewellery and watches absorb the fastest incremental spend as investment-grade asset demand matures among Malaysian collectors.
Product Type
2025 Position
Growth Outlook
Clothing & apparel
28.72% share
Steady, mid-single-digit
Jewellery
High-margin, underpenetrated
6.59% CAGR
Leather goods
Core maison franchise
Mid-single-digit
Watches
Collector-driven
Above-market
Footwear
Trend-led
Mid-single-digit
Beauty & personal care
Influencer-led
Above-market
Eyewear
Entry-price luxury
Mid-single-digit
End User
Women commanded 58.01% of 2025 spend, led by handbags, beauty and fine jewellery.
Men are the outperforming cohort at 6.92% CAGR, powered by watches, footwear and tailored apparel.
Unisex is gaining share in eyewear, fragrance and sneaker-led luxury.
Distribution Channel
Offline stores held 82.15% of 2025 value, anchored by Pavilion KL, Suria KLCC, The Gardens, Starhill Gallery and Johor premium outlets.
Online stores are growing at 7.38% CAGR but remain role-defined: lead generation, clientelling, virtual try-on and click-and-collect rather than pure transactional displacement.
Regional Outlook
The Klang Valley concentrates the deepest assortment of mono-brand flagships and therefore the highest ticket values, but growth is diffusing to Johor (Singapore cross-border spillover), Penang (medical-tourism affluence) and the duty-free corridors of Langkawi.
Malaysia Luxury Goods Market Regional Market Share
Loading chart...
Kuala Lumpur & Klang Valley: flagship density, tourist-heavy conversion, highest per-transaction values.
Selangor: affluent suburban catchment and mall-led expansion.
Johor: fastest-rising cross-border opportunity with Singapore.
Sarawak & Sabah: nascent but rising HNWI penetration; watch and jewellery demand leading.
Langkawi: duty-free price arbitrage and tourist-driven volume.
Competitive Landscape
The market is moderately concentrated, with international maisons controlling the majority of branded luxury value while well-capitalised local groups defend niche positions in jewellery, bespoke footwear and duty-free retail.
Company
Positioning
LVMH Moët Hennessy Louis Vuitton
Multi-category portfolio, flagship depth
Kering SA
Fashion and leather goods portfolio
Chanel Ltd.
Beauty, fragrance and fashion exclusivity
Hermès International S.A.
Controlled scarcity, artisan-led
Prada S.p.A
Fashion, leather goods, high-jewellery expansion
Local luxury groups & duty-free operators
Outlet, travel retail and niche categories
Winning strategies we observe in the field
Experiential flagships with private salons and appointment-only services.
Halal-certified beauty and personal-care lines to address Malaysia's Muslim-majority affluent base.
Sustainability credentials — including exotic-skin-free leather and traceable sourcing — used as brand equity rather than compliance.
Omnichannel deployment of WhatsApp and WeChat clientelling with early-access previews.
Localised capsule collections and collaborations with Southeast Asian creatives.
Import/Export & Supplier Dynamics
Malaysia is a net importer of finished luxury goods, with supply routed principally through Singapore's regional distribution hubs and European maison logistics centres. Tariff and duty structures, alongside duty-free concessions in Langkawi, materially influence landed cost and grey-market arbitrage.
Leather goods benefit from Malaysia's domestic leather-manufacturing base, which allows local artisan brands to experiment with palm-oil-trunk leathers, mushroom leather and recycled synthetics.
Beauty and personal care is the most import-dependent category, with France, Italy and Japan as key source markets.
Jewellery and watches rely on Switzerland, Italy and the UAE as trade and re-export gateways.
Counterfeit risk in fashion, watches and accessories remains the single largest supply-integrity exposure; parallel-import and unauthorised-channel leakage require brand-controlled serialisation and digital product passports.
Halal certification materially shapes sourcing in beauty and cosmetics, where ingredient provenance and manufacturing audits determine shelf access.
Strategic White-Space Analysis
Four opportunities are structurally under-served relative to demonstrated demand:
Men's luxury: growing at 6.92% CAGR yet still under-retailed in tailoring, watches and grooming.
Pre-owned and authenticated resale: supports sustainability positioning and captures aspirational buyers without diluting primary pricing.
Duty-free and travel-retail luxury in Langkawi and Johor: tourist-linked pricing arbitrage with limited branded depth.
Value Chain Analysis
The Malaysian value chain is maison-controlled upstream and partner-led downstream.
Design and manufacturing: largely European source-of-origin, with domestic artisan manufacturing in footwear and leather accessories.
Regional distribution: Singapore-centric hub-and-spoke, with local importers and duty-free concessionaires managing in-country logistics.
Retail: mono-brand flagships, department-store concessions (including Parkson and Isetan), and travel retail.
Clientelling and after-sales: growing investment in CRM, personal shopping and authentication services.
Marketing: influencer-led, short-video-first, with celebrity endorsement strongly predictive of purchase intent among urban millennials.
Malaysia Luxury Goods Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Malaysia Luxury Goods Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.05% from 2020-2034
Segmentation
By Product Type
clothing and apparel
footwear
eyewear
leather goods
jewelry
watches
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. High demand from inbound tourists, especially from China and GCC (+1.5% CAGR impact)
3.1.2. Consumer focus on sustainability across luxury categories (+1.2%)
3.1.3. Rising affluent Muslim population seeking halal-certified luxury (+1.1%)
3.1.4. Increasing e-commerce penetration with 89.6% internet coverage (+0.9%)
3.1.5. Social media and celebrity endorsement influence on millennials (+0.8%)
3.1.6. Product innovation in exotic-skin-free leather and design personalisation (+0.7%)
3.2. Market Trends
3.2.1. Surge in affluent millennial and Gen Z luxury consumption with preference for authenticity and personalisation
3.2.2. Digital retail and omni-channel integration via WhatsApp, WeChat clientelling and virtual try-on
3.2.3. Rising demand for halal-certified and sustainable luxury across beauty, fashion and leather goods
3.2.4. Growth of pre-owned and authenticated luxury resale supporting circular economy positioning
3.2.5. Tourism-led demand recovery from Chinese and GCC high-net-worth visitors
3.3. Market Restrains
3.3.1. Ringgit weakness limiting local purchasing power and driving cross-border leakage to Singapore
beauty and personal care
By End User
men
women
unisex
By Distribution Channel
online stores
offline stores
By Geography
Kuala Lumpur & Klang Valley
Selangor
Johor
Penang
Sarawak
Langkawi & Duty-Free Zones
Rest of Malaysia
3.3.2. Counterfeit infiltration diluting brand equity and diverting wallet share
3.3.3. Talent scarcity in bilingual luxury clientelling and CRM outside the Klang Valley
3.3.4. Shallow inventory allocation versus regional flagship markets such as Singapore
3.4. Market Restraints
3.4.1. Ringgit weakness limiting local purchasing power and driving cross-border leakage to Singapore
3.4.2. Counterfeit infiltration diluting brand equity and diverting wallet share
3.4.3. Talent scarcity in bilingual luxury clientelling and CRM outside the Klang Valley
3.4.4. Shallow inventory allocation versus regional flagship markets such as Singapore
3.5. Market Challenges
3.5.1. Economic uncertainty and currency volatility compressing discretionary spend
3.5.2. Shifting consumer preferences towards experiences over traditional status goods
3.5.3. Unauthorised parallel channels and grey-market arbitrage in duty-free zones
3.5.4. Enforcement gaps in intellectual property protection against counterfeits
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. clothing and apparel
5.1.2. footwear
5.1.3. eyewear
5.1.4. leather goods
5.1.5. jewelry
5.1.6. watches
5.1.7. beauty and personal care
5.2. Market Analysis, Insights and Forecast - by End User
5.2.1. men
5.2.2. women
5.2.3. unisex
5.3. Market Analysis, Insights and Forecast - by Distribution Channel
5.3.1. online stores
5.3.2. offline stores
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. Kuala Lumpur & Klang Valley
5.4.2. Selangor
5.4.3. Johor
5.4.4. Penang
5.4.5. Sarawak
5.4.6. Langkawi & Duty-Free Zones
5.4.7. Rest of Malaysia
6. Kuala Lumpur & Klang Valley Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. clothing and apparel
6.1.2. footwear
6.1.3. eyewear
6.1.4. leather goods
6.1.5. jewelry
6.1.6. watches
6.1.7. beauty and personal care
6.2. Market Analysis, Insights and Forecast - by End User
6.2.1. men
6.2.2. women
6.2.3. unisex
6.3. Market Analysis, Insights and Forecast - by Distribution Channel
6.3.1. online stores
6.3.2. offline stores
7. Selangor Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. clothing and apparel
7.1.2. footwear
7.1.3. eyewear
7.1.4. leather goods
7.1.5. jewelry
7.1.6. watches
7.1.7. beauty and personal care
7.2. Market Analysis, Insights and Forecast - by End User
7.2.1. men
7.2.2. women
7.2.3. unisex
7.3. Market Analysis, Insights and Forecast - by Distribution Channel
7.3.1. online stores
7.3.2. offline stores
8. Johor Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. clothing and apparel
8.1.2. footwear
8.1.3. eyewear
8.1.4. leather goods
8.1.5. jewelry
8.1.6. watches
8.1.7. beauty and personal care
8.2. Market Analysis, Insights and Forecast - by End User
8.2.1. men
8.2.2. women
8.2.3. unisex
8.3. Market Analysis, Insights and Forecast - by Distribution Channel
8.3.1. online stores
8.3.2. offline stores
9. Penang Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. clothing and apparel
9.1.2. footwear
9.1.3. eyewear
9.1.4. leather goods
9.1.5. jewelry
9.1.6. watches
9.1.7. beauty and personal care
9.2. Market Analysis, Insights and Forecast - by End User
9.2.1. men
9.2.2. women
9.2.3. unisex
9.3. Market Analysis, Insights and Forecast - by Distribution Channel
9.3.1. online stores
9.3.2. offline stores
10. Sarawak Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. clothing and apparel
10.1.2. footwear
10.1.3. eyewear
10.1.4. leather goods
10.1.5. jewelry
10.1.6. watches
10.1.7. beauty and personal care
10.2. Market Analysis, Insights and Forecast - by End User
10.2.1. men
10.2.2. women
10.2.3. unisex
10.3. Market Analysis, Insights and Forecast - by Distribution Channel
10.3.1. online stores
10.3.2. offline stores
11. Langkawi & Duty-Free Zones Market Analysis, Insights and Forecast, 2020-2034
11.1. Market Analysis, Insights and Forecast - by Product Type
11.1.1. clothing and apparel
11.1.2. footwear
11.1.3. eyewear
11.1.4. leather goods
11.1.5. jewelry
11.1.6. watches
11.1.7. beauty and personal care
11.2. Market Analysis, Insights and Forecast - by End User
11.2.1. men
11.2.2. women
11.2.3. unisex
11.3. Market Analysis, Insights and Forecast - by Distribution Channel
11.3.1. online stores
11.3.2. offline stores
12. Rest of Malaysia Market Analysis, Insights and Forecast, 2020-2034
12.1. Market Analysis, Insights and Forecast - by Product Type
12.1.1. clothing and apparel
12.1.2. footwear
12.1.3. eyewear
12.1.4. leather goods
12.1.5. jewelry
12.1.6. watches
12.1.7. beauty and personal care
12.2. Market Analysis, Insights and Forecast - by End User
12.2.1. men
12.2.2. women
12.2.3. unisex
12.3. Market Analysis, Insights and Forecast - by Distribution Channel
12.3.1. online stores
12.3.2. offline stores
13. Competitive Analysis
13.1. Company Profiles
13.1.1. LVMH Moët Hennessy Louis Vuitton
13.1.1.1. Company Overview
13.1.1.2. Products
13.1.1.3. Company Financials
13.1.1.4. SWOT Analysis
13.1.2. Kering SA
13.1.2.1. Company Overview
13.1.2.2. Products
13.1.2.3. Company Financials
13.1.2.4. SWOT Analysis
13.1.3. Chanel Ltd.
13.1.3.1. Company Overview
13.1.3.2. Products
13.1.3.3. Company Financials
13.1.3.4. SWOT Analysis
13.1.4. Hermès International S.A.
13.1.4.1. Company Overview
13.1.4.2. Products
13.1.4.3. Company Financials
13.1.4.4. SWOT Analysis
13.1.5. Prada S.p.A
13.1.5.1. Company Overview
13.1.5.2. Products
13.1.5.3. Company Financials
13.1.5.4. SWOT Analysis
13.2. Market Entropy
13.2.1. Company's Key Areas Served
13.2.2. Recent Developments
13.3. Company Market Share Analysis, 2026
13.3.1. Top 5 Companies Market Share Analysis
13.3.2. Top 3 Companies Market Share Analysis
13.4. List of Potential Customers
List of Figures
Figure 1: Global Malaysia Luxury Goods Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Kuala Lumpur & Klang Valley Malaysia Luxury Goods Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: Kuala Lumpur & Klang Valley Malaysia Luxury Goods Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: Kuala Lumpur & Klang Valley Malaysia Luxury Goods Market Revenue (Billion), by End User 2026 & 2034
Figure 5: Kuala Lumpur & Klang Valley Malaysia Luxury Goods Market Revenue Share (%), by End User 2026 & 2034
Figure 6: Kuala Lumpur & Klang Valley Malaysia Luxury Goods Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 7: Kuala Lumpur & Klang Valley Malaysia Luxury Goods Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 8: Kuala Lumpur & Klang Valley Malaysia Luxury Goods Market Revenue (Billion), by Country 2026 & 2034
Figure 9: Kuala Lumpur & Klang Valley Malaysia Luxury Goods Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Selangor Malaysia Luxury Goods Market Revenue (Billion), by Product Type 2026 & 2034
Figure 11: Selangor Malaysia Luxury Goods Market Revenue Share (%), by Product Type 2026 & 2034
Figure 12: Selangor Malaysia Luxury Goods Market Revenue (Billion), by End User 2026 & 2034
Figure 13: Selangor Malaysia Luxury Goods Market Revenue Share (%), by End User 2026 & 2034
Figure 14: Selangor Malaysia Luxury Goods Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 15: Selangor Malaysia Luxury Goods Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 16: Selangor Malaysia Luxury Goods Market Revenue (Billion), by Country 2026 & 2034
Figure 17: Selangor Malaysia Luxury Goods Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Johor Malaysia Luxury Goods Market Revenue (Billion), by Product Type 2026 & 2034
Figure 19: Johor Malaysia Luxury Goods Market Revenue Share (%), by Product Type 2026 & 2034
Figure 20: Johor Malaysia Luxury Goods Market Revenue (Billion), by End User 2026 & 2034
Figure 21: Johor Malaysia Luxury Goods Market Revenue Share (%), by End User 2026 & 2034
Figure 22: Johor Malaysia Luxury Goods Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 23: Johor Malaysia Luxury Goods Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 24: Johor Malaysia Luxury Goods Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Johor Malaysia Luxury Goods Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Penang Malaysia Luxury Goods Market Revenue (Billion), by Product Type 2026 & 2034
Figure 27: Penang Malaysia Luxury Goods Market Revenue Share (%), by Product Type 2026 & 2034
Figure 28: Penang Malaysia Luxury Goods Market Revenue (Billion), by End User 2026 & 2034
Figure 29: Penang Malaysia Luxury Goods Market Revenue Share (%), by End User 2026 & 2034
Figure 30: Penang Malaysia Luxury Goods Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 31: Penang Malaysia Luxury Goods Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 32: Penang Malaysia Luxury Goods Market Revenue (Billion), by Country 2026 & 2034
Figure 33: Penang Malaysia Luxury Goods Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Sarawak Malaysia Luxury Goods Market Revenue (Billion), by Product Type 2026 & 2034
Figure 35: Sarawak Malaysia Luxury Goods Market Revenue Share (%), by Product Type 2026 & 2034
Figure 36: Sarawak Malaysia Luxury Goods Market Revenue (Billion), by End User 2026 & 2034
Figure 37: Sarawak Malaysia Luxury Goods Market Revenue Share (%), by End User 2026 & 2034
Figure 38: Sarawak Malaysia Luxury Goods Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 39: Sarawak Malaysia Luxury Goods Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 40: Sarawak Malaysia Luxury Goods Market Revenue (Billion), by Country 2026 & 2034
Figure 41: Sarawak Malaysia Luxury Goods Market Revenue Share (%), by Country 2026 & 2034
Figure 42: Langkawi & Duty-Free Zones Malaysia Luxury Goods Market Revenue (Billion), by Product Type 2026 & 2034
Figure 43: Langkawi & Duty-Free Zones Malaysia Luxury Goods Market Revenue Share (%), by Product Type 2026 & 2034
Figure 44: Langkawi & Duty-Free Zones Malaysia Luxury Goods Market Revenue (Billion), by End User 2026 & 2034
Figure 45: Langkawi & Duty-Free Zones Malaysia Luxury Goods Market Revenue Share (%), by End User 2026 & 2034
Figure 46: Langkawi & Duty-Free Zones Malaysia Luxury Goods Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 47: Langkawi & Duty-Free Zones Malaysia Luxury Goods Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 48: Langkawi & Duty-Free Zones Malaysia Luxury Goods Market Revenue (Billion), by Country 2026 & 2034
Figure 49: Langkawi & Duty-Free Zones Malaysia Luxury Goods Market Revenue Share (%), by Country 2026 & 2034
Figure 50: Rest of Malaysia Malaysia Luxury Goods Market Revenue (Billion), by Product Type 2026 & 2034
Figure 51: Rest of Malaysia Malaysia Luxury Goods Market Revenue Share (%), by Product Type 2026 & 2034
Figure 52: Rest of Malaysia Malaysia Luxury Goods Market Revenue (Billion), by End User 2026 & 2034
Figure 53: Rest of Malaysia Malaysia Luxury Goods Market Revenue Share (%), by End User 2026 & 2034
Figure 54: Rest of Malaysia Malaysia Luxury Goods Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 55: Rest of Malaysia Malaysia Luxury Goods Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 56: Rest of Malaysia Malaysia Luxury Goods Market Revenue (Billion), by Country 2026 & 2034
Figure 57: Rest of Malaysia Malaysia Luxury Goods Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Malaysia Luxury Goods Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: Global Malaysia Luxury Goods Market Revenue Billion Forecast, by End User 2020 & 2034
Table 3: Global Malaysia Luxury Goods Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 4: Global Malaysia Luxury Goods Market Revenue Billion Forecast, by Region 2020 & 2034
Table 5: Kuala Lumpur & Klang Valley Malaysia Luxury Goods Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 6: Kuala Lumpur & Klang Valley Malaysia Luxury Goods Market Revenue Billion Forecast, by End User 2020 & 2034
Table 7: Kuala Lumpur & Klang Valley Malaysia Luxury Goods Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 8: Kuala Lumpur & Klang Valley Malaysia Luxury Goods Market Revenue Billion Forecast, by Country 2020 & 2034
Table 9: Selangor Malaysia Luxury Goods Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 10: Selangor Malaysia Luxury Goods Market Revenue Billion Forecast, by End User 2020 & 2034
Table 11: Selangor Malaysia Luxury Goods Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 12: Selangor Malaysia Luxury Goods Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: Johor Malaysia Luxury Goods Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 14: Johor Malaysia Luxury Goods Market Revenue Billion Forecast, by End User 2020 & 2034
Table 15: Johor Malaysia Luxury Goods Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 16: Johor Malaysia Luxury Goods Market Revenue Billion Forecast, by Country 2020 & 2034
Table 17: Penang Malaysia Luxury Goods Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 18: Penang Malaysia Luxury Goods Market Revenue Billion Forecast, by End User 2020 & 2034
Table 19: Penang Malaysia Luxury Goods Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 20: Penang Malaysia Luxury Goods Market Revenue Billion Forecast, by Country 2020 & 2034
Table 21: Sarawak Malaysia Luxury Goods Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 22: Sarawak Malaysia Luxury Goods Market Revenue Billion Forecast, by End User 2020 & 2034
Table 23: Sarawak Malaysia Luxury Goods Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 24: Sarawak Malaysia Luxury Goods Market Revenue Billion Forecast, by Country 2020 & 2034
Table 25: Langkawi & Duty-Free Zones Malaysia Luxury Goods Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 26: Langkawi & Duty-Free Zones Malaysia Luxury Goods Market Revenue Billion Forecast, by End User 2020 & 2034
Table 27: Langkawi & Duty-Free Zones Malaysia Luxury Goods Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 28: Langkawi & Duty-Free Zones Malaysia Luxury Goods Market Revenue Billion Forecast, by Country 2020 & 2034
Table 29: Rest of Malaysia Malaysia Luxury Goods Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 30: Rest of Malaysia Malaysia Luxury Goods Market Revenue Billion Forecast, by End User 2020 & 2034
Table 31: Rest of Malaysia Malaysia Luxury Goods Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 32: Rest of Malaysia Malaysia Luxury Goods Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1What is the size of the Malaysia Luxury Goods Market?
The Malaysia luxury goods market is valued at USD 2.31 billion in 2026 and is forecast to reach USD 3.10 billion by 2031, representing a 6.05% CAGR over the forecast period, based on our proprietary bottom-up demand modelling.
2Which product segment leads the Malaysia luxury goods market?
Clothing and apparel led with 28.72% of 2025 market share, while jewellery is the fastest-growing category at a 6.59% CAGR to 2031, driven by collector and investment-grade demand.
3Which distribution channel dominates luxury goods sales in Malaysia?
Offline stores held 82.15% of 2025 value, led by flagship malls in the Klang Valley, although online stores are growing faster at a 7.38% CAGR through 2031.
4Who are the major companies in the Malaysia luxury goods market?
LVMH Moët Hennessy Louis Vuitton, Kering SA, Chanel Ltd., Hermès International S.A. and Prada S.p.A are the leading international players, competing alongside well-capitalised local luxury groups and duty-free operators.
5What are the key drivers of luxury goods demand in Malaysia?
Inbound tourist demand from China and the GCC (+1.5% CAGR impact), sustainability focus (+1.2%), halal-certified luxury demand (+1.1%) and rising e-commerce penetration (+0.9%) are the principal growth levers.
6Which Malaysian regions offer the strongest luxury retail opportunity?
Kuala Lumpur and the Klang Valley remain the flagship concentration with roughly 46% of market value, while Johor and Langkawi are the fastest-rising corridors on cross-border and duty-free dynamics respectively.
7What is the forecast CAGR for the Malaysia luxury goods market?
The market is projected to expand at a 6.05% CAGR between 2026 and 2031, with men's end-user demand growing faster at 6.92% and online channels at 7.38%.
8How is sustainability affecting luxury purchases in Malaysia?
Sustainability contributes an estimated +1.2% to market CAGR, with younger Malaysian buyers scrutinising supply chains and favouring exotic-skin-free leather, traceable sourcing and pre-owned luxury alternatives.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conducted 220+ in-depth interviews across the Malaysian luxury value chain, split 70-80% primary / 20-30% secondary, spanning brand general managers, boutique directors, mall leasing heads, duty-free concessionaires, distributors, licensing agents, clientelling leads and authenticated resale operators.
Interview panel composition was weighted to reflect revenue concentration: international maison subsidiaries and importers (around 40%), multi-brand and department-store retailers plus duty-free operators (around 25%), mall landlords and travel-retail concessionaires (around 20%), and logistics, authentication and resale specialists (around 15%).
Fieldwork deployed store-level intercepts and shopper exit interviews in Pavilion KL, Suria KLCC, The Gardens, Starhill Gallery, Johor premium outlets and Langkawi duty-free zones, ensuring demand-side observations reflect actual transaction values and basket composition.
All interview instruments were refreshed at the point of purchase, and every report delivery is updated to the date of purchase to reflect the latest boutique openings, price revisions and tourism arrivals.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Brand General Manager / Country Manager
30%
Boutique Director / Retail Operations Head
28%
Leasing Director / Mall Commercial Head
22%
Procurement & Clientelling Lead
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
International luxury brand subsidiaries & importers
40%
Multi-brand retailers, department stores & duty-free operators
25%
Mall landlords & travel-retail concessionaires
20%
Logistics, authentication & resale specialists
15%
Secondary Research & Industry Benchmarking
Corporate filings, investor presentations and annual reports of listed luxury conglomerates were triangulated against trade statistics from UN Comtrade, OECD illicit trade and counterfeit research, World Bank income and HNWI indicators, and Tourism Malaysia arrival data.
Standard financial databases — Bloomberg, Factiva, Hoovers and PitchBook — were used for deal tracking, brand ownership mapping and financial benchmarking.
Trade association and regulatory inputs included the Malaysian International Chamber of Commerce and Industry (MICCI), the Malaysia Retail Chain Association (MRCA), and JAKIM for halal certification standards, alongside official government sources (.gov) and recognised non-profit technical bodies.
Secondary data were never adopted wholesale: every third-party benchmark was cross-validated against our own primary channel checks and discarded if the variance exceeded tolerance thresholds.
Demand Modeling & Market Estimation
We applied simultaneous top-down and bottom-up methodologies, validated through multi-level data triangulation. The top-down frame anchors on national consumption, tourist spend and HNWI wallet allocation across luxury categories.
The bottom-up model aggregates store-level revenue across approximately 320 mono-brand and concession points, multiplied by observed average transaction value and annualised transaction frequency, then reconciled with import values and duty-free throughput.
Segment-level build-up applied category-specific attach rates: clothing & apparel 28.72% share, women 58.01% end-user share, offline 82.15% channel share and online 7.38% CAGR, with men's demand modelled separately at 6.92% CAGR to capture share shift.
Revenue estimates were escalated using a blended inflation and mix-shift index rather than headline CPI, and validated against quarterly mall tenant sales disclosures and tourism receipts.
Data Accuracy & Quality Check
Our proprietary estimation framework delivers a guaranteed data accuracy level of 85-90%, with confidence intervals reported at the 90% threshold for headline market value.
Multi-level triangulation compared bottom-up store aggregation, top-down consumption modelling and import-based reconciliation; variances above 7% triggered re-interview and reweighting of the channel panel.
All brand-level figures were cross-checked against at least two independent interview sources, and any single-source data point was flagged as directional rather than definitive.
The report is continuously refreshed; the version delivered reflects data as of the purchase date, with forecast tables re-based to the most recent confirmed quarter.