1What is the current size of the US retail colocation market?
The US retail colocation market was valued at USD 7.36 billion in 2025 and is projected to reach USD 23.97 billion by 2035, growing at a CAGR of 12.54%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 US - Retail Colocation Market
 by By Solution Type (Room Space, Rack Space, Cage Space, Suite), by By Service Type (Managed Hosting, Interconnection, Colocation, Remote Hands, Security), by By Organization Size (Large Enterprises, Small & Medium Enterprises), by By Tier Classification (Tier 1 and 2, Tier 3, Tier 4), by By Industry Vertical (BFSI, IT & Telecom, Government and Defense, Healthcare, Energy, Manufacturing, Others), by Northeast (Northern Virginia, New York, Boston), by South (Dallas, Atlanta, Miami), by West (Silicon Valley, Phoenix, Seattle), by Midwest (Chicago, Columbus), by Southwest (Nevada, Arizona) Forecast 2026-2034

Research Analyst


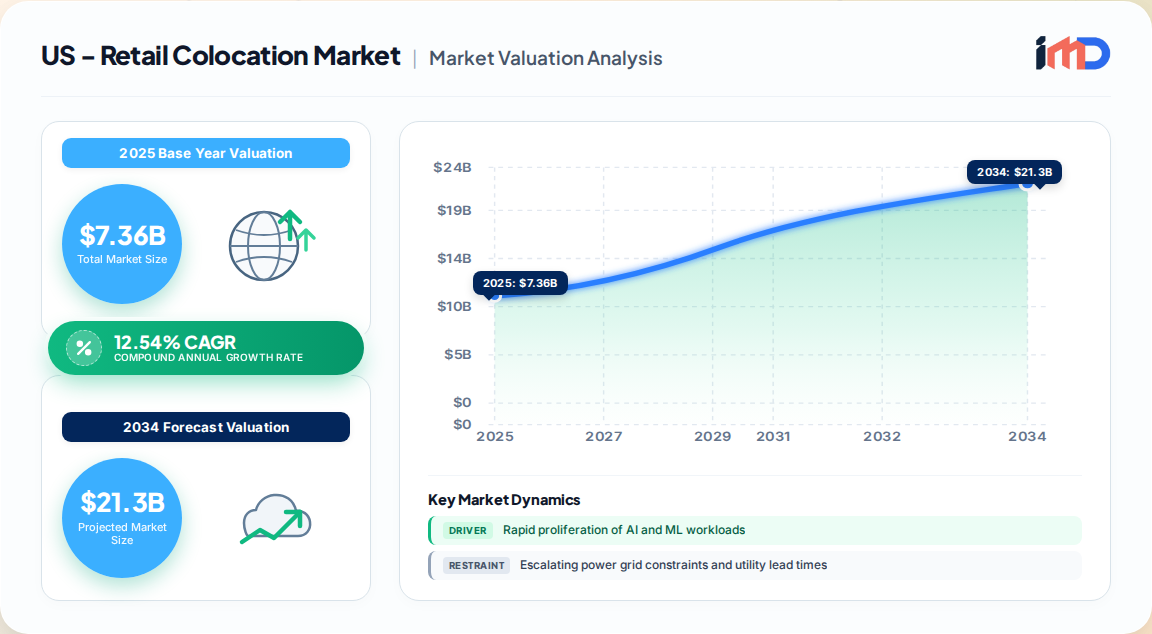
The US retail colocation market represents the largest national market within the global data center colocation landscape. Our proprietary primary research estimates the market at USD 7.36 billion in 2025, projected to expand to USD 23.97 billion by 2035, reflecting a robust CAGR of 12.54% over the forecast period. This growth is underpinned by the accelerating migration of enterprise workloads from on-premises infrastructure to shared, carrier-neutral facilities, coupled with the unrelenting demand for artificial intelligence (AI) and high-density computing.
Retail colocation—characterized by smaller lease units such as racks, cages, and private suites—remains the preferred model for small-to-medium enterprises (SMEs), start-ups, and large enterprises seeking flexible, scalable infrastructure without the capital burden of building and maintaining their own data centers. The United States accounts for over 37% of global colocation revenue, a position sustained by its dense concentration of hyperscale cloud regions, major network interconnection hubs, and a mature enterprise base demanding low-latency access to digital ecosystems.
Key hubs including Northern Virginia, Dallas, Chicago, Atlanta, and Silicon Valley continue to dominate capacity absorption. However, supply constraints—particularly power availability and utility interconnection delays—are reshaping the market landscape, driving operators to Tier-2 metros and edge locations. This report provides an authoritative, data-driven analysis of the US retail colocation market, covering market sizing, key trends, drivers, restraints, segmentation, competitive dynamics, and strategic opportunities.
The US retail colocation value chain is characterized by a complex ecosystem of suppliers, service providers, and end-users. Key participants include:
The US retail colocation market is segmented by solution type, service type, organization size, tier classification, and industry vertical. Our primary research reveals the following dynamics:
The US retail colocation market exhibits distinct regional dynamics, shaped by power availability, fiber connectivity, and state incentives.
The US retail colocation market is moderately concentrated, with the five largest operators holding approximately 48% of installed capacity. However, the market remains fragmented below the top tier, with numerous regional specialists and edge-focused providers targeting niche workloads.
Key players include Digital Realty Trust, Inc., Equinix, Inc., CyrusOne LLC, Quality Technology Services (QTS Realty Trust), and CoreSite Realty Corporation (American Tower). These operators are investing heavily in capacity expansion, liquid-cooling readiness, and interconnection ecosystems to capture AI-driven demand.
Recent strategic developments include:
Competitive differentiation increasingly hinges on power availability, sustainability credentials, interconnection density, and the ability to support high-density AI workloads with advanced cooling solutions.
Several high-growth opportunities are emerging in the US retail colocation market:
The US retail colocation market is not a traditional import/export market for physical goods; however, supply chain dynamics for critical data center equipment play a significant role in market development. Key imported components include:
Operators must navigate lead times, tariff exposure, and logistics risks when planning capacity expansions. Strategic partnerships with equipment vendors and diversified sourcing strategies are essential to mitigate supply chain vulnerabilities.
The US retail colocation market is poised for sustained, high-growth expansion, driven by AI, hybrid cloud, and interconnection demand. With a CAGR of 12.54% through 2035, the market offers significant opportunities for operators, investors, and technology providers. However, power constraints, construction costs, and sustainability imperatives will shape competitive dynamics. Stakeholders must prioritize strategic capacity planning, liquid-cooling readiness, and sustainable operations to capitalize on the next wave of digital infrastructure demand.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 12.54% from 2020-2034 |
| Segmentation |
|
By Organization Size
By Tier Classification
By Industry Vertical
| By Geography |
|
The US retail colocation market was valued at USD 7.36 billion in 2025 and is projected to reach USD 23.97 billion by 2035, growing at a CAGR of 12.54%.
The IT & Telecom vertical held the largest share at 35.33% in 2025, driven by network operators, software firms, and content delivery networks requiring scalable, low-latency infrastructure.
Rapid adoption of AI/ML workloads, hybrid cloud strategies, interconnection demand, and federal/state tax incentives are the primary growth drivers, with AI workloads alone contributing a 2.8% impact on CAGR.
Northern Virginia (Northeast region) dominates, accounting for approximately 28% of national revenue, although power constraints are driving new capacity to Dallas, Atlanta, and Phoenix.
Key operators include Digital Realty Trust, Equinix, CyrusOne, Quality Technology Services (QTS), and CoreSite Realty Corporation, which together hold about 48% of installed capacity.
Room space dominated with 40% share in 2025, while rack space is the fastest-growing segment at a CAGR of 17.28%, driven by SMEs and edge deployments.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CTO / VP Technology | 30% |
| VP Data Center Operations | 25% |
| Director of Infrastructure & Cloud | 25% |
| Head of Procurement & Facilities | 20% |
| Company Type | Representation (%) |
|---|---|
| Retail Colocation Operators | 35% |
| Hyperscale Cloud Providers | 20% |
| Enterprise End-Users | 25% |
| Infrastructure OEMs | 12% |
| Edge Colocation Specialists | 8% |
 Related Reports
