1What is the size of the Spain e-commerce logistics market?
Our proprietary primary research estimates the Spain e-commerce logistics market at USD 9.2 billion in 2025, projected to reach USD 14.8 billion by 2031 at a CAGR of 8.7%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Spain E-commerce Logistics Market
 by By Service Type (Warehousing, Transportation), by By Operational Area (Domestic, International), by By Model (3PL, 4PL, Others), by By Type (Forward Logistics, Reverse Logistics), by By Vertical (Apparel, Consumer Electronics, Food & Beverage, Healthcare, Automotive, Others), by Central Spain (Madrid), by Catalonia (Barcelona), by Andalusia (Seville, Malaga), by Valencia, by Basque Country, by Other Regions Forecast 2026-2034

Research Associate


 Related Reports

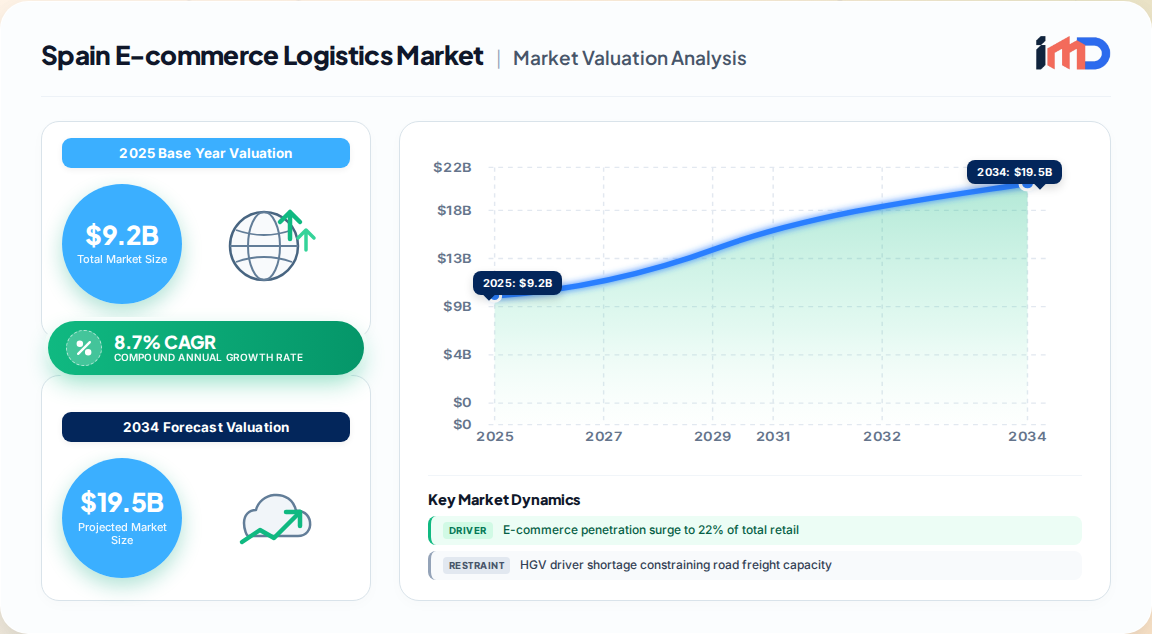
The Spain e-commerce logistics market is a strategically vital segment of the broader Spanish logistics industry, which reached USD 72.56 billion in 2025 and is projected to grow at a 3.28% CAGR to USD 97.04 billion by 2034. Within this ecosystem, e-commerce logistics represents the fastest-growing service line, fueled by the 6.83% CAGR of Spain's e-commerce market, which will expand from USD 130.48 billion in 2026 to USD 181.59 billion by 2031. Our proprietary primary research estimates the Spain e-commerce logistics market at USD 9.2 billion in 2025, forecast to reach USD 14.8 billion by 2031 at a 8.7% CAGR—outpacing both the overall logistics sector and the underlying e-commerce retail market.
This growth is underpinned by a structural shift in consumer behavior: mobile-first shopping, 5G coverage reaching 96% of urban areas, and instant account-to-account payment systems like Bizum have compressed checkout friction and raised delivery expectations. Spain's logistics investment surged 24% year-over-year to €690 million in H1 2026, directly expanding warehousing and last-mile capacity for e-commerce. The market is characterized by medium concentration, with integrated global players competing against specialized regional 3PLs and emerging crowd-shipping platforms.
The Spain e-commerce logistics value chain comprises five core layers, each with distinct economics and competitive dynamics:
| Layer | Activities | Key Metrics | Representative Participants |
|---|---|---|---|
| First-Mile/Origin | Pickup from merchant, consolidation, labeling | Pickup cost per parcel (€0.80–1.20) | Integrated 3PLs, merchant in-house |
| Warehousing & Fulfillment | Storage, pick-and-pack, inventory management | Storage cost per pallet/month (€12–18) | 3PL warehouses, micro-fulfillment centers |
| Line-Haul/Trunking | Inter-regional transport, hub transfers | Line-haul cost per km (€0.90–1.30) | Road carriers, rail intermodal |
| Last-Mile Delivery | Final-mile to consumer, parcel lockers | Cost per delivery (€2.50–4.00) | Parcel carriers, crowdshippers, locker networks |
| Returns & Reverse Logistics | Collection, sorting, refurbishment | Return rate (8–12% for fashion) | Reverse logistics specialists, 3PLs |
Warehousing remains the largest service segment globally, but transportation is the fastest-growing in Spain, driven by same-day delivery expectations and the expansion of express networks. The forward logistics segment dominates with roughly 68.7% share of e-commerce logistics volume, while reverse logistics grows faster as fashion and electronics return rates rise.
Spain's e-commerce logistics activity is heavily concentrated in three poles:
Investment in logistics real estate reached €690 million in H1 2026, a 24% year-over-year increase, with the majority directed to Madrid, Barcelona, and Valencia. The Corredor Mediterraneo rail freight enhancement is expected to shift some truck-to-rail modal share, though roadways will retain dominance.
The Spain e-commerce logistics market features a mix of global integrators, regional parcel carriers, and specialized fulfillment providers. Our primary research identifies the following competitive dynamics:
Recent developments include:
Spain's e-commerce logistics market is deeply integrated with international trade. In 2023, Spain recorded USD 457.1 billion in goods imports and USD 419.6 billion in goods exports, with a trade-to-GDP ratio of 72.19%. The country's HH market concentration index of 0.06 indicates a highly diversified trade portfolio, reducing dependency on any single partner.
For e-commerce logistics, key cross-border flows include:
Supply chain risks include port congestion at Algeciras (which handles approximately 5 million TEUs annually) and potential delays from EU Carbon Border Adjustment Mechanism compliance, which will increase documentation requirements for importers.
Our proprietary analysis identifies three high-opportunity white spaces in the Spain e-commerce logistics market:
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.7% from 2020-2034 |
| Segmentation |
|
By Model
By Type
By Vertical
| By Geography |
|
Our proprietary primary research estimates the Spain e-commerce logistics market at USD 9.2 billion in 2025, projected to reach USD 14.8 billion by 2031 at a CAGR of 8.7%.
Warehousing is the largest service segment, while transportation is the fastest-growing, driven by same-day delivery demand. 3PL providers hold 58.6% share of the overall logistics model mix.
Mobile-first shopping, 5G coverage reaching 96% of urban areas, instant payment systems like Bizum, and government digitalization vouchers worth EUR 3.067 billion are key demand drivers.
The market includes global integrators (DHL, FedEx, UPS), regional parcel carriers, 3PL fulfillment specialists, and crowd-shipping platforms. The market is of medium concentration.
HGV driver shortages, fuel price volatility, and fragmented regional regulations are the primary restraints, alongside rising labor costs and urban access restrictions.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Supply Chain Director | 30% |
| Logistics Manager | 35% |
| E-commerce Operations Head | 20% |
| Procurement Director | 15% |
| Company Type | Representation (%) |
|---|---|
| E-commerce Logistics Service Providers (3PLs, Parcel Carriers) | 40% |
| E-commerce Retailers and Brands | 25% |
| Warehousing and Fulfillment Center Operators | 15% |
| Last-Mile Technology and Platform Providers | 12% |
| Freight Forwarders and Customs Brokers | 8% |