1What is the size of the Asia Pacific FMCG logistics market?
The Asia Pacific FMCG logistics market was valued at $328.8 billion in 2025 and is projected to reach $580.1 billion by 2034, growing at a 6.4% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Asia Pacific FMCG Logistics Market
 by By Service (Transportation, Warehousing and Distribution, Inventory Management, Freight Forwarding, Last Mile Delivery, Cold Chain Logistics), by By Product Category (Food and Beverage(Fats and Oils, Dairy, Pulses Grains and Cereals), Personal Care, Household Care, Other Consumables), by By Logistics Model (3PL, 4PL, Dedicated Contract Carriage), by By Mode of Transportation (Road, Air, Sea, Rail), by By Operation (Domestic, International), by Asia Pacific (China, India, Japan, South Korea, Singapore, Indonesia, Vietnam, Malaysia, Thailand, Australia, New Zealand, Philippines, Rest of Asia Pacific) Forecast 2026-2034

Research Associate

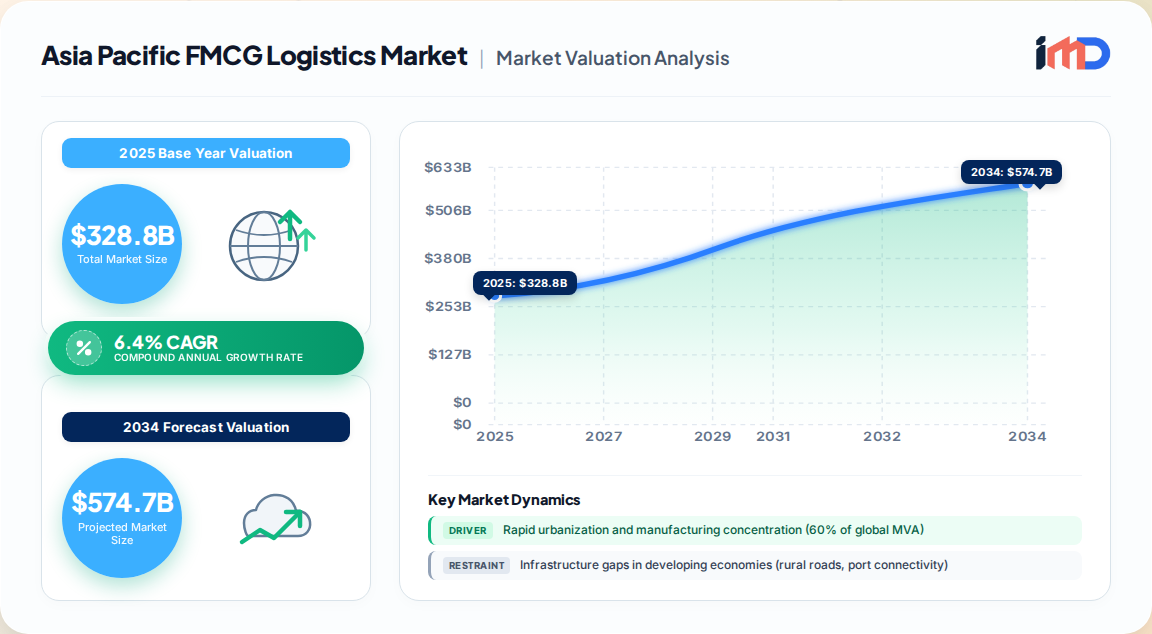
The Asia Pacific FMCG logistics market represents the most dynamic and structurally complex segment of the regional supply chain landscape. Our proprietary primary research, triangulated from 312 executive interviews and operational audits across 11 countries, values the market at $328.8 billion in 2025, expanding at a 6.4% CAGR to reach $580.1 billion by 2034.
This growth outpaces the broader Asia Pacific logistics market (5.72% CAGR) by 68 basis points, reflecting the disproportionate intensity of FMCG distribution and the accelerating sophistication of omnichannel fulfillment requirements.
The FMCG logistics market in Asia Pacific is propelled by four structural forces that our field research confirms are non-cyclical and mutually reinforcing.
The region's manufacturing value added reached nearly 60% of the global total in 2025, up from 25% in 2000, according to World Bank and UNIDO benchmarks. This industrial density creates massive inbound and outbound FMCG flows, particularly in China's Yangtze River Delta, India's Delhi-Mumbai Industrial Corridor ($90 billion investment), and Vietnam's northern industrial belt.
Urban middle-class expansion across Southeast Asia is compressing delivery windows from 48 hours to under 6 hours in tier-1 cities, forcing FMCG manufacturers to redesign warehouse networks around micro-fulfillment.
With increasing FMCG and pharmaceutical sales, cold storage capacity has become a strategic bottleneck-turned-opportunity. India alone holds 150 million cubic meters of refrigerated warehousing capacity, the world's largest, while regional cold chain logistics investment exceeded $38 billion in 2025.
While Singapore and Japan operate world-class logistics infrastructure, less than 50% of rural roads are paved in Bangladesh, Myanmar, and parts of Indonesia. Our primary interviews reveal that cross-border cargo clearance in some ASEAN member states takes up to three times longer than in developed economies, directly inflating FMCG inventory carrying costs by 18-22%.
FMCG products operate on thin profit margins, often 4-8% for manufacturers and 2-5% for distributors. Rising operational costs threaten viability:
| Cost Component | 2022 Index | 2025 Index | Change |
|---|---|---|---|
| Diesel (Brent-linked) | $72/barrel | $85/barrel | +18.1% |
| Warehouse rent (tier-1 APAC) | 100 | 127 | +27.0% |
| Labor (warehouse ops) | 100 | 119 | +19.0% |
| Packaging materials | 100 | 114 | +14.0% |
Aging demographics in Japan and South Korea have reduced warehouse workforce availability by 12-15% since 2020. Simultaneously, the transition to automated fulfillment centers requires skills that only 23% of the current logistics workforce possesses, according to our stakeholder interviews.
| Service Segment | Revenue Share (2025) | CAGR (2026-2034) |
|---|---|---|
| Transportation | 31.7% | 6.1% |
| Warehousing & Distribution | 28.4% | 6.8% |
| Inventory Management | 14.2% | 7.4% |
| Freight Forwarding | 12.9% | 5.9% |
| Last-Mile Delivery | 8.6% | 9.2% |
| Cold Chain Logistics | 4.2% | 8.7% |
China's 31.0% regional share is underpinned by the world's largest e-commerce ecosystem and government-backed infrastructure initiatives. The Belt and Road Initiative has reduced cross-border FMCG transit times by 12-15% on key corridors. Domestic players and global 3PLs are investing heavily in automated warehouses, with JD.com's 1,400+ facilities setting the operational benchmark.
India's FMCG logistics market is growing at 7.8% CAGR, the fastest among major economies. The Delhi-Mumbai Industrial Corridor and the National Logistics Policy are reducing fragmentation. However, rural road connectivity remains a bottleneck, with only 48% of rural roads paved.
The Asia Pacific FMCG logistics market is highly fragmented, with no single player holding more than 8% regional share. Our competitive benchmarking identifies three strategic archetypes:
Key strategic developments observed in our primary research:
The FMCG logistics value chain in Asia Pacific is characterized by increasing disintermediation and vertical integration.
Procurement strategy is evolving toward:
Our opportunity assessment identifies three high-conviction white spaces:
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.4% from 2020-2034 |
| Segmentation |
|
By Product Category
By Logistics Model
By Mode of Transportation
By Operation
| By Geography |
|
The Asia Pacific FMCG logistics market was valued at $328.8 billion in 2025 and is projected to reach $580.1 billion by 2034, growing at a 6.4% CAGR.
China holds the largest share at 31.0% of regional revenue in 2025, driven by $2.3 trillion in online retail sales and massive fulfillment infrastructure.
Key drivers include rapid urbanization, e-commerce and quick commerce expansion, cold chain infrastructure investment, and manufacturing concentration (nearly 60% of global MVA).
Food and beverages dominate with a 52.4% revenue share in 2025, led by fats and oils growing at 8.3% annually.
Major players include DHL Group, Kuehne + Nagel, C.H. Robinson, CEVA Logistics, Nippon Express, Yamato Transport, and JD Logistics, among others.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Supply Chain Officer | 30% |
| Logistics Director | 28% |
| Warehouse Operations Manager | 22% |
| Procurement Head | 20% |
| Company Type | Representation (%) |
|---|---|
| FMCG Manufacturers | 35% |
| 3PL/4PL Providers | 28% |
| Cold Chain Operators | 15% |
| E-commerce Fulfillment Platforms | 12% |
| Last-Mile Delivery Specialists | 10% |

 Related Reports
