1What is the size of the Malaysia freight logistics market in 2026?
The Malaysia freight logistics market is estimated at USD 33.49 billion in 2026 and is projected to reach USD 54.30 billion by 2035, growing at a CAGR of 5.52%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Malaysia Freight Logistics Market
 by Logistics Function (Freight Transport, Freight Forwarding, Courier Express and Parcel (CEP), Warehousing and Storage, Other Services), by End User Industry (Manufacturing, Wholesale and Retail Trade, Oil and Gas Mining and Quarrying, Construction, Agriculture Fishing and Forestry, Others), by Freight Transport Mode (Road Freight, Sea Freight, Rail Freight, Air Freight), by Central Region (Selangor, Kuala Lumpur, Putrajaya), by Southern Region (Johor, Melaka, Negeri Sembilan), by Northern Region (Penang, Perak, Kedah, Perlis), by East Coast Region (Pahang, Terengganu, Kelantan), by East Malaysia (Sabah, Sarawak, Labuan) Forecast 2026-2034

Research Associate


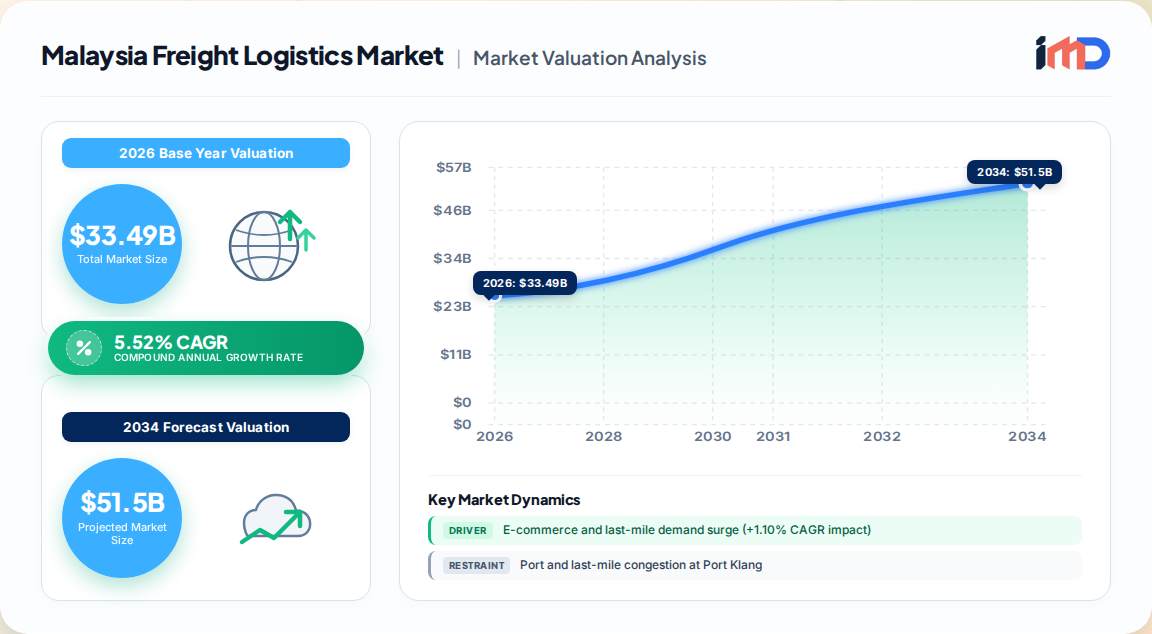
The Malaysia freight logistics market is projected to grow from USD 33.49 billion in 2026 to USD 54.30 billion by 2035, registering a CAGR of 5.52% over the forecast period. This expansion is anchored by Malaysia's strategic position as a trade gateway between the Indian and Pacific Oceans, sustained foreign direct investment in manufacturing, and a rapidly maturing e-commerce ecosystem.
Port Klang's rise among the world's busiest container terminals, handling over 14.2 million TEUs in 2024, and sustained FDI-led manufacturing expansion are creating recurring freight demand that flows through cross-border forwarding, advanced warehousing, and specialized carrier partnerships. The National Transport Policy 2019–2030 and targeted diesel subsidy restructuring have further reduced cost volatility for haulage operators, supporting steady capacity expansion across road, rail, and maritime corridors.
| Driver | Estimated Impact on CAGR | Geographic Relevance | Timeline |
|---|---|---|---|
| E-commerce and last-mile demand surge | +1.10% | Nationwide | Short-term (≤2 years) |
| ECRL and rail infrastructure investment | +0.85% | Central–East Coast | Long-term (≥4 years) |
| FDI-driven manufacturing expansion | +0.75% | Central, Northern | Medium-term (2–4 years) |
| RCEP and CPTPP tariff liberalization | +0.60% | Nationwide | Medium-term (2–4 years) |
| Cold-chain and temperature-controlled expansion | +0.50% | Central, Southern | Medium-term (2–4 years) |
| Digital customs and National Single Window rollout | +0.45% | Nationwide | Short-term (≤2 years) |
| Johor–Singapore Special Economic Zone | +0.40% | Southern | Long-term (≥4 years) |
Malaysia's e-commerce gross merchandise value exceeded USD 15 billion in 2024, growing at approximately 18% annually, which has forced courier operators to establish micro-fulfillment nodes in secondary cities including Ipoh, Kuching, and Kota Kinabalu. The East Coast Rail Link, a 665-kilometer dual-track line representing an estimated MYR 50 billion investment, is expected to carry approximately 53 million tons of freight annually between the east coast and Port Klang once fully operational, significantly restructuring cost economics for electronics, petrochemicals, and palm oil shipments.
| Restraint | Estimated Impact on CAGR | Geographic Relevance | Timeline |
|---|---|---|---|
| Port and last-mile congestion | -0.80% | Klang and Port Klang | Short-term (≤2 years) |
| Chronic truck-driver shortage | -0.60% | Port Klang and Penang Port | Medium-term (2–4 years) |
| Domestic cabotage policy limits coastal shipping | -0.30% | Sarawak, Sabah, Peninsular Malaysia | Short-term (≤2 years) |
| Planned Euro-V emission rules, capex squeeze | -0.20% | Nationwide | Medium-term (2–4 years) |
Port congestion in Malaysia, characterized by insufficient berth space and outdated equipment, is compounded by geopolitical tensions that have disrupted sea trade routes and led to port overcrowding. Cargo handling blockages, customs clearance delays, and operational inefficiencies slow goods movement, while persistent truck-driver shortages around Port Klang and Penang Port constrain the delivery commitments a fleet can reliably support.
The Malaysia freight logistics market exhibits distinct regional dynamics aligned with industrial clusters and trade gateways.
| Region | Market Share (2025) | Key Characteristics |
|---|---|---|
| Central Region | 44.6% | Anchored by Port Klang and KLIA; Selangor alone generated USD 10.85 billion in freight logistics activity in 2025 |
| Southern Region | 22.1% | Fastest-growing corridor at 6.35% CAGR; driven by Johor–Singapore Special Economic Zone and Tanjung Pelepas port expansion |
| Northern Region | 16.3% | Penang accounts for 38.4% of regional freight share, driven by electronics manufacturing exports |
| East Coast Region | 9.2% | Tied to ECRL corridor and petrochemical freight; Pahang generated about USD 1.72 billion in 2025 |
| East Malaysia | 7.8% | Supported by palm oil export infrastructure and cross-border trade with Brunei and Indonesia |
The Central Region, comprising Selangor, Kuala Lumpur, and Putrajaya, commands the largest share, benefiting from Port Klang's container volumes and KLIA's air cargo terminal, which processed 780,000 tonnes in 2024. The Southern Region is being reshaped by the Johor–Singapore Special Economic Zone, formalized in January 2025, expected to create over 100,000 jobs and draw around MYR 60 billion in incremental investment into logistics parks, bonded warehouses, and intermodal terminals. The Northern Region's Penang corridor continues to attract semiconductor-related freight volumes, while the East Coast Region is poised for transformation as the ECRL links Kuantan Port to Port Klang, reducing freight transit time by roughly 50%.
The Malaysia freight logistics market is characterized by medium concentration, with a mix of global integrated providers and established domestic operators competing across freight forwarding, contract logistics, and last-mile delivery.
Leading Players: DHL Group, GDEX Group, J&T Express, POS Malaysia Bhd, City-Link Express, CJ Century Logistics Holdings, Tiong Nam Logistics Holdings, Pos Logistics Berhad, Freight Management Holdings, DB Schenker, FedEx, Kuehne + Nagel, Keretapi Tanah Melayu Berhad, MMC Corporation Berhad, and Hextar Technologies Solutions Berhad.
Recent Developments:
The Malaysia freight logistics value chain spans from inbound raw material procurement through manufacturing, warehousing, and outbound distribution to end customers.
Supply chain risks include port congestion, driver shortages, and cabotage policy constraints that limit coastal shipping between Peninsular Malaysia and East Malaysia. However, government investment in the ECRL and Pan-Borneo Highway is expected to mitigate these bottlenecks over the medium term.
By 2035, the Malaysia freight logistics market is poised to solidify the nation's standing as a top-tier ASEAN logistics hub, with value creation shifting toward contract logistics, automated warehousing, and multimodal network design.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.52% from 2020-2034 |
| Segmentation |
|
By End User Industry
By Freight Transport Mode
| By Geography |
|
The Malaysia freight logistics market is estimated at USD 33.49 billion in 2026 and is projected to reach USD 54.30 billion by 2035, growing at a CAGR of 5.52%.
Freight transport holds the largest share at 51.2% in 2025, driven by road and sea modes, while manufacturing is the dominant end-user industry with a 42.1% share.
Key drivers include e-commerce growth (adding 1.10% to CAGR), ECRL rail investment (+0.85%), FDI-driven manufacturing (+0.75%), and RCEP/CPTPP trade liberalization (+0.60%).
The Southern Region, centered on Johor, is the fastest-growing corridor with a projected CAGR of 6.35%, supported by the Johor–Singapore Special Economic Zone.
Major players include DHL Group, GDEX Group, J&T Express, POS Malaysia Bhd, City-Link Express, CJ Century Logistics Holdings, and Tiong Nam Logistics Holdings.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Supply Chain Director | 30% |
| Logistics Operations Manager | 25% |
| Procurement Head | 25% |
| Chief Strategy Officer | 20% |
| Company Type | Representation (%) |
|---|---|
| Integrated Logistics Service Providers | 30% |
| Freight Forwarding & Customs Brokerage Firms | 25% |
| Contract Warehousing & Cold-Chain Operators | 20% |
| Last-Mile Parcel & Express Carriers | 15% |
| Port & Terminal Operating Companies | 10% |
 Related Reports
