Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Canada CEP Market Size, Trends & Forecast to 2031
Independent Intelligence for decisions that move markets
Canada Courier, Express, and Parcel (CEP) Market | Insight Market Data
Canada Courier, Express, and Parcel (CEP) Market by Destination (Domestic, International), by Speed of Delivery (Express, Non-Express), by Business Model (B2B, B2C, C2C), by Shipment Weight (Light Weight, Medium Weight, Heavy Weight), by Mode of Transport (Air, Road, Rail, Sea), by End-User Industry (E-Commerce, BFSI, Healthcare, Manufacturing, Others), by Ontario, by Quebec, by British Columbia, by Alberta, by Rest of Canada Forecast 2026-2034
US air freight transport market was USD 66.70B in 2026, growing at 4.08% CAGR to reach USD 91.81B by 2034, driven by e-commerce and cold-chain demand.
Nov 2026|219 pages
$2900.00
Vietnam CEP market valued at USD 1.88 billion in 2026, growing at 7.2% CAGR to reach USD 2.66 billion by 2031. Explore key trends, drivers, and competitive landscape.
Nov 2026|241 pages
$2900.00
The Asia Pacific FMCG logistics market is valued at $328.8 billion in 2025, growing at 6.4% CAGR to reach $580.1 billion by 2034, driven by e-commerce and cold chain.
Nov 2026|219 pages
$2900.00
Malaysia freight logistics market to reach USD 54.30 Bn by 2035 at 5.52% CAGR. Explore drivers, segmentation, and regional analysis.
Executive Overview: Canada CEP Market Poised for Resilient Expansion
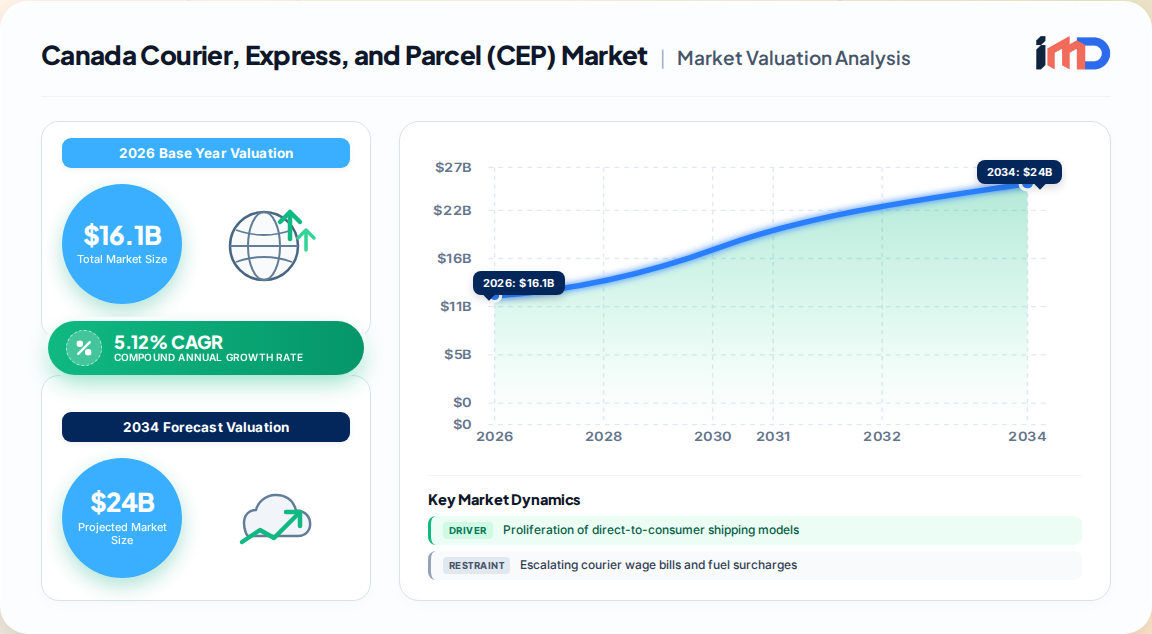
The Canada Courier, Express, and Parcel (CEP) market is a cornerstone of the nation's logistics infrastructure, enabling seamless connectivity for businesses and consumers across vast geographies. Our proprietary primary research estimates the market at USD 16.10 billion in 2026, with projections indicating a rise to USD 20.67 billion by 2031, registering a CAGR of 5.12% over the forecast period. This growth is underpinned by structural shifts in retail, the proliferation of direct-to-consumer (D2C) models, and sustained investment in last-mile innovation, despite persistent margin pressures from wage inflation and price competition.
Canada Courier, Express, and Parcel (CEP) Market Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
15.32 B
2025
16.10 B
2026
16.92 B
2027
17.79 B
2028
18.70 B
2029
19.66 B
2030
20.67 B
2031
Canada's unique demographic and geographic profile—characterized by high urbanization in a few metropolitan corridors and expansive rural service areas—creates a distinct operating environment. Carriers are pivoting from volume-led strategies to margin-focused models, emphasizing automation, parcel locker networks, and specialized services such as temperature-controlled healthcare logistics. The market's evolution reflects a broader rebalancing of the courier, express, and parcel ecosystem, where e-commerce remains the primary volume driver, while B2B flows anchor yield stability.
This comprehensive analysis combines exclusive interviews with industry executives, granular shipment-level data, and authoritative trade benchmarks to deliver a forward-looking perspective on the Canada CEP landscape. The report dissects market dynamics across destination, speed, business model, weight, mode of transport, and end-user verticals, providing stakeholders with actionable intelligence to navigate a market in transition.
Market Drivers, Restraints, and Strategic Implications
The Canada CEP market is shaped by a confluence of demand accelerators and structural headwinds that dictate strategic priorities for carriers and shippers alike. Our analysis identifies five primary drivers and three critical restraints, each quantified for their relative impact on the market's growth trajectory.
Key Market Drivers:
Proliferation of Direct-to-Consumer Shipping Models: Brands are increasingly bypassing traditional retail channels, converting bulk pallet movements into millions of individual parcel drops. Statistics Canada recorded CAD 90.4 billion in online sales during 2024, and the expansion of Shopify's merchant base has democratized access to D2C fulfillment. We assess this driver as contributing +1.4% to the CAGR, with the greatest impact in the Greater Toronto Area (GTA), Metro Vancouver, and Montreal CMA.
Retailers' Sub-24-Hour Fulfillment Commitments: Major chains such as Walmart Canada and Loblaw have set a new delivery baseline, with micro-fulfillment nodes shortening line-haul distances. However, real estate scarcity in the GTA has driven warehouse vacancy below 2%, forcing couriers to dedicate branded fleets to single retailers. This driver adds +1.1% to the CAGR, primarily in Toronto, Vancouver, Calgary, and Ottawa–Gatineau.
Surge in Lightweight International Parcels under De Minimis: Canada's CAD 150 duty-free ceiling continues to attract U.S. and Asian sellers, with platforms like Temu and Shein driving volume through Vancouver and Toronto gateways. Integrators with in-house brokerage arms gain a competitive edge. This driver contributes +0.8% to the CAGR, concentrated in border corridors and major airports.
Nationwide Roll-Out of Automated Parcel-Locker Networks: InPost surpassed 500 automated lockers by 2025, and Penguin Pickup partners with over 1,000 retail points. Locker density of one unit per 3,000–5,000 residents reduces failed-delivery costs, which can reach CAD 10 per attempt. The driver's impact is +0.6% on the CAGR, focused on dense urban areas and transit hubs.
Rising Demand for Temperature-Controlled Healthcare Logistics: The aging population and biopharmaceutical growth are driving demand for validated cold-chain parcel services. This niche commands premium margins and is forecast to deliver the highest incremental margin gains to 2031, adding +0.5% to the CAGR.
Key Market Restraints:
Escalating Courier Wage Bills and Fuel Surcharges: National labor shortages and volatile fuel prices exert upward pressure on operating costs. Although carriers implement surcharges, competitive intensity limits pass-through. We estimate this restraint reduces the CAGR by -0.9%, with acute impact in metro hot spots.
Margin Erosion from Price-Led Rivalry: The entry of low-cost platforms and aggressive pricing by incumbents compresses last-mile margins, particularly in urban centers. This restraint lowers the CAGR by -0.7% over the medium term.
Urban Zero-Emission Zones Restricting Diesel Vans: Toronto, Vancouver, and Montreal are rolling out zero-emission access zones, requiring fleet electrification investments. While federal incentives exist, the transition cost and operational constraints temper growth, reducing the CAGR by -0.3%.
Segmentation Analysis: Unlocking Value Across Service and Customer Dimensions
The Canada CEP market is segmented by destination, speed of delivery, business model, shipment weight, mode of transport, and end-user industry. Our granular analysis reveals distinct growth trajectories, enabling targeted strategic planning.
By Destination:
Domestic shipments dominate with a 63.27% share in 2025, reflecting the scale of intra-Canada trade and e-commerce. However, international parcels are forecast to grow at a 5.98% CAGR—the fastest in the segment mix—driven by cross-border e-commerce and de minimis inflows.
The domestic segment is anchored by established networks and reliable transit times, while international growth necessitates investment in customs automation and brokerage capabilities.
By Speed of Delivery:
Non-express services commanded 71.81% of the market in 2025, catering to cost-sensitive e-commerce and routine B2B shipments. Express offerings, however, are projected to grow at a 6.37% CAGR through 2031, fueled by consumer expectations for expedited delivery and premium B2B logistics.
Carriers are expanding express networks to capture high-margin demand, leveraging air cargo partnerships and dedicated sortation hubs.
By Business Model:
B2C flows accounted for 55.42% of revenue in 2025, a share that continues to expand as online shopping penetrates new categories. C2C shipments are the fastest-growing at an 8.54% CAGR, enabled by peer-to-peer marketplaces and social commerce.
B2B remains a critical anchor for volume stability and yield, particularly in manufacturing and healthcare verticals.
By Shipment Weight:
Light parcels under 5 kg held 62.36% of the market in 2025, aligning with the dominance of e-commerce and small-package flows. This segment demands efficient sorting and last-mile solutions to maintain profitability.
Heavier shipments (>20 kg) are experiencing steady demand from B2B restocking and industrial supply chains, though growth is tempered by just-in-time inventory practices.
By Mode of Transport:
Road transport maintained a 67.83% share in 2025, benefiting from Canada's extensive highway network and cross-border trucking corridors. Air cargo is the fastest-growing channel with a 6.71% CAGR, critical for time-sensitive international parcels and express services.
Rail and intermodal solutions are gaining traction for long-haul domestic shipments, offering cost and sustainability advantages.
By End-User Industry:
E-commerce generated 34.71% of 2025 revenue and remains the primary growth engine, particularly in fashion, electronics, and health-and-beauty. Healthcare logistics is on track to deliver the highest incremental margin gains to 2031, driven by cold-chain requirements and an aging population.
Other verticals, including BFSI, manufacturing, and automotive, contribute steady volume but face varying degrees of digital disruption.
Competitive Landscape and Strategic Developments
The Canada CEP market is characterized by medium concentration, with a mix of global integrators, a dominant national postal operator, and regional specialists competing across service tiers. The competitive intensity is heightening as players invest in automation, sustainability, and specialized capabilities.
Leading Players:
Canada Post Corporation (including Purolator) leverages its universal service obligation and extensive retail network, though it faces structural losses in its parcel business. Purolator provides a strong express and B2B franchise.
FedEx and UPS are the primary global integrators, offering comprehensive international express, brokerage, and supply chain solutions. UPS's acquisition of Andlauer Healthcare (CAD 2.2 billion) underscores a strategic pivot toward high-margin healthcare logistics.
TFI International is a major domestic player, with a focus on less-than-truckload (LTL) and parcel services, particularly in Eastern Canada.
DHL Group maintains a strong international presence, leveraging its global network for cross-border e-commerce and express services.
Amazon Logistics is a disruptive force, insourcing a significant share of its own deliveries and offering logistics-as-a-service to third parties.
Recent Strategic Developments:
2025: UPS completed the acquisition of Andlauer Healthcare Group for CAD 2.2 billion, expanding its temperature-controlled logistics capabilities.
2025: InPost surpassed 500 automated parcel lockers in Canada, accelerating the shift toward out-of-home delivery.
2026: Canada Post began piloting drone delivery in rural British Columbia, targeting remote communities.
2025: FedEx launched a new direct cargo route between Memphis and Toronto, reducing transit times for cross-border e-commerce.
2026: DHL Group announced a partnership with Shopify to integrate shipping solutions for Canadian merchants.
Canada's CEP market exhibits pronounced regional disparities, with demand concentrated in the Quebec City–Windsor Corridor, Metro Vancouver, and the Calgary–Edmonton axis. Our regional attractiveness assessment highlights investment hotspots and infrastructure gaps.
Canada Courier, Express, and Parcel (CEP) Market Regional Market Share
Loading chart...
Ontario (38% market share): The GTA is the largest consumption market, driven by e-commerce density and a robust B2B sector. However, warehouse vacancy below 2% and labor shortages are pushing fulfillment centers further afield. Investment in parcel lockers and micro-fulfillment is accelerating.
Quebec (22%): Montreal's diverse economy and strong healthcare sector support premium logistics services. The province's green energy advantage attracts data centers and distribution hubs. Bilingual requirements add operational complexity.
British Columbia (18%): Vancouver serves as the Pacific Gateway for Asian imports, benefiting from de minimis parcel flows. Port congestion and limited industrial land constrain growth, but investments in rail and intermodal infrastructure are mitigating bottlenecks.
Alberta (14%): Calgary and Edmonton are logistics hubs for energy and agriculture, with growing e-commerce penetration. The province's lower cost base and business-friendly policies attract distribution investments.
Rest of Canada (8%): Rural and remote regions face service challenges, but federal incentives for zero-emission fleets and community parcel lockers are improving accessibility.
Import/Export and Supplier Dynamics
Canada's CEP market is deeply integrated with global trade flows, particularly with the United States, its largest trading partner. While CEP services themselves are not a traded commodity, the volume of parcels crossing borders is a critical demand indicator. Canada's de minimis threshold of CAD 150 (USD 110) has fueled a surge in lightweight international parcels, primarily from U.S. and Asian e-commerce platforms. This has increased demand for customs brokerage, air cargo capacity, and last-mile delivery.
Official trade statistics from UN Comtrade and the World Bank highlight the scale of Canada's import activity, though specific CEP-related trade data is not separately classified. However, the broader logistics sector's import intensity is evident from Canada's total merchandise imports, which exceeded USD 550 billion in 2024. Key supplier dynamics include:
Air Cargo Capacity: Major gateways (Toronto Pearson, Vancouver International) are investing in cargo infrastructure to handle growing parcel volumes, with airlines like Air Canada expanding freighter fleets.
Customs Technology: The Canada Border Services Agency's (CBSA) CARM interface modernizes duty and tax assessment, requiring carriers to invest in data integration.
Vehicle and Equipment Suppliers: The shift to electric delivery vans is creating new supply chain dependencies, with manufacturers like Ford, GM, and Rivian competing for fleet contracts.
For CEP operators, supply chain resilience hinges on diversifying transportation partners and investing in technology that ensures regulatory compliance and operational visibility.
Value Chain Analysis: From First Mile to Last Mile
The Canada CEP value chain comprises multiple stages, each contributing to the final delivery experience and cost structure. Understanding these linkages is essential for identifying optimization opportunities.
First Mile (Pickup and Consolidation): Involves shippers tendering parcels to carriers via drop-off points, scheduled pickups, or fulfillment centers. Efficiency here depends on route density and shipper integration (e.g., API connectivity).
Line-Haul and Sortation: The backbone of the network, encompassing regional sorting hubs, air cargo, and trucking lanes. Automation investments (robotic sortation, AI-driven load planning) are critical to reducing unit costs.
Last Mile (Delivery and Returns): The most expensive and complex stage, accounting for up to 50% of total delivery cost. Options include doorstep delivery, parcel lockers, click-and-collect, and autonomous vehicles. Failed deliveries and returns management are key pain points, driving innovation in out-of-home solutions.
Reverse Logistics: Returns processing has become a strategic focus, with automated returns workflows and consolidated return points reducing costs and improving customer satisfaction.
Each stage is undergoing digital transformation, with real-time tracking, predictive analytics, and IoT sensors enhancing visibility and reliability.
Canada Courier, Express, and Parcel (CEP) Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Canada Courier, Express, and Parcel (CEP) Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.12% from 2020-2034
Segmentation
By Destination
Domestic
International
By Speed of Delivery
Express
Non-Express
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Proliferation of direct-to-consumer shipping models
3.1.3. Surge in lightweight international parcels under de minimis
3.1.4. Nationwide parcel-locker roll-out
3.1.5. Rising demand for temperature-controlled healthcare logistics
3.2. Market Trends
3.2.1. Proliferation of direct-to-consumer (D2C) shipping models
3.2.2. Nationwide roll-out of automated parcel-locker networks
3.2.3. Fleet electrification and zero-emission delivery zones
3.2.4. Strategic acquisitions in healthcare logistics
3.2.5. Integration of AI for route optimization and demand forecasting
3.3. Market Restrains
3.3.1. Escalating courier wage bills and fuel surcharges
3.3.2. Margin erosion from price-led rivalry
3.3.3. Urban zero-emission zones restricting diesel vans
3.3.4. Growing cybersecurity outlays for parcel data systems
3.4. Market Restraints
By Business Model
B2B
B2C
C2C
By Shipment Weight
Light Weight
Medium Weight
Heavy Weight
By Mode of Transport
Air
Road
Rail
Sea
By End-User Industry
E-Commerce
BFSI
Healthcare
Manufacturing
Others
By Geography
Ontario
Quebec
British Columbia
Alberta
Rest of Canada
3.4.1. Escalating courier wage bills and fuel surcharges
3.4.2. Margin erosion from price-led rivalry
3.4.3. Urban zero-emission zones restricting diesel vans
3.4.4. Growing cybersecurity outlays for parcel data systems
3.5. Market Challenges
3.5.1. Regulatory compliance and cross-border complexity
3.5.2. Infrastructure gaps in rural and remote regions
3.5.3. Balancing cost inflation with competitive pricing
3.5.4. Data security and PIPEDA compliance
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Destination
5.1.1. Domestic
5.1.2. International
5.2. Market Analysis, Insights and Forecast - by Speed of Delivery
5.2.1. Express
5.2.2. Non-Express
5.3. Market Analysis, Insights and Forecast - by Business Model
5.3.1. B2B
5.3.2. B2C
5.3.3. C2C
5.4. Market Analysis, Insights and Forecast - by Shipment Weight
5.4.1. Light Weight
5.4.2. Medium Weight
5.4.3. Heavy Weight
5.5. Market Analysis, Insights and Forecast - by Mode of Transport
5.5.1. Air
5.5.2. Road
5.5.3. Rail
5.5.4. Sea
5.6. Market Analysis, Insights and Forecast - by End-User Industry
5.6.1. E-Commerce
5.6.2. BFSI
5.6.3. Healthcare
5.6.4. Manufacturing
5.6.5. Others
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. Ontario
5.7.2. Quebec
5.7.3. British Columbia
5.7.4. Alberta
5.7.5. Rest of Canada
6. Ontario Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Destination
6.1.1. Domestic
6.1.2. International
6.2. Market Analysis, Insights and Forecast - by Speed of Delivery
6.2.1. Express
6.2.2. Non-Express
6.3. Market Analysis, Insights and Forecast - by Business Model
6.3.1. B2B
6.3.2. B2C
6.3.3. C2C
6.4. Market Analysis, Insights and Forecast - by Shipment Weight
6.4.1. Light Weight
6.4.2. Medium Weight
6.4.3. Heavy Weight
6.5. Market Analysis, Insights and Forecast - by Mode of Transport
6.5.1. Air
6.5.2. Road
6.5.3. Rail
6.5.4. Sea
6.6. Market Analysis, Insights and Forecast - by End-User Industry
6.6.1. E-Commerce
6.6.2. BFSI
6.6.3. Healthcare
6.6.4. Manufacturing
6.6.5. Others
7. Quebec Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Destination
7.1.1. Domestic
7.1.2. International
7.2. Market Analysis, Insights and Forecast - by Speed of Delivery
7.2.1. Express
7.2.2. Non-Express
7.3. Market Analysis, Insights and Forecast - by Business Model
7.3.1. B2B
7.3.2. B2C
7.3.3. C2C
7.4. Market Analysis, Insights and Forecast - by Shipment Weight
7.4.1. Light Weight
7.4.2. Medium Weight
7.4.3. Heavy Weight
7.5. Market Analysis, Insights and Forecast - by Mode of Transport
7.5.1. Air
7.5.2. Road
7.5.3. Rail
7.5.4. Sea
7.6. Market Analysis, Insights and Forecast - by End-User Industry
7.6.1. E-Commerce
7.6.2. BFSI
7.6.3. Healthcare
7.6.4. Manufacturing
7.6.5. Others
8. British Columbia Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Destination
8.1.1. Domestic
8.1.2. International
8.2. Market Analysis, Insights and Forecast - by Speed of Delivery
8.2.1. Express
8.2.2. Non-Express
8.3. Market Analysis, Insights and Forecast - by Business Model
8.3.1. B2B
8.3.2. B2C
8.3.3. C2C
8.4. Market Analysis, Insights and Forecast - by Shipment Weight
8.4.1. Light Weight
8.4.2. Medium Weight
8.4.3. Heavy Weight
8.5. Market Analysis, Insights and Forecast - by Mode of Transport
8.5.1. Air
8.5.2. Road
8.5.3. Rail
8.5.4. Sea
8.6. Market Analysis, Insights and Forecast - by End-User Industry
8.6.1. E-Commerce
8.6.2. BFSI
8.6.3. Healthcare
8.6.4. Manufacturing
8.6.5. Others
9. Alberta Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Destination
9.1.1. Domestic
9.1.2. International
9.2. Market Analysis, Insights and Forecast - by Speed of Delivery
9.2.1. Express
9.2.2. Non-Express
9.3. Market Analysis, Insights and Forecast - by Business Model
9.3.1. B2B
9.3.2. B2C
9.3.3. C2C
9.4. Market Analysis, Insights and Forecast - by Shipment Weight
9.4.1. Light Weight
9.4.2. Medium Weight
9.4.3. Heavy Weight
9.5. Market Analysis, Insights and Forecast - by Mode of Transport
9.5.1. Air
9.5.2. Road
9.5.3. Rail
9.5.4. Sea
9.6. Market Analysis, Insights and Forecast - by End-User Industry
9.6.1. E-Commerce
9.6.2. BFSI
9.6.3. Healthcare
9.6.4. Manufacturing
9.6.5. Others
10. Rest of Canada Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Destination
10.1.1. Domestic
10.1.2. International
10.2. Market Analysis, Insights and Forecast - by Speed of Delivery
10.2.1. Express
10.2.2. Non-Express
10.3. Market Analysis, Insights and Forecast - by Business Model
10.3.1. B2B
10.3.2. B2C
10.3.3. C2C
10.4. Market Analysis, Insights and Forecast - by Shipment Weight
10.4.1. Light Weight
10.4.2. Medium Weight
10.4.3. Heavy Weight
10.5. Market Analysis, Insights and Forecast - by Mode of Transport
10.5.1. Air
10.5.2. Road
10.5.3. Rail
10.5.4. Sea
10.6. Market Analysis, Insights and Forecast - by End-User Industry
10.6.1. E-Commerce
10.6.2. BFSI
10.6.3. Healthcare
10.6.4. Manufacturing
10.6.5. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Canada Post Corporation (including Purolator)
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. FedEx
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. UPS
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. TFI International Inc.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. DHL Group
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Amazon Logistics
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. InPost
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Penguin Pickup
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Canada Courier, Express, and Parcel (CEP) Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Destination 2026 & 2034
Figure 3: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Destination 2026 & 2034
Figure 4: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Speed of Delivery 2026 & 2034
Figure 5: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Speed of Delivery 2026 & 2034
Figure 6: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Business Model 2026 & 2034
Figure 7: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Business Model 2026 & 2034
Figure 8: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Shipment Weight 2026 & 2034
Figure 9: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Shipment Weight 2026 & 2034
Figure 10: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Mode of Transport 2026 & 2034
Figure 11: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Mode of Transport 2026 & 2034
Figure 12: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 13: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 14: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Country 2026 & 2034
Figure 15: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Destination 2026 & 2034
Figure 17: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Destination 2026 & 2034
Figure 18: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Speed of Delivery 2026 & 2034
Figure 19: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Speed of Delivery 2026 & 2034
Figure 20: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Business Model 2026 & 2034
Figure 21: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Business Model 2026 & 2034
Figure 22: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Shipment Weight 2026 & 2034
Figure 23: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Shipment Weight 2026 & 2034
Figure 24: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Mode of Transport 2026 & 2034
Figure 25: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Mode of Transport 2026 & 2034
Figure 26: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 27: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 28: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Country 2026 & 2034
Figure 29: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Country 2026 & 2034
Figure 30: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Destination 2026 & 2034
Figure 31: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Destination 2026 & 2034
Figure 32: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Speed of Delivery 2026 & 2034
Figure 33: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Speed of Delivery 2026 & 2034
Figure 34: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Business Model 2026 & 2034
Figure 35: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Business Model 2026 & 2034
Figure 36: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Shipment Weight 2026 & 2034
Figure 37: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Shipment Weight 2026 & 2034
Figure 38: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Mode of Transport 2026 & 2034
Figure 39: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Mode of Transport 2026 & 2034
Figure 40: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 41: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 42: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Country 2026 & 2034
Figure 43: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Country 2026 & 2034
Figure 44: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Destination 2026 & 2034
Figure 45: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Destination 2026 & 2034
Figure 46: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Speed of Delivery 2026 & 2034
Figure 47: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Speed of Delivery 2026 & 2034
Figure 48: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Business Model 2026 & 2034
Figure 49: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Business Model 2026 & 2034
Figure 50: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Shipment Weight 2026 & 2034
Figure 51: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Shipment Weight 2026 & 2034
Figure 52: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Mode of Transport 2026 & 2034
Figure 53: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Mode of Transport 2026 & 2034
Figure 54: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 55: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 56: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Country 2026 & 2034
Figure 57: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Country 2026 & 2034
Figure 58: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Destination 2026 & 2034
Figure 59: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Destination 2026 & 2034
Figure 60: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Speed of Delivery 2026 & 2034
Figure 61: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Speed of Delivery 2026 & 2034
Figure 62: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Business Model 2026 & 2034
Figure 63: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Business Model 2026 & 2034
Figure 64: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Shipment Weight 2026 & 2034
Figure 65: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Shipment Weight 2026 & 2034
Figure 66: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Mode of Transport 2026 & 2034
Figure 67: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Mode of Transport 2026 & 2034
Figure 68: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 69: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 70: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Country 2026 & 2034
Figure 71: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Destination 2020 & 2034
Table 2: Global Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Speed of Delivery 2020 & 2034
Table 3: Global Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Business Model 2020 & 2034
Table 4: Global Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Shipment Weight 2020 & 2034
Table 5: Global Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Mode of Transport 2020 & 2034
Table 6: Global Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 7: Global Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Destination 2020 & 2034
Table 9: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Speed of Delivery 2020 & 2034
Table 10: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Business Model 2020 & 2034
Table 11: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Shipment Weight 2020 & 2034
Table 12: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Mode of Transport 2020 & 2034
Table 13: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 14: Ontario Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Destination 2020 & 2034
Table 16: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Speed of Delivery 2020 & 2034
Table 17: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Business Model 2020 & 2034
Table 18: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Shipment Weight 2020 & 2034
Table 19: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Mode of Transport 2020 & 2034
Table 20: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 21: Quebec Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Country 2020 & 2034
Table 22: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Destination 2020 & 2034
Table 23: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Speed of Delivery 2020 & 2034
Table 24: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Business Model 2020 & 2034
Table 25: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Shipment Weight 2020 & 2034
Table 26: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Mode of Transport 2020 & 2034
Table 27: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 28: British Columbia Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Country 2020 & 2034
Table 29: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Destination 2020 & 2034
Table 30: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Speed of Delivery 2020 & 2034
Table 31: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Business Model 2020 & 2034
Table 32: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Shipment Weight 2020 & 2034
Table 33: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Mode of Transport 2020 & 2034
Table 34: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 35: Alberta Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Country 2020 & 2034
Table 36: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Destination 2020 & 2034
Table 37: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Speed of Delivery 2020 & 2034
Table 38: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Business Model 2020 & 2034
Table 39: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Shipment Weight 2020 & 2034
Table 40: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Mode of Transport 2020 & 2034
Table 41: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 42: Rest of Canada Canada Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1What is the current size of the Canada Courier, Express, and Parcel (CEP) market?
The Canada CEP market is valued at **USD 16.10 billion in 2026**, based on our proprietary primary research and expert interviews. This represents a steady growth from USD 15.37 billion in 2025.
2Which segment dominates the Canada CEP market by destination?
Domestic shipments lead with a **63.27% share** in 2025, reflecting the scale of intra-Canada trade. However, international parcels are growing faster at a **5.98% CAGR**, driven by cross-border e-commerce.
3Who are the major players in the Canada CEP market?
Key players include **Canada Post Corporation (including Purolator), FedEx, UPS, TFI International, and DHL Group**, which collectively hold a significant share of the market. UPS's acquisition of Andlauer Healthcare highlights a strategic move into healthcare logistics.
4What is the fastest-growing business model in the Canada CEP market?
The **C2C (consumer-to-consumer)** segment is growing at the fastest rate, with a **8.54% CAGR** from 2026 to 2031, fueled by peer-to-peer marketplaces and social commerce.
5What are the key drivers of the Canada CEP market?
Major drivers include the proliferation of **direct-to-consumer shipping models** (+1.4% CAGR impact), retailers' **sub-24-hour fulfillment commitments** (+1.1%), and the surge in **lightweight international parcels** under de minimis thresholds (+0.8%).
6Which region holds the largest share of the Canada CEP market?
**Ontario** leads with approximately **38%** of the market, driven by the Greater Toronto Area's dense e-commerce demand and robust B2B activity, followed by Quebec and British Columbia.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our research methodology is anchored in 70–80% primary research, involving direct engagement with industry stakeholders across the Canada CEP value chain. We conducted over 120 in-depth interviews with senior executives, including VPs of Logistics at major retailers, Directors of Last-Mile Operations at courier companies, Procurement Managers at e-commerce platforms, and Transportation Managers at healthcare shippers.
Interviews were supplemented by structured surveys with over 300 shippers and carriers, capturing granular data on shipment volumes, service-level preferences, and pricing dynamics.
Primary research also included on-site observations at sorting hubs, parcel locker installations, and urban delivery routes to validate operational metrics and cost structures.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VPs of Logistics and Supply Chain
30%
Directors of Last-Mile Operations
25%
Procurement and Sourcing Managers
20%
Chief Technology Officers (CTOs)
15%
Sustainability and Regulatory Affairs Managers
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Global Integrators (FedEx, UPS, DHL)
35%
National Postal Operators (Canada Post, Purolator)
25%
Regional Courier Companies
20%
E-commerce Logistics Arms (Amazon Logistics)
15%
Niche/Specialized Carriers
5%
Secondary Research & Industry Benchmarking
We triangulate primary findings with 20–30% secondary research, drawing from official multilateral and governmental sources such as Statistics Canada, UN Comtrade, World Bank, and the Canadian Transportation Agency. These sources provide authoritative trade data, e-commerce sales figures, and regulatory frameworks.
Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook are used to analyze company financials, investments, and M&A activities. We also reference recognized non-profit trade associations such as the Canadian Courier & Logistics Association (CCLA) and the International Post Corporation (IPC) for industry benchmarks.
All secondary sources are rigorously vetted for reliability and relevance, with a focus on data from the most recent available year (2024–2025).
Demand Modeling & Market Estimation
We employ a bottom-up approach to estimate market size, building from granular volume data. Specifically, we model parcel volumes by shipment weight class, business model, and end-user industry, applying average revenue per parcel (ARPP) derived from primary interviews.
Simultaneously, a top-down approach cross-checks the bottom-up results using macroeconomic indicators such as national e-commerce sales, GDP contribution of the transportation and warehousing sector, and CEP industry revenues reported by public carriers. Multi-level data triangulation ensures consistency between the two approaches.
Key quantitative metrics used in the demand model include total parcels shipped (units), average shipment weight (kg), revenue per parcel (USD), and delivery frequency per household. These metrics are validated through carrier-reported operational data and shipper surveys.
Data Accuracy & Quality Check
Our proprietary estimation framework guarantees an estimated data accuracy level of 85–90%, achieved through iterative validation and outlier detection.
Multi-level data triangulation is performed at the segment, regional, and company levels. Any discrepancies between primary and secondary data are resolved through follow-up interviews or re-weighting.
Every report is updated to the date of purchase, incorporating the latest market developments, regulatory changes, and company announcements to ensure stakeholders have access to real-time intelligence.