1What is the current size of the solid board packaging market?
The global solid board packaging market is valued at USD 2.97 billion in 2026 and is projected to reach USD 3.88 billion by 2035, growing at a CAGR of 3%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Solid Board Packaging Market
 by Board Type (Folding Boxboard (FBB), Recycled Solid Board, Solid Bleached Sulfate (SBS), Others), by Coating/Treatment (Virgin Coated, Recycled Coated, Barrier-Coated/Laminated, Uncoated), by Thickness/Grade (Medium Boards (250-400 gsm), Heavyweight Boards (>400 gsm), Lightweight Boards (<250 gsm)), by End-User (Food & Beverage Manufacturers, Ready-to-Eat/Convenience Food Companies, Retail/E-commerce, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, Japan, India, South Korea, Australia, Rest of Asia Pacific), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (UAE, Saudi Arabia, South Africa, Rest of MEA) Forecast 2026-2034
Research Associate


 Related Reports

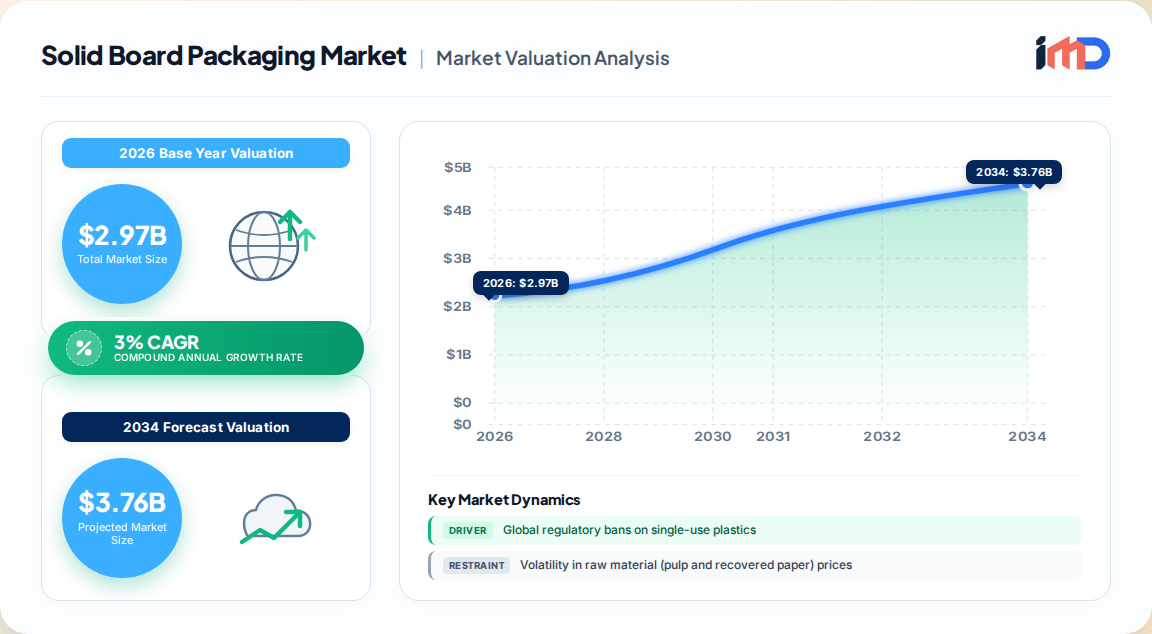
The global solid board packaging market represents a critical and rapidly evolving segment of the sustainable packaging industry. Our proprietary primary research estimates the market at USD 2.97 billion in 2026, projected to reach USD 3.88 billion by 2035, expanding at a steady CAGR of 3%. This growth is underpinned by a structural shift away from single-use plastics, driven by regulatory mandates and profound changes in consumer preference for recyclable, biodegradable, and food-safe packaging formats.
Solid board, characterized by its superior stiffness, printability, and barrier properties, is the material of choice for high-value folding cartons, premium food packaging, and robust e-commerce transit solutions. The market's trajectory is defined by a dual narrative: mature Western markets are focused on premiumization and barrier innovation, while the Asia-Pacific region is experiencing explosive volume growth fueled by urbanization, a burgeoning middle class, and the rapid expansion of modern retail and food delivery ecosystems.
The solid board packaging market is subject to a complex interplay of regulatory, economic, and technological forces. Our analysis identifies the following primary dynamics:
Market Drivers:
Market Restraints:
Key Trends:
The solid board packaging market is segmented by board type, coating/treatment, thickness/grade, and end-user. Our analysis reveals distinct growth patterns within each category.
| Segment | Type | Market Position (2026) | Fastest-Growing Sub-Segment |
|---|---|---|---|
| Board Type | Folding Boxboard (FBB), Recycled Solid Board, Solid Bleached Sulfate (SBS), Others | FBB dominates with the largest revenue share, favored for its strength and printability. | Recycled Solid Board is the fastest-growing, driven by cost and sustainability benefits. |
| Coating/Treatment | Virgin Coated, Recycled Coated, Barrier-Coated/Laminated, Uncoated | Virgin Coated boards hold the majority share due to superior aesthetics and food safety. | Barrier-Coated/Laminated boards are growing fastest, replacing plastic films in food packaging. |
| Thickness/Grade | Medium Boards (250–400 gsm), Heavyweight Boards (>400 gsm), Lightweight Boards (<250 gsm) | Medium Boards are the workhorse segment, ideal for folding cartons and general retail packaging. | Heavyweight Boards are gaining traction for premium and heavy-duty packaging applications. |
| End-User | Food & Beverage Manufacturers, Ready-to-Eat/Convenience Food Companies, Retail/E-commerce, Others | Food & Beverage manufacturers represent the largest end-user base. | Ready-to-Eat/Convenience Food companies are the fastest-growing end-user, driven by food delivery trends. |
The solid board packaging market exhibits significant regional variation in maturity, growth drivers, and competitive intensity.
Europe remains the dominant and most mature market, accounting for an estimated 34% of global revenue in 2026. The region's leadership is rooted in stringent environmental regulations, a highly developed recycling infrastructure, and a strong preference for premium, branded food products. Germany, the UK, and France are key markets, with a strong emphasis on circular economy solutions.
North America represents a substantial market, driven by a robust food processing industry, high per-capita packaging consumption, and the rapid expansion of e-commerce. The US market is characterized by a high degree of consolidation among converters and a strong focus on automation and digitalization.
Asia-Pacific is the fastest-growing region, projected to register a CAGR exceeding 4.5% through 2035. This growth is fueled by rapid urbanization, rising disposable incomes, the expansion of modern trade channels, and the proliferation of food delivery platforms in countries like China, India, and Southeast Asian nations. The region is also witnessing significant investment in new, state-of-the-art board mills and converting plants.
Latin America and Middle East & Africa are emerging markets with substantial long-term potential. Growth is driven by population expansion, increasing demand for packaged foods, and ongoing industry modernization, though infrastructure and political stability remain watch points.
The solid board packaging market is moderately consolidated, with global players and regional specialists competing on the basis of innovation, sustainability credentials, and supply chain reliability. Key players include integrated paper and board producers such as Smurfit Kappa, International Paper, Mondi Group, Stora Enso, and Graphic Packaging International. These companies are actively pursuing strategies to capitalize on the sustainability wave.
Recent Strategic Developments:
The global trade in solid board and its raw materials (wood pulp, recovered paper) is significant and highly dynamic. Official trade statistics from organizations such as Eurostat and UN Comtrade highlight the EU as a major net exporter of paper and board products, while Asia (particularly China) is a major importer of recovered paper and a growing exporter of finished packaging.
Key trade patterns influencing the solid board packaging market include:
Our analysis identifies several high-potential "white spaces" for innovation and investment in the solid board packaging market:
For brand owners and converters, a robust procurement strategy is essential to manage cost, risk, and sustainability goals.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3% from 2020-2034 |
| Segmentation |
|
By Coating/Treatment
By Thickness/Grade
By End-User
| By Geography |
|
The global solid board packaging market is valued at USD 2.97 billion in 2026 and is projected to reach USD 3.88 billion by 2035, growing at a CAGR of 3%.
Europe dominates the market, holding an estimated 34% share in 2026, driven by stringent sustainability regulations and a mature food and beverage industry.
The barrier-coated and laminated board segment is growing fastest, as it enables the replacement of plastic films and laminates in demanding food packaging applications.
Key players include Smurfit Kappa, International Paper, Mondi Group, Stora Enso, and Graphic Packaging International.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Procurement Officer | 30% |
| Sustainability Manager | 25% |
| Head of Packaging Development | 25% |
| Supply Chain Director | 20% |
| Company Type | Representation (%) |
|---|---|
| Paper & Board Mills | 35% |
| Packaging Converters | 30% |
| Brand Owners & Retailers | 20% |
| Coatings & Additives Suppliers | 15% |