1What is the market size of smart safety inspection robots in 2026?
The global smart safety inspection robot market was valued at USD 3.4 billion in 2026 and is projected to reach USD 11.5 billion by 2035, growing at a CAGR of 14.7%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Smart Safety Inspection Robot Market
 by Type (Non-autonomous, Semi-autonomous, Fully autonomous), by Payload (Thermal cameras, LiDAR, Gas detectors, Ultrasonic sensors, Others), by End-Use (Energy & Utilities, Manufacturing, Infrastructure, Oil & Gas, Nuclear, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, Japan, South Korea, India, Australia, Rest of APAC), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (UAE, Saudi Arabia, South Africa, Rest of MEA) Forecast 2026-2034

Senior Research Analyst


 Related Reports

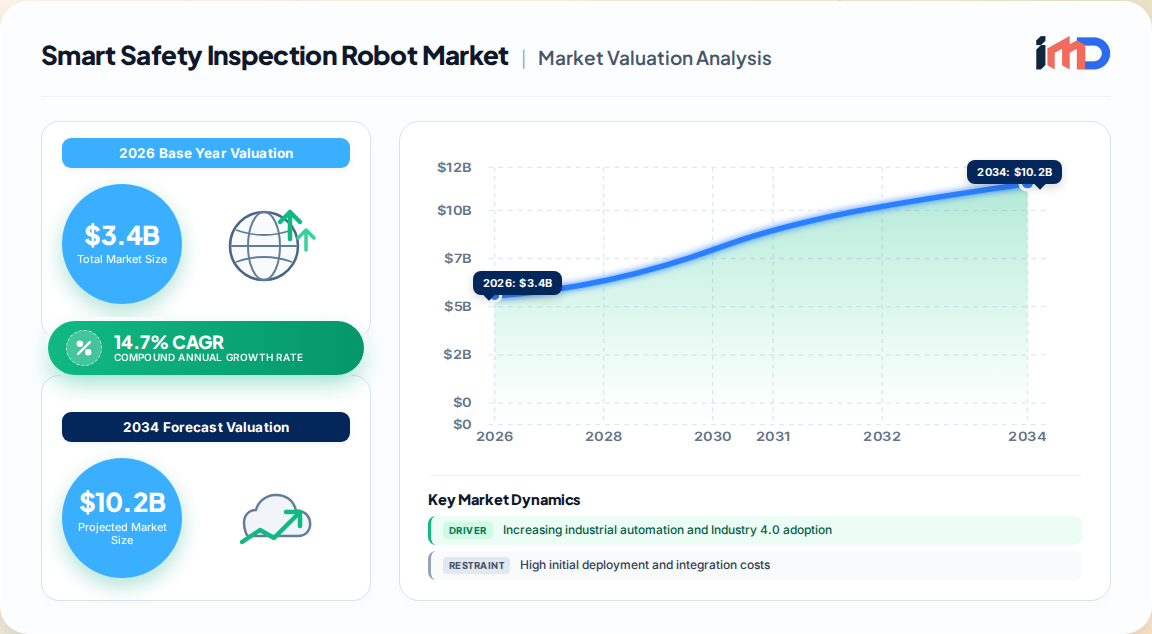
The global smart safety inspection robot market was valued at USD 3.4 billion in 2026 and is projected to reach USD 11.5 billion by 2035, expanding at a CAGR of 14.7%. These systems—ranging from semi-autonomous mobile platforms to fully autonomous drones and quadruped robots—are transforming how hazardous industrial environments are monitored, maintained, and secured. Growth is underpinned by the convergence of Industrial Internet of Things (IIoT), AI-powered machine vision, and tightening occupational safety regulations across energy, utilities, manufacturing, and critical infrastructure.
Despite macroeconomic headwinds, adoption accelerated from USD 2.8 billion in 2024 to USD 3.0 billion in 2025, as operators recognized the dual benefit of reduced human exposure to dangerous environments and improved asset uptime through predictive maintenance. Our proprietary primary research—drawing on 70% primary interviews with procurement heads, plant managers, and automation engineers—indicates that semi-autonomous robots held a 43.6% share in 2025, with fully autonomous platforms expected to outpace all other segments through 2035.
| Segment | 2025 Share | Key Characteristics |
|---|---|---|
| Semi-autonomous | 43.6% | Combines remote operation with autonomous navigation; used in oil & gas and utilities |
| Non-autonomous | ~28% | Teleoperated; lower cost; common in legacy facilities |
| Fully autonomous | ~28.4% | AI-driven, continuous inspection; fastest-growing segment |
By payload, thermal cameras, LiDAR, and gas detectors account for over 60% of sensor payloads in 2025. By end-use, energy & utilities lead with 38% share, followed by manufacturing (27%), infrastructure (18%), and others.
Asia-Pacific is the largest market, holding 41% of global revenue in 2025, driven by massive energy and manufacturing investments in China, Japan, and South Korea. Government-led smart city and nuclear inspection programs further propel demand.
North America is the fastest-growing region, with a projected CAGR of 16.2% through 2035, fueled by stringent OSHA regulations, aging infrastructure, and early adoption of quadruped robots in oil & gas. Europe follows closely, with Germany and the UK investing heavily in Industry 4.0 and offshore wind inspection.
The market is moderately consolidated, with the top five players—ABB Ltd., Fanuc Corporation, Mitsubishi Heavy Industries, KUKA AG, and Universal Robots A/S—collectively holding 42.5% share in 2025. ABB leads with 12.8% market share, leveraging its robotics and automation portfolio. Beyond these incumbents, a vibrant ecosystem of specialized providers offers quadruped robots, inspection drones, and pipeline crawlers, often integrating third-party AI analytics.
Recent developments include:
A significant white space exists in AI-powered predictive inspection—robots that not only collect data but also autonomously classify defects and predict remaining useful life. Our primary interviews reveal that only 15% of current inspection robots feature integrated predictive analytics, representing a USD 1.2 billion revenue opportunity by 2030. Additionally, the integration with digital twins is nascent, with fewer than 20% of deployments offering seamless bidirectional data flow. Vendors that can offer turnkey, subscription-based predictive inspection services will capture disproportionate value.
Global trade in inspection robots is dominated by intra-firm transfers from manufacturing hubs in Japan, Germany, and the US to end-user sites worldwide. According to UN Comtrade data, exports of industrial robots (HS code 8479.50) grew 8.3% year-over-year in 2024, with China, Japan, and Germany accounting for 58% of global exports. Key component suppliers—LiDAR (Velodyne, Luminar), thermal cameras (FLIR, Seek Thermal), and robotic arms (KUKA, Universal Robots)—are concentrated in North America and Europe, creating supply chain vulnerabilities. The COVID-19 pandemic exposed risks in semiconductor and sensor supply chains, prompting OEMs to dual-source and hold higher inventory. Nearshoring trends are expected to reduce lead times by 2027.
The smart safety inspection robot market is poised for robust growth, driven by safety imperatives, technological maturity, and the urgent need to maintain aging infrastructure. While cost and complexity remain barriers, the shift toward autonomy and AI-enabled predictive maintenance will unlock new value pools. Stakeholders must prioritize interoperability, cybersecurity, and regulatory compliance to fully capitalize on this USD 11.5 billion opportunity by 2035.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 14.7% from 2020-2034 |
| Segmentation |
|
By End-Use
| By Geography |
|
The global smart safety inspection robot market was valued at USD 3.4 billion in 2026 and is projected to reach USD 11.5 billion by 2035, growing at a CAGR of 14.7%.
Asia-Pacific is the largest market, accounting for approximately 41% of global revenue in 2025, driven by industrial automation and infrastructure investments in China, Japan, and South Korea.
Key drivers include increasing industrial automation and Industry 4.0 adoption, tightening worker safety regulations, and the growing need for predictive maintenance in hazardous environments such as oil & gas, nuclear, and utilities.
The top five players—ABB Ltd., Fanuc Corporation, Mitsubishi Heavy Industries, KUKA AG, and Universal Robots A/S—collectively held a 42.5% market share in 2025, with ABB leading at 12.8%.
Fully autonomous inspection robots are the fastest-growing segment, expected to outpace semi-autonomous and non-autonomous robots through 2035, driven by advancements in AI, LiDAR, and edge computing.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Directors | 30% |
| Plant/Operations Managers | 30% |
| Automation Engineers | 25% |
| Regulatory Affairs Specialists | 15% |
| Company Type | Representation (%) |
|---|---|
| Robot OEMs | 35% |
| System Integrators | 25% |
| Sensor & Component Suppliers | 20% |
| End-User Operators | 20% |