1What is the size of the Algeria telecom market in 2026?
The Algeria telecom market is valued at USD 2.73 billion in 2026, up from USD 2.68 billion in 2025. It is projected to reach USD 2.97 billion by 2031, growing at a CAGR of 1.75%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Algeria Telecom Market
 by Service Type (Voice Services, Data and Internet Services, Messaging Services, IoT and M2M Services, OTT and PayTV Services, Other Services), by End User (Enterprises, Consumers), by North-Central Algeria (Algiers, Blida, Boumerdès), by Western Algeria (Oran, Tlemcen), by Eastern Algeria (Constantine, Annaba), by High Plateaus, by Southern Algeria Forecast 2026-2034

Senior Research Analyst


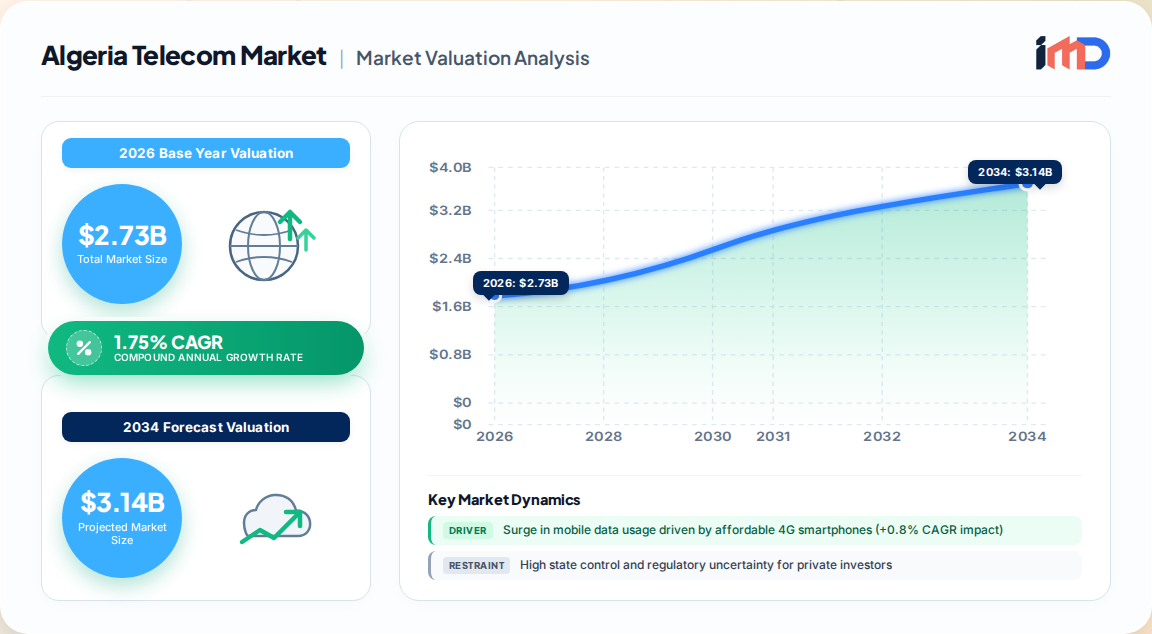
The Algeria telecom market is valued at USD 2.73 billion in 2026, up from USD 2.68 billion in 2025, and is projected to reach USD 2.97 billion by 2031, expanding at a CAGR of 1.75%. This measured growth reflects a market in transition: legacy voice and SMS revenue is contracting while data, broadband, and enterprise connectivity services accelerate.
Algeria's digital foundation is substantial. The country hosts 54.8 million mobile connections — a 116% SIM-per-capita ratio — and 36 million mobile internet users, translating to a 77% penetration rate. Fixed broadband is anchored by 1.8 million fiber subscribers, the largest FTTH base in North Africa, with residential speeds reaching 1.2 Gbps. These metrics position Algeria as a volume-rich but monetization-constrained market where multi-SIM behavior and prepaid dominance continue to suppress ARPU.
The Algerian telecom market's expansion is driven by several reinforcing forces, each with distinct impact profiles.
| Driver | Estimated CAGR Impact | Geographic Relevance | Timeline |
|---|---|---|---|
| Surge in mobile data usage from affordable 4G smartphones | +0.8% | National; early gains in Algiers, Oran, Constantine | Medium term (2–4 years) |
| Government-led FTTH rollout and wholesale fiber backbone | +0.4% | National; concentrated in urban centers | Long term (≥4 years) |
| Upcoming 5G spectrum auctions unlocking enterprise FWA | +0.3% | National; initial focus on major cities | Medium term (2–4 years) |
| Rapid digitization of public services and mobile payments | +0.2% | National; public administration and banking | Short term (≤2 years) |
| Cross-border fiber corridors opening wholesale revenue | +0.1% | Border regions and international gateways | Long term (≥4 years) |
| Rising IoT demand from oil and gas telemetry | +0.1% | Southern Algeria; oil and gas basins | Medium term (2–4 years) |
Mobile data consumption is the single largest growth contributor. Operators are refarming 1,800 MHz and 2,100 MHz spectrum and densifying networks to accommodate traffic shifts from voice to data. Prepaid bundles with aggressive data allowances are stimulating usage, though monetization lags because ARPU remains under pressure.
Government-led FTTH and wholesale fiber programs are reducing last-mile bottlenecks. Algeria Telecom's wholesale backbone links provincial capitals and supports metro rings, enabling private ISPs to lease capacity. The migration from copper to fiber is lowering churn and enabling upselling to higher speed tiers.
5G spectrum auctions represent a medium-term catalyst. The regulatory authority opened bidding in June 2025 for the 3.5 GHz and 26 GHz bands, structuring licenses to favor rapid service-launch commitments. Pilots by Djezzy and Ooredoo concentrate on campus-style deployments, industrial IoT, and business-park fixed-wireless access. However, high spectrum fees and hard-currency shortages mean mass-market consumer 5G is unlikely before 2027; early uptake will hinge on enterprise demand.
Several structural constraints temper the market's growth trajectory, with the most significant being institutional rather than demand-side.
| Restraint | Estimated CAGR Impact | Geographic Relevance | Timeline |
|---|---|---|---|
| High state control and regulatory uncertainty for private investors | -0.8% | National; capital-intensive segments | Long term (≥4 years) |
| Currency-convertibility limits inflating network-equipment CAPEX | -0.4% | National; network procurement | Medium term (2–4 years) |
| Diesel-based power-supply volatility impacting rural towers | -0.2% | Rural and remote regions | Short term (≤2 years) |
| Scarcity of neutral data centers inflating domestic backhaul costs | -0.2% | Urban enterprise districts | Medium term (2–4 years) |
State control is the dominant restraint. Dominant ownership of backbone assets by Mobilis and Algeria Telecom, coupled with opaque licensing timelines, fuels investor caution. The 2022 nationalization of Djezzy crystallized perceptions that foreign equity can be diluted, prompting cost-of-capital premiums and reducing appetite for greenfield ventures.
Currency-convertibility limits require central-bank approvals for hard-currency purchases, stretching procurement cycles for 4G and 5G radios. Suppliers demand euro- or U.S.-dollar terms, and delays inflate equipment costs and slow rollout timelines.
By service type, data and internet services captured 53.86% of market share in 2025, making it the dominant revenue pool. Voice services remain significant but are declining as a share of total revenue. IoT and M2M services are advancing at a 1.86% CAGR through 2031, albeit from a small base, driven by oil and gas telemetry and smart metering.
| Service Type | 2025 Share | Growth Outlook (CAGR to 2031) |
|---|---|---|
| Data and Internet Services | 53.86% | Moderate (above market average) |
| Voice Services | Declining share | Contracting |
| Messaging Services | Declining share | Contracting |
| IoT and M2M Services | Small base | 1.86% |
| OTT and PayTV Services | Emerging | Growing |
| Other Services | Residual | Stable |
By end user, the consumer segment commanded 85.02% of market size in 2025, reflecting the mass-market nature of mobile and fixed broadband. However, the enterprise segment is projected to grow at a 2.46% CAGR to 2031, outpacing consumer growth and signaling a gradual shift toward B2B connectivity, IoT, and managed services.
The Algeria telecom market exhibits high concentration, with three mobile network operators dominating: Mobilis, Djezzy, and Ooredoo Algeria. Competitive positioning is shaped more by state influence than pure market forces.
The market is semi-consolidated, with moderate players holding significant shares. Recent strategic developments include:
Algeria's telecom market activity is concentrated in the north, where population density and economic activity are highest.
| Region | Estimated Share of Telecom Activity | Key Characteristics |
|---|---|---|
| North-Central Algeria (Algiers, Blida, Boumerdès) | ~61% | Highest population density; enterprise demand; fiber and 5G pilots |
| Western Algeria (Oran, Tlemcen) | ~18% | Fastest-growing region; ORVAL submarine cable landing; AI compute center |
| Eastern Algeria (Constantine, Annaba) | ~12% | Industrial corridors; growing fiber penetration |
| High Plateaus | ~5% | Rural coverage challenges; diesel-dependent towers |
| Southern Algeria | ~4% | Oil and gas telemetry; low-density coverage |
The Western region is the fastest-growing, driven by the Oran-Valencia (ORVAL) submarine cable landing and the development of a GPU computing center in Oran. The North-Central region remains the largest hub, accounting for the majority of enterprise and government connectivity spend.
Despite structural constraints, several high-value opportunities are emerging for operators and investors.
Wholesale fiber corridors represent a strategic opportunity. Algeria's extensive 200,000 km fiber optic network, including SEA-ME-WE 4, Medex, Orval, and a government-backed fourth cable, positions the nation as a potential regional transit hub. Cross-border fiber corridors could open new wholesale revenue streams, particularly with European and sub-Saharan partners.
Enterprise 5G fixed-wireless access is a near-term opportunity as spectrum auctions conclude. Early deployments will target manufacturing, logistics, and energy corridors, where low-latency connectivity commands premium pricing.
Oil and gas telemetry in the Sahara fields is a niche but growing IoT opportunity. Rising demand for remote monitoring and predictive maintenance creates a recurring revenue stream with high switching costs.
Data center co-location is a complementary opportunity. Algeria's data center market is forecast to grow at a 17.36% CAGR from 2025 to 2035, reaching USD 1.14 billion by 2035, driven by sovereign hosting requirements and AI compute demand. Telecom operators that integrate colocation with connectivity services can capture higher wallet share.
The Algeria telecom value chain spans network infrastructure, service provisioning, and end-user distribution.
Network infrastructure is dominated by state-controlled entities for fixed backhaul and wholesale fiber, with private operators owning mobile radio access networks. Equipment procurement is constrained by currency-convertibility rules, which extend lead times for 4G and 5G radios. Key vendors include Huawei, Ericsson, Nokia, ZTE, Cisco, Ciena, and Juniper Networks.
Service provisioning is concentrated among the three MNOs, with private ISPs leasing wholesale capacity for fixed broadband. Mobile virtual network operators (MVNOs) have limited presence, and the regulatory framework for MVNO licensing remains nascent.
Distribution is heavily prepaid-oriented, with operators relying on a network of retail agents and electronic top-up channels. Mobile payment ecosystems are growing, supported by partnerships with fintechs and banks, and Algeria Telecom's incentive of up to 30 days of free data for electronic payment of internet top-ups exemplifies how telcos align with national digitalization targets.
Supply chain risks include diesel-based power volatility for rural towers, which raises operating costs and complicates network expansion. Scarcity of neutral data centers inflates domestic backhaul costs, discouraging the growth of a neutral interconnection ecosystem and keeping transit costs elevated.
To navigate the Algeria telecom market's measured growth trajectory, stakeholders should prioritize:
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 1.75% from 2020-2034 |
| Segmentation |
|
By End User
| By Geography |
|
The Algeria telecom market is valued at USD 2.73 billion in 2026, up from USD 2.68 billion in 2025. It is projected to reach USD 2.97 billion by 2031, growing at a CAGR of 1.75%.
Data and internet services captured 53.86% of the Algeria telecom market share in 2025, making it the dominant service type. Voice and messaging services continue to decline as a share of total revenue.
The major mobile network operators in Algeria are Mobilis, Djezzy, and Ooredoo Algeria. Mobilis leads on coverage, Djezzy excels in dense metros, and Ooredoo focuses on operational efficiency.
The enterprise segment is projected to grow at a 2.46% CAGR to 2031, outpacing consumer growth. Enterprise demand for IoT, 5G fixed-wireless access, and oil and gas telemetry presents high-value recurring revenue opportunities.
Growth is driven by a surge in mobile data usage from affordable 4G smartphones (+0.8% CAGR impact), government-led FTTH rollout (+0.4%), and upcoming 5G spectrum auctions (+0.3%). Rapid digitization of public services and mobile payments also contributes.
High state control and regulatory uncertainty for private investors (-0.8% CAGR impact) and currency-convertibility limits inflating network-equipment CAPEX (-0.4%) are the most significant restraints. Diesel-based power volatility in rural areas also impacts operations.
Algeria has 1.8 million fiber subscribers, the largest FTTH base in North Africa, offering residential speeds up to 1.2 Gbps. Government-led FTTH rollout and wholesale fiber backbone projects are expected to drive further adoption.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Technology Officer (CTO) | 30% |
| VP of Network Strategy | 25% |
| Head of Regulatory Affairs | 25% |
| Procurement Director | 20% |
| Company Type | Representation (%) |
|---|---|
| Mobile Network Operators (MNOs) | 30% |
| Telecom Equipment Vendors | 25% |
| Fixed-Line and Broadband Providers | 20% |
| Enterprise Connectivity Buyers | 15% |
| Wholesale Fiber and Infrastructure Operators | 10% |
 Related Reports
