Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Morocco Telecom Market by Service Type (Voice Services, Data and Internet Services, Messaging Services, IoT and M2M Services, OTT and PayTV Services, Other Services), by End User (Enterprises, Consumer), by Urban Centers (Casablanca, Rabat, Marrakech), by Rural Areas, by Industrial Zones (Tangier, Kenitra) Forecast 2026-2034
Executive Overview: A Maturing Market Shifting from Subscriber Growth to Value Optimization
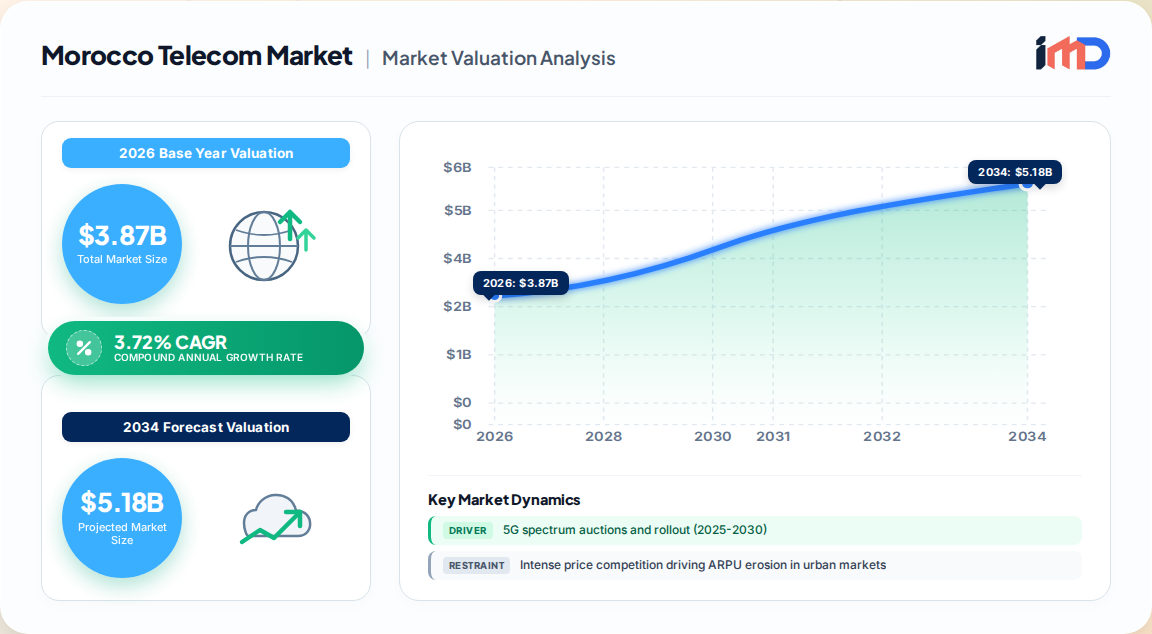
The Morocco telecom market has entered a decisive maturation phase, characterized by near-parity competition among three mobile network operators (MNOs) and a strategic pivot from headline subscriber additions toward revenue optimization through 5G-enabled services, fiber backhaul, and enterprise-grade solutions. Our proprietary primary research estimates the market at USD 3.87 billion in 2026, forecast to reach USD 4.64 billion by 2031, expanding at a CAGR of 3.72% over the forecast period (2026–2031). In volume terms, the subscriber base is projected to grow from 62.92 million in 2026 to 75.16 million by 2031, at a CAGR of 3.62%.
Morocco Telecom Market Market Size (In Billion)
5.0B
4.0B
3.0B
2.0B
1.0B
0
3.731 B
2025
3.870 B
2026
4.014 B
2027
4.163 B
2028
4.318 B
2029
4.479 B
2030
4.645 B
2031
This expansion reflects a fundamental structural shift. Network modernization, strategic infrastructure-sharing ventures, and the government's sweeping "Digital Morocco 2030" fiber program are reshaping operator strategies. Meanwhile, near-parity market shares among Inwi, Maroc Telecom, and Orange Maroc have created an aggressive pricing environment that compresses margins and intensifies regulatory scrutiny. Sizable anticompetitive penalties and mandatory local-loop unbundling are pushing incumbents to collaborate on neutral FiberCo and TowerCo vehicles to cut capital outlays.
Market Concentration: High, dominated by three operators with near-equal shares.
Data Revenue Dominance: Data and internet services led with 50.02% of market share in 2025.
Consumer Segment: Accounted for 86.95% of market size in 2025; enterprise is the faster-growing segment.
Regulatory Intensity: ANRT enforcement and infrastructure-sharing mandates are redefining competitive dynamics.
Key Market Drivers and Restraints Shaping the 2026–2031 Outlook
Drivers
5G Spectrum Auctions and Rollout (2025–2030): The scheduled November 2025 auction for 3.5 GHz and 700 MHz licenses represents a strategic inflection point. We forecast 5G coverage to reach 25% of the population by 2026 and 70% by 2030, creating capacity for industrial IoT, smart-city platforms, and immersive consumer applications. This driver alone contributes an estimated +1.2% impact on CAGR, concentrated in Casablanca, Rabat, and Marrakech.
Surging Mobile Data Consumption Among Youth: Roughly two-thirds of Morocco's 38 million citizens are under 30, and this cohort accounts for 78% of total mobile data traffic. Unlimited social-media bundles and video-streaming add-ons now comprise 41% of prepaid ARPU, contributing a +0.8% impact on CAGR in urban centers nationwide.
Government "Digital Morocco 2030" Fiber Investment Program: Targeting 5.6 million household fiber links by 2030—more than doubling the existing 2.5 million fixed-broadband lines recorded in September 2024—this program adds a +0.6% impact on CAGR, primarily benefiting rural and underserved areas over the long term.
Urban Uptake of Converged Quad-Play Bundles: Primary and secondary cities are seeing accelerating adoption of bundled voice, data, TV, and IoT offerings, contributing +0.4% to CAGR.
Enterprise Demand for Private LTE/5G at Industrial Zones: Clusters around Tangier, Casablanca, and Kenitra are driving demand for private networks, adding +0.3% to CAGR.
Near-Shoring FDI Boosting International Wholesale Traffic: Coastal data-center hubs are benefiting from Morocco's emergence as a cross-Mediterranean supply-chain hub, contributing +0.2% to CAGR over the long term.
Restraints
Intense Price Competition Driving ARPU Erosion: Near-parity market shares among the three MNOs have created an aggressive pricing environment, particularly in urban markets, exerting a -0.9% drag on CAGR in the short term.
Heavy Regulatory Fines and Compliance Costs on Incumbents: ANRT's enforcement actions and mandatory local-loop unbundling impose significant compliance costs, adding -0.6% to the negative pressure on incumbent margins.
OTT Substitution for Voice and Messaging: Traditional voice and SMS revenue fell 8% year-on-year in 2024, and this structural decline continues to restrain legacy revenue streams.
Fixed Infrastructure Monopoly: The incumbent's strategic dominance over fixed infrastructure, reinforced by local-loop access tariffs that have failed to incentivize technological transition, limits competitive fixed-broadband expansion.
Segment Analysis: Data and Enterprise Lead Growth
By Service Type
Service Type
2025 Share (%)
Growth Outlook (CAGR)
Data and Internet Services
50.02
Stable, driven by mobile data and fixed broadband
Voice Services
Declining
-8% YoY revenue decline in 2024
Messaging Services
Declining
OTT substitution pressure
IoT and M2M Services
Emerging
3.84% CAGR to 2031
OTT and PayTV Services
Growing
Moderate growth
Other Services
Niche
Stable
Data and internet services led the market with 50.02% share in 2025, underpinned by mobile internet dominance (representing about 93.09% of total internet subscriptions) and the accelerating fiber rollout. IoT and M2M services represent the fastest-growing sub-segment at 3.84% CAGR, driven by smart metering, asset tracking, and predictive maintenance applications.
By End User
End User
2025 Share (%)
Growth Outlook (CAGR)
Consumer
86.95
Moderate, driven by data and bundled services
Enterprise
13.05
4.43% CAGR through 2031
The consumer segment remains the dominant revenue contributor, but the enterprise segment is the standout growth engine, projected to expand at 4.43% CAGR through 2031. Private LTE/5G networks in industrial parks, SD-WAN, MEC, cloud orchestration, and cybersecurity offerings are transforming the revenue mix. The April 2025 Vodafone–Maroc Telecom memorandum of understanding—bundling these services into a single SLA-backed offering for automotive, logistics, and aerospace plants—exemplifies this pivot.
Competitive Landscape: Near-Parity Competition and Infrastructure Collaboration
The Morocco telecom market is highly concentrated, with three operators holding near-equal shares:
Operator
Estimated Market Share (2024)
Strategic Positioning
Maroc Telecom
36.1%
Largest player; wide service range; consolidated revenue of USD 3.67 billion in 2024; regional footprint across 10 African countries with over 75 million customers
Orange Maroc (Méditel)
32.9%
Strong competitor; aggressive fiber and 5G positioning
Inwi (Wana Corporate S.A.)
31.0%
Active in mobile, fixed, and internet segments; joint TowerCo venture with Maroc Telecom
The near-parity structure creates an aggressive pricing environment that compresses margins. In response, operators are collaborating on neutral FiberCo and TowerCo vehicles to cut capital outlays. The Maroc Telecom–Inwi TowerCo joint venture illustrates how carriers pool passive assets to support faster rollout while protecting cash flow. Capital intensity is anticipated to decline by nearly 200 basis points from 2024 levels, lifting free cash that can be redirected toward enterprise service development and customer-experience tools.
Regional Outlook: Urban Concentration and Rural Inclusion
Market activity is heavily concentrated in urban centers, which account for an estimated 62% of telecom revenue, led by Casablanca, Rabat, and Marrakech. These cities are the first targets for 5G rollout, with stadiums, fan zones, hotels, and airports prioritized for the December 2025 AFCON event. Industrial zones around Tangier, Casablanca, and Kenitra represent a growing 14% share of revenue, driven by enterprise demand for private LTE/5G. Rural areas, while contributing a smaller share, are the focus of the government's fiber program and a new initiative to improve internet access in 1,800 rural communities, ensuring an inclusive digital transition and bridging the urban-rural digital divide.
Morocco Telecom Market Regional Market Share
Loading chart...
Value Chain and Infrastructure Dynamics
The telecom value chain in Morocco is undergoing significant transformation:
Network Infrastructure: Fiber backhaul and 5G RAN deployment are accelerating, supported by Nokia's innovation centers supplying local operators with advanced radio and core solutions.
Infrastructure Sharing: ANRT rules oblige infrastructure sharing, opening premium spectrum bands to smaller licensees and curbing redundant deployment costs. Joint ventures such as the Maroc Telecom–Inwi TowerCo pool passive assets.
Service Enablement: Operators are moving up the value chain into SD-WAN, MEC, cloud orchestration, and cybersecurity, particularly for enterprise customers.
Content and OTT: Partnerships with local e-learning and fintech platforms embed operator brands into youth digital lifestyles, contributing incremental service revenue.
Median nationwide upload speeds reached 31.86 Mbps in early 2025—the highest in North Africa—meeting the latency and symmetry requirements of data-center colocation, cloud migration, and advanced analytics workloads. This infrastructure quality is a critical enabler for enterprise digital transformation and Morocco's ambition to become a leading digital hub in Africa.
Strategic White-Space Analysis
Several high-potential white spaces emerge from our analysis:
Enterprise Private 5G: The industrial zones of Tangier Med and Casablanca free-trade zones represent a largely untapped market for private LTE/5G, with RedCap chipsets lowering the total cost of ownership for asset tracking, smart metering, and predictive-maintenance solutions.
Fixed Broadband Fiber: With fixed internet accounting for only 6.59% of total internet subscriptions, the fiber rollout under Digital Morocco 2030 presents a significant growth opportunity, particularly as median upload speeds already meet data-center requirements.
IoT and M2M: The projected 3.84% CAGR for IoT and M2M services signals growing demand in smart metering, asset tracking, and smart-city platforms.
Wholesale and Data-Center Interconnect: Near-shoring FDI and Morocco's emergence as a cross-Mediterranean supply-chain hub create opportunities in wholesale IP transit, multi-cloud interconnect, and managed security offerings.
Recent Industry Developments
November 2025: 5G spectrum auction for 3.5 GHz and 700 MHz bands, expected to accelerate coverage to 25% of the population by 2026 and 70% by 2030.
April 2025: Vodafone–Maroc Telecom memorandum of understanding to bundle SD-WAN, MEC, cloud orchestration, and cybersecurity into a single SLA-backed offering for automotive, logistics, and aerospace plants.
2024: ANRT reports 4G mobile subscribers increased by more than 30% to approximately 20.5 million.
September 2024: Fixed-broadband lines reached 2.5 million, with Digital Morocco 2030 targeting 5.6 million household fiber links by 2030.
2025: All three telecom operators successfully completed 5G pilot tests and stand ready to deploy their own 5G networks.
Morocco Telecom Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Morocco Telecom Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3.72% from 2020-2034
Segmentation
By Service Type
Voice Services
Data and Internet Services
Messaging Services
IoT and M2M Services
OTT and PayTV Services
Other Services
By End User
Enterprises
Consumer
By Geography
Urban Centers
Casablanca
Rabat
Marrakech
Rural Areas
Industrial Zones
Tangier
Kenitra
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. 5G spectrum auctions and rollout (2025-2030)
3.1.2. Surging mobile data consumption among youth population
3.1.3. Government Digital Morocco 2030 fiber investment program
3.1.4. Urban uptake of converged quad-play bundles
3.1.5. Enterprise demand for private LTE/5G at industrial zones
3.2. Market Trends
3.2.1. 5G spectrum auctions and rollout accelerating coverage to 25% by 2026 and 70% by 2030
3.2.2. Youth-driven data consumption with under-30 cohort accounting for 78% of mobile data traffic
3.2.3. Digital Morocco 2030 fiber program targeting 5.6 million household links by 2030
3.2.4. Enterprise demand for private LTE/5G at industrial zones transforming revenue mix
3.3. Market Restrains
3.3.1. Intense price competition driving ARPU erosion in urban markets
3.3.2. Heavy regulatory fines and compliance costs on incumbents
3.3.3. OTT substitution for voice and messaging eroding legacy revenues
3.5.2. Mandatory local-loop unbundling and infrastructure-sharing mandates
3.5.3. Declining traditional voice and SMS revenue (8% YoY decline in 2024)
3.5.4. Bridging the urban-rural digital divide
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Service Type
5.1.1. Voice Services
5.1.2. Data and Internet Services
5.1.3. Messaging Services
5.1.4. IoT and M2M Services
5.1.5. OTT and PayTV Services
5.1.6. Other Services
5.2. Market Analysis, Insights and Forecast - by End User
5.2.1. Enterprises
5.2.2. Consumer
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. Urban Centers
5.3.2. Rural Areas
5.3.3. Industrial Zones
6. Urban Centers Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Service Type
6.1.1. Voice Services
6.1.2. Data and Internet Services
6.1.3. Messaging Services
6.1.4. IoT and M2M Services
6.1.5. OTT and PayTV Services
6.1.6. Other Services
6.2. Market Analysis, Insights and Forecast - by End User
6.2.1. Enterprises
6.2.2. Consumer
7. Rural Areas Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Service Type
7.1.1. Voice Services
7.1.2. Data and Internet Services
7.1.3. Messaging Services
7.1.4. IoT and M2M Services
7.1.5. OTT and PayTV Services
7.1.6. Other Services
7.2. Market Analysis, Insights and Forecast - by End User
7.2.1. Enterprises
7.2.2. Consumer
8. Industrial Zones Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Service Type
8.1.1. Voice Services
8.1.2. Data and Internet Services
8.1.3. Messaging Services
8.1.4. IoT and M2M Services
8.1.5. OTT and PayTV Services
8.1.6. Other Services
8.2. Market Analysis, Insights and Forecast - by End User
8.2.1. Enterprises
8.2.2. Consumer
9. Competitive Analysis
9.1. Company Profiles
9.1.1. Maroc Telecom
9.1.1.1. Company Overview
9.1.1.2. Products
9.1.1.3. Company Financials
9.1.1.4. SWOT Analysis
9.1.2. Orange Maroc (Méditel)
9.1.2.1. Company Overview
9.1.2.2. Products
9.1.2.3. Company Financials
9.1.2.4. SWOT Analysis
9.1.3. Inwi (Wana Corporate S.A.)
9.1.3.1. Company Overview
9.1.3.2. Products
9.1.3.3. Company Financials
9.1.3.4. SWOT Analysis
9.1.4. Vodafone
9.1.4.1. Company Overview
9.1.4.2. Products
9.1.4.3. Company Financials
9.1.4.4. SWOT Analysis
9.1.5. Nokia
9.1.5.1. Company Overview
9.1.5.2. Products
9.1.5.3. Company Financials
9.1.5.4. SWOT Analysis
9.2. Market Entropy
9.2.1. Company's Key Areas Served
9.2.2. Recent Developments
9.3. Company Market Share Analysis, 2026
9.3.1. Top 5 Companies Market Share Analysis
9.3.2. Top 3 Companies Market Share Analysis
9.4. List of Potential Customers
List of Figures
Figure 1: Global Morocco Telecom Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Global Morocco Telecom Market Volume Breakdown (Subscribers, %) by Region 2026 & 2034
Figure 3: Urban Centers Morocco Telecom Market Revenue (Billion), by Service Type 2026 & 2034
Figure 4: Urban Centers Morocco Telecom Market Volume (Subscribers), by Service Type 2026 & 2034
Figure 5: Urban Centers Morocco Telecom Market Revenue Share (%), by Service Type 2026 & 2034
Figure 6: Urban Centers Morocco Telecom Market Volume Share (%), by Service Type 2026 & 2034
Figure 7: Urban Centers Morocco Telecom Market Revenue (Billion), by End User 2026 & 2034
Figure 8: Urban Centers Morocco Telecom Market Volume (Subscribers), by End User 2026 & 2034
Figure 9: Urban Centers Morocco Telecom Market Revenue Share (%), by End User 2026 & 2034
Urban Centers Morocco Telecom Market Volume Share (%), by End User 2026 & 2034
List of Tables
Table 1: Global Morocco Telecom Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 2: Global Morocco Telecom Market Volume Subscribers Forecast, by Service Type 2020 & 2034
Table 3: Global Morocco Telecom Market Revenue Billion Forecast, by End User 2020 & 2034
Table 4: Global Morocco Telecom Market Volume Subscribers Forecast, by End User 2020 & 2034
Table 5: Global Morocco Telecom Market Revenue Billion Forecast, by Region 2020 & 2034
Table 6: Global Morocco Telecom Market Volume Subscribers Forecast, by Region 2020 & 2034
Table 7: Urban Centers Morocco Telecom Market Revenue Billion Forecast, by Service Type 2020 & 2034
Table 8: Urban Centers Morocco Telecom Market Volume Subscribers Forecast, by Service Type 2020 & 2034
Table 9: Urban Centers Morocco Telecom Market Revenue Billion Forecast, by End User 2020 & 2034
Urban Centers Morocco Telecom Market Volume Subscribers Forecast, by End User 2020 & 2034
Frequently Asked Questions
1What is the size of the Morocco telecom market?
The Morocco telecom market is estimated at USD 3.87 billion in 2026 and is forecast to reach USD 4.64 billion by 2031, growing at a CAGR of 3.72%. In volume terms, the subscriber base is projected to grow from 62.92 million in 2026 to 75.16 million by 2031.
2Who are the major players in the Morocco telecom market?
The market is dominated by three operators: Maroc Telecom (36.1% market share), Orange Maroc (32.9%), and Inwi (31.0%). Near-parity competition drives aggressive pricing and infrastructure-sharing collaborations.
3Which segment leads the Morocco telecom market?
Data and internet services led with 50.02% of market share in 2025, while the consumer segment accounted for 86.95% of market size. The enterprise segment is the fastest-growing, projected at a 4.43% CAGR through 2031.
4What is driving growth in the Morocco telecom market?
Key drivers include 5G spectrum auctions and rollout (2025–2030), surging mobile data consumption among the under-30 population, the Digital Morocco 2030 fiber investment program, and enterprise demand for private LTE/5G at industrial zones.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of data in this report is derived from primary research, including direct interviews with senior executives, network engineers, and procurement heads across the Morocco telecom value chain.
We conduct 150+ in-depth interviews annually with stakeholders such as MNO strategy directors, fiber infrastructure project managers, enterprise IT procurement leads, and regulatory affairs officers.
Company types surveyed include MNOs (Maroc Telecom, Orange Maroc, Inwi), tower and fiber infrastructure providers, enterprise solution integrators, and OTT/content service providers.
Stakeholder job titles include Chief Strategy Officer, Network Operations Director, Procurement Director, and Regulatory Compliance Manager.
Quantitative metrics captured include ARPU by service segment, subscriber churn rates, 5G coverage percentages, fiber homes-passed figures, and enterprise contract values.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Strategy Officer
30%
Network Operations Director
25%
Procurement Director
25%
Regulatory Compliance Manager
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Mobile Network Operators (MNOs)
35%
Tower and Fiber Infrastructure Providers
Figure 10:
Figure 11: Urban Centers Morocco Telecom Market Revenue (Billion), by Country 2026 & 2034
Figure 12: Urban Centers Morocco Telecom Market Volume (Subscribers), by Country 2026 & 2034
Figure 13: Urban Centers Morocco Telecom Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Urban Centers Morocco Telecom Market Volume Share (%), by Country 2026 & 2034
Figure 15: Rural Areas Morocco Telecom Market Revenue (Billion), by Service Type 2026 & 2034
Figure 16: Rural Areas Morocco Telecom Market Volume (Subscribers), by Service Type 2026 & 2034
Figure 17: Rural Areas Morocco Telecom Market Revenue Share (%), by Service Type 2026 & 2034
Figure 18: Rural Areas Morocco Telecom Market Volume Share (%), by Service Type 2026 & 2034
Figure 19: Rural Areas Morocco Telecom Market Revenue (Billion), by End User 2026 & 2034
Figure 20: Rural Areas Morocco Telecom Market Volume (Subscribers), by End User 2026 & 2034
Figure 21: Rural Areas Morocco Telecom Market Revenue Share (%), by End User 2026 & 2034
Figure 22: Rural Areas Morocco Telecom Market Volume Share (%), by End User 2026 & 2034
Figure 23: Rural Areas Morocco Telecom Market Revenue (Billion), by Country 2026 & 2034
Figure 24: Rural Areas Morocco Telecom Market Volume (Subscribers), by Country 2026 & 2034
Figure 25: Rural Areas Morocco Telecom Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Rural Areas Morocco Telecom Market Volume Share (%), by Country 2026 & 2034
Figure 27: Industrial Zones Morocco Telecom Market Revenue (Billion), by Service Type 2026 & 2034
Figure 28: Industrial Zones Morocco Telecom Market Volume (Subscribers), by Service Type 2026 & 2034
Figure 29: Industrial Zones Morocco Telecom Market Revenue Share (%), by Service Type 2026 & 2034
Figure 30: Industrial Zones Morocco Telecom Market Volume Share (%), by Service Type 2026 & 2034
Figure 31: Industrial Zones Morocco Telecom Market Revenue (Billion), by End User 2026 & 2034
Figure 32: Industrial Zones Morocco Telecom Market Volume (Subscribers), by End User 2026 & 2034
Figure 33: Industrial Zones Morocco Telecom Market Revenue Share (%), by End User 2026 & 2034
Figure 34: Industrial Zones Morocco Telecom Market Volume Share (%), by End User 2026 & 2034
Figure 35: Industrial Zones Morocco Telecom Market Revenue (Billion), by Country 2026 & 2034
Figure 36: Industrial Zones Morocco Telecom Market Volume (Subscribers), by Country 2026 & 2034
Figure 37: Industrial Zones Morocco Telecom Market Revenue Share (%), by Country 2026 & 2034
Figure 38: Industrial Zones Morocco Telecom Market Volume Share (%), by Country 2026 & 2034
Table 10:
Table 11: Urban Centers Morocco Telecom Market Revenue Billion Forecast, by Country 2020 & 2034
Table 12: Urban Centers Morocco Telecom Market Volume Subscribers Forecast, by Country 2020 & 2034
5What are the challenges facing the Morocco telecom market?
The market faces intense price competition driving ARPU erosion, heavy regulatory fines and compliance costs on incumbents, OTT substitution for voice and messaging, and the incumbent's strategic dominance over fixed infrastructure.
25%
Enterprise Solution Integrators
20%
OTT and Content Service Providers
12%
Regulatory and Government Bodies
8%
Secondary Research & Industry Benchmarking
20–30% of data is sourced from secondary research, including official publications from the ANRT, World Bank, OECD, and ITU.
We benchmark market estimates against national accounts, spectrum licensing records, and trade association reports from GSMA and the Fibre to the Home Council.
Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook are used to validate operator revenue, M&A activity, and investment trends.
All secondary sources are cross-referenced with primary interview data to ensure consistency and accuracy.
Demand Modeling & Market Estimation
We employ both top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up modeling aggregates subscriber numbers by service type (voice, data, IoT, OTT) and multiplies by ARPU to derive segment revenue, which is then summed to market size.
Top-down modeling starts with national telecom revenue reported by ANRT and disaggregates by service segment and end-user using operator financial disclosures.
Key variables in the demand model include population growth, smartphone penetration, data consumption per user, 5G adoption curves, and enterprise digital transformation spending.
Scenario analysis (base, optimistic, pessimistic) is conducted to account for regulatory, technological, and macroeconomic uncertainties.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through rigorous multi-stage validation.
Every data point is triangulated across at least three independent sources: primary interviews, official regulatory filings, and trade association benchmarks.
Real-time validation is performed against ANRT quarterly market reports and operator earnings releases.
Every report is updated to the date of purchase, ensuring the most current market data and competitive intelligence.
A dedicated quality assurance team reviews all models, assumptions, and outputs before publication.
SaaS Backup Software market to reach $5.12 Billion by 2035 at 15.61% CAGR. Explore key trends, top companies, and regional insights in this comprehensive report.
Nov 2026|190 pages
$2900.00
The global gymnastics club management software market is valued at $1.24 billion in 2025 and is projected to grow at a CAGR of 14.2% through 2035.
Nov 2026|235 pages
$2900.00
FP&A software market valued at $3.9B in 2025, growing at 16.4% CAGR to $9.7B by 2033. Read our proprietary analysis of cloud, AI, and regional trends.