1How large is the U.K. core banking software market?
The U.K. core banking software market generated US$ 796.8 million in 2025 and is projected to reach US$ 1,640.6 million by 2033, according to our proprietary primary research.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 U.K. Core Banking Software
 by Component (Solution(Deposits, Loans, Enterprise Customer Solutions, Others), Service(Professional Service, Managed Service)), by Deployment (Cloud, On-Premise, SaaS/Hosted, Licensed), by Bank Type (Large Banks, Midsize Bank, Small Banks, Community Banks, Credit Unions, Others), by End Use (Banks, Financial Institutions, Retail Banking, Treasury, Corporate Banking, Wealth Management, Others), by England, by Scotland, by Wales, by Northern Ireland Forecast 2026-2034

Senior Research Analyst


 Related Reports

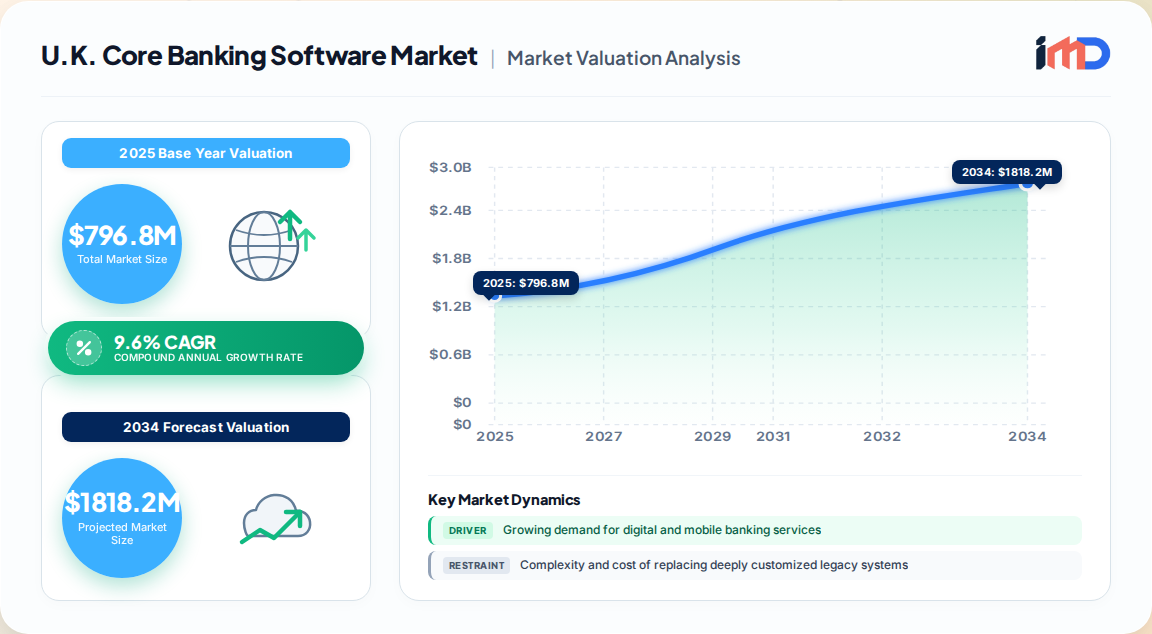
The U.K. core banking software market generated US$ 796.8 million in revenue in 2025 and is projected to expand to US$ 1,640.6 million by 2033, advancing at a CAGR of 9.6% across the 2026–2033 forecast window. Base-year 2026 revenue is estimated at US$ 863.4 million.
The United Kingdom remains one of the most consequential core banking arenas globally, accounting for approximately 6.0% of worldwide core banking software revenue in 2025. This disproportionate share reflects the depth of the U.K.'s banking sector, its dense fintech ecosystem, and a regulatory environment — anchored by Open Banking and PSD2-derived obligations — that structurally rewards software-led modernization.
Three structural forces define the current cycle:
Our proprietary bottom-up modeling, triangulated against institution-level IT spend disclosures and vendor revenue attribution, indicates the market will add roughly US$ 844 million in incremental revenue between 2025 and 2033.
| Component | 2025 Position | Growth Profile |
|---|---|---|
| Solution | Largest segment, 67.88% share | Steady, license and subscription led |
| Service | Smaller base | Fastest-growing component |
The services segment's acceleration is consistent with a market transitioning from license acquisition to outcome-based modernization programs. Professional services — implementation, integration, data migration, and regulatory configuration — dominate, while managed services grow as institutions offload run-state operations.
Solution-level segmentation includes deposits, loans, enterprise customer solutions, and adjacent modules, with enterprise customer solutions commanding the largest revenue block.
England dominates the U.K. market, anchored by London's role as a global financial centre and the concentration of Tier-1 headquarters, challenger banks, and fintech vendors. Scotland presents a robust financial services base with an expanding fintech cluster and emphasis on blockchain and digital assets. Wales shows a smaller but sustainability- and responsible-banking-oriented appetite. Northern Ireland skews toward innovation and cybersecurity-focused adoption.
| Region | Share of U.K. Market | Strategic Character |
|---|---|---|
| England | 62% | Tier-1 concentration, challenger banks, vendor HQs |
| Scotland | 17% | Established financial sector, fintech growth |
| Wales | 11% | Smaller base, sustainability focus |
| Northern Ireland | 10% | Cybersecurity and technology-led adoption |
Investment white-space concentrates in three areas: mid-tier bank core replacement programs, managed-service wrappers for smaller institutions, and AI-native risk and lending modules layered onto existing cores.
The U.K. vendor field spans global software majors, banking specialists, and India-headquartered IT services firms with dedicated core banking platforms. Notable participants active in the U.K. market include Temenos, Finastra, Oracle, FIS, Infosys (Finacle), SAP, Capgemini, Fiserv, Jack Henry & Associates, HCL Technologies, Unisys, Fidelity National Information Services, TCS, Sopra Banking Software, NCR, Mambu, Thought Machine, Tuum, and SaaScada.
Recent market developments observed in our primary research program:
Competitive advantage in this market increasingly accrues to vendors that pair open API depth with proven migration tooling and regulatory reporting coverage.
Applying an Ansoff-style lens to the U.K. core banking software market reveals four viable strategic postures:
The strongest near-term white-space sits with midsize U.K. banks — institutions large enough to require full core functionality but too small to absorb Tier-1 transformation costs.
Value is migrating downstream toward services and managed operations, where recurring revenue and switching costs are highest.
Our proprietary forecast anticipates continued double-digit-adjacent growth, with the market reaching US$ 1,640.6 million by 2033 at 9.6% CAGR. Upside scenarios hinge on accelerated cloud migration among Tier-1 institutions and faster AI monetization; downside risks center on elongated procurement cycles and legacy migration cost overruns.
The services component is expected to outperform the market average throughout the forecast period, reinforcing a shift toward outcome-oriented vendor business models across the U.K. core banking software landscape.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.6% from 2020-2034 |
| Segmentation |
|
By Deployment
By Bank Type
By End Use
| By Geography |
|
The U.K. core banking software market generated US$ 796.8 million in 2025 and is projected to reach US$ 1,640.6 million by 2033, according to our proprietary primary research.
The market is expected to grow at a CAGR of 9.6% from 2026 to 2033, with 2026 revenue estimated at US$ 863.4 million.
Solutions represented the largest component segment with a 67.88% revenue share in 2025, while services constitute the fastest-growing component through 2033.
Cloud deployment is the largest and fastest-advancing segment, supported by FCA cloud guidance and scalability economics, though on-premise retains a substantial Tier-1 installed base.
Leading participants include Temenos, Finastra, Oracle, FIS, Infosys Finacle, SAP, Capgemini, Fiserv, and Thought Machine, alongside emerging cloud-native specialists such as Mambu and Tuum.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Technology Officer | 32% |
| Head of Core Banking Transformation | 27% |
| Procurement Director | 23% |
| Chief Information Security Officer | 18% |
| Company Type | Representation (%) |
|---|---|
| Core Banking Software Vendors | 30% |
| U.K. Retail & Challenger Banks | 28% |
| Systems Integrators & Managed Service Providers | 18% |
| Cloud Infrastructure Providers | 14% |
| Specialist Fintech Module Suppliers | 10% |