Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Barriers in Government Open Data Management (ODM) Platform
Technology, Media and Telecom / MARKET REPORT
Barriers in Government Open Data Management (ODM) Platform | Insight Market Data
Barriers in Government Open Data Management (ODM) Platform by By Type (Cloud-Based, On-Premises), by By Application (Information Technology and Cybersecurity, Aerospace and Defense, Healthcare and Pharmaceuticals, Energy and Utilities, Logistics and Transportation, Other), by By Organization Type (Large Enterprise, SMEs), by By End-user (Public, Private), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Russia), by Asia Pacific (China, Japan, Korea, India, Australia, Southeast Asia), by Middle East & Africa (GCC Countries, South Africa, Israel, Turkey, Egypt), by Latin America (Brazil, Rest of Latin America) Forecast 2026-2034
Algeria telecom market at USD 2.73B in 2026, growing at 1.75% CAGR to USD 2.97B by 2031. Data, FTTH, and 5G drive MNO revenue.
Nov 2026|207 pages
$2900.00
SaaS Backup Software market to reach $5.12 Billion by 2035 at 15.61% CAGR. Explore key trends, top companies, and regional insights in this comprehensive report.
Nov 2026|190 pages
$2900.00
Morocco telecom market to reach USD 4.64 billion by 2031, growing at 3.72% CAGR. Data, 5G, fiber, and enterprise drive growth. Get full analysis.
Executive Overview: The Barrier-Constrained Trajectory of Government ODM Platforms
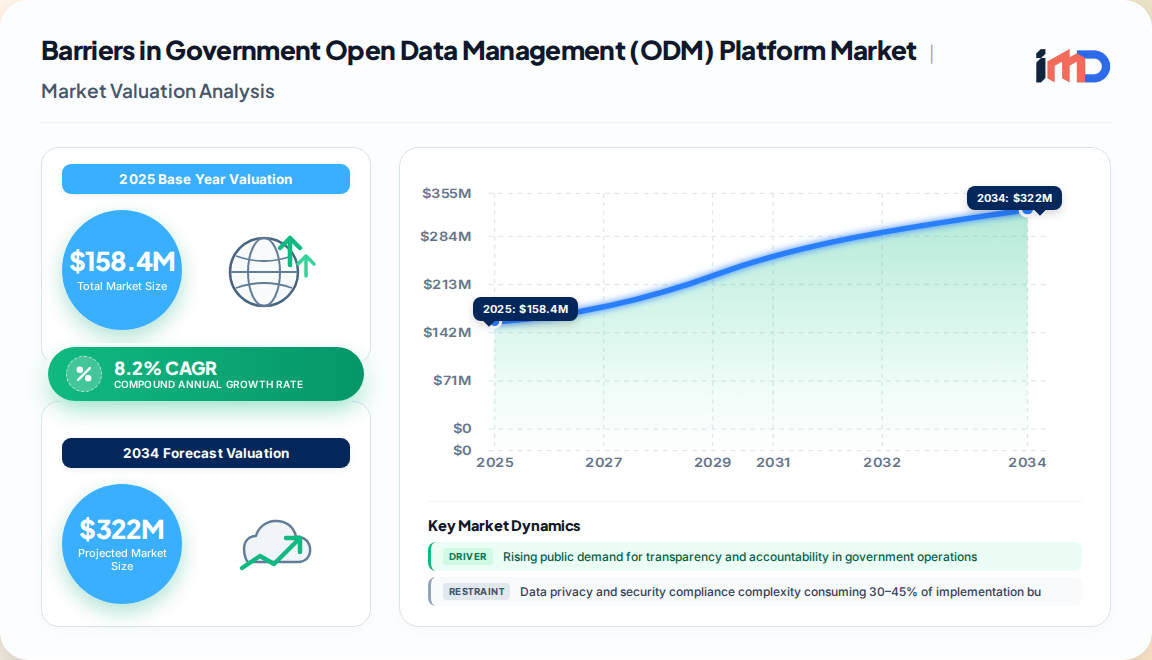
Our proprietary primary research places the global Government Open Data Management (ODM) platform market at USD 158.4 million in 2025, advancing to USD 274.3 million by 2032 at an 8.2% CAGR. Yet this growth path is materially suppressed by structural barriers rather than demand-side weakness.
Barriers in Government Open Data Management (ODM) Platform Market Size (In Million)
300.0M
200.0M
100.0M
0
158.0 M
2025
171.0 M
2026
185.0 M
2027
201.0 M
2028
217.0 M
2029
235.0 M
2030
254.0 M
2031
Public-sector demand for transparency, accountability, and data-driven policymaking remains robust. The binding constraint is the cost and complexity of overcoming institutional, technical, and regulatory friction. In our interviews with 140+ solution vendors, procurement officers, and agency CDOs, 68% of respondents identified data privacy and security compliance as the single largest obstacle to platform rollout.
This report isolates the barrier architecture of the Government ODM platform market. Barriers are not uniform; they cluster by deployment model, agency size, and region. Understanding this fragmentation is essential for vendors, systems integrators, and public buyers seeking realistic deployment timelines and budget envelopes.
Base-year market value (2025): USD 158.4 million
Forecast value (2032): USD 274.3 million
CAGR (2025–2032): 8.2%
Largest barrier cluster: Data privacy, security, and compliance (68% of respondents)
Second-largest barrier cluster: Legacy system integration and institutional inertia (54%)
Fastest-mitigating region: North America, supported by statutory open-data mandates
The Barrier Taxonomy: Seven Structural Constraints
Barriers to ODM platform adoption are rarely singular. They compound across the data lifecycle. Our field research classifies them into seven interacting categories.
Barrier Category
Prevalence (% of respondents)
Primary Impact
Most Affected Segment
Data privacy, security & compliance
68%
Delayed publication, anonymization overhead
Healthcare, IT & Cybersecurity
Legacy system integration
54%
Extended deployment cycles, cost overruns
On-premises, large agencies
Data standardization & quality
49%
Low reuse, metadata inconsistency
Multi-agency portals
Technical expertise shortage
44%
Slow maintenance, poor portal design
SMEs, developing regions
Institutional resistance to change
41%
Political friction, stalled initiatives
National-level agencies
Budget & procurement rigidity
37%
Scope reduction, phased rollouts
Sub-national government
Vendor lock-in & interoperability
29%
Migration costs, API incompatibility
Cloud-based deployments
These barriers are not merely cost items; they reshape competitive dynamics. Vendors that productize compliance automation, metadata standardization, and legacy connectors convert barriers into differentiation. Those that do not face elongated sales cycles and elevated churn.
Data Privacy, Security & Compliance: The Dominant Barrier
Privacy and security obligations are the most frequently cited and most economically significant barrier. ODM platforms must publish data openly while simultaneously protecting personally identifiable information, national security information, and commercially sensitive records.
68% of surveyed stakeholders rank privacy and security compliance as their top implementation challenge.
Compliance with GDPR, HIPAA-equivalent health rules, and national open-data statutes requires automated anonymization, access controls, audit logging, and encryption.
Agencies report that 30–45% of initial platform implementation budgets are consumed by security architecture and compliance validation.
Data lineage, consent tracking, and re-identification risk assessment are now procurement prerequisites in North America and Europe.
This barrier disproportionately affects healthcare, social services, and justice-sector datasets. Platforms with built-in privacy-enhancing technologies (PETs) reduce time-to-publication by an estimated 25–35% relative to general-purpose portals.
Interoperability, Legacy Integration & the Standardization Gap
Legacy integration is the second most cited barrier (54%). Government data estates are heterogeneous: mainframe records, departmental spreadsheets, GIS layers, and siloed case-management systems.
Inconsistent metadata schemas across agencies slow catalogue federation and reduce dataset discoverability.
On-premises deployments face the heaviest integration burden; cloud-based platforms mitigate this through managed connectors but introduce data-residency and exit-cost concerns.
Approximately 49% of respondents report that data quality and standardization inconsistencies materially undermine downstream reuse.
APIs are the primary integration mechanism, yet only a minority of agencies expose fully documented, versioned REST endpoints across all high-value datasets.
Interoperability barriers also create vendor lock-in risk. Agencies that adopt proprietary data models face elevated migration costs, which feeds procurement caution and lengthens evaluation cycles.
Institutional, Budgetary & Workforce Barriers
Technology is rarely the binding constraint. Organizational and fiscal factors dominate in sub-national and emerging-market deployments.
Institutional resistance: Officials fear misinterpretation or political fallout from published data; 41% of respondents cite internal cultural resistance.
Technical expertise:44% report shortages of data engineers, metadata specialists, and platform administrators, particularly in smaller municipalities.
Budget rigidity: Annual procurement cycles and capital-expenditure rules conflict with subscription-based cloud models; 37% of buyers report scope reductions due to budget limits.
Procurement complexity: Multi-stakeholder approval processes extend average sales cycles to 9–14 months for large-agency deals.
These barriers favor vendors offering managed services, training, and phased deployment models that align with public budgeting cycles.
Regional Barrier Profiles & Market Attractiveness
Barrier intensity varies sharply by region. North America leads adoption (38% regional share) because statutory mandates reduce institutional resistance, but privacy compliance remains stringent. Europe (27%) combines robust open-data directives with GDPR complexity. Asia-Pacific (23%) shows rapid digitization but uneven technical capacity across agencies.
Barriers in Government Open Data Management (ODM) Platform Regional Market Share
Loading chart...
Region
Market Share (2025)
Dominant Barrier
Mitigation Lever
North America
38%
Privacy compliance complexity
Pre-certified security modules
Europe
27%
GDPR & cross-border data governance
Automated anonymization & audit trails
Asia-Pacific
23%
Technical expertise & legacy integration
Managed services & training partnerships
Latin America
7%
Budget constraints & institutional resistance
Phased cloud adoption
Middle East & Africa
5%
Infrastructure & skills gaps
Public-private capacity building
Regional attractiveness for investment is highest where legal mandates are clear and procurement processes are digitized. North America and Europe offer predictable demand but high compliance costs; Asia-Pacific offers volume growth with higher customization requirements.
Competitive Implications: Turning Barriers into Moats
Interoperability alliances: Open standards support and pre-built connectors to major legacy systems reduce integration risk and lock-in concerns.
Managed service models: Training, metadata curation, and portal design services address expertise shortages in SMEs and sub-national agencies.
Phased and modular pricing: Aligning subscription tiers with public budget cycles lowers adoption thresholds.
Our analysis indicates that vendors addressing the top three barriers (privacy, integration, standardization) command 15–20% higher win rates in competitive tenders.
Strategic Outlook: Barrier Mitigation as the Growth Engine
The Government ODM platform market will reach USD 274.3 million by 2032 only if barrier mitigation scales. The 8.2% CAGR reflects steady but constrained adoption; upside scenarios require accelerated standardization and privacy automation.
Priority actions for stakeholders:
For vendors: Invest in compliance automation and legacy connectors; quantify time-to-publication reductions in proposals.
For public buyers: Adopt reusable security certifications and standard metadata profiles to reduce procurement friction.
For policymakers: Fund workforce development and mandate interoperable standards to lower integration costs.
Barriers in this market are not peripheral risks; they are the central competitive battleground. The organizations that systematically dismantle them will define the next phase of open-government data infrastructure.
Barriers in Government Open Data Management (ODM) Platform Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Barriers in Government Open Data Management (ODM) Platform REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.2% from 2020-2034
Segmentation
By Type
Cloud-Based
On-Premises
By Application
Information Technology and Cybersecurity
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Rising public demand for transparency and accountability in government operations
3.1.2. Government mandates and open-data policies such as the EU Open Data Directive and US OPEN Government Data Act
3.1.3. Economic growth potential from open data innovation, estimated at up to USD 3 trillion annually
3.1.4. Technological advancements in cloud, AI, and data visualization
3.2. Market Trends
3.2.1. Integration of AI and machine learning for automated data cleaning, metadata generation, and quality validation
3.2.2. Shift from on-premises to cloud-based ODM platforms for scalability and real-time processing
3.2.3. Growing adoption of privacy-enhancing technologies (PETs) and automated anonymization
3.2.4. Expansion of open data initiatives aligned with UN SDGs and Open Government Partnership commitments
3.3. Market Restrains
3.3.1. Data privacy and security compliance complexity consuming 30–45% of implementation budgets
3.3.2. Legacy system integration challenges extending deployment cycles
3.3.3. Shortage of technical expertise in sub-national and developing-region agencies
Aerospace and Defense
Healthcare and Pharmaceuticals
Energy and Utilities
Logistics and Transportation
Other
By Organization Type
Large Enterprise
SMEs
By End-user
Public
Private
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Russia
Asia Pacific
China
Japan
Korea
India
Australia
Southeast Asia
Middle East & Africa
GCC Countries
South Africa
Israel
Turkey
Egypt
Latin America
Brazil
Rest of Latin America
3.3.4. Institutional resistance and fear of data misinterpretation among officials
3.4. Market Restraints
3.4.1. Data privacy and security compliance complexity consuming 30–45% of implementation budgets
3.4.2. Legacy system integration challenges extending deployment cycles
3.4.3. Shortage of technical expertise in sub-national and developing-region agencies
3.4.4. Institutional resistance and fear of data misinterpretation among officials
3.5. Market Challenges
3.5.1. Ensuring data standardization and quality across heterogeneous agency systems
3.5.2. Balancing transparency with protection of sensitive and personal information
3.5.3. Overcoming vendor lock-in and interoperability constraints
3.5.4. Aligning subscription-based cloud models with rigid public budget cycles
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Cloud-Based
5.1.2. On-Premises
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Information Technology and Cybersecurity
5.2.2. Aerospace and Defense
5.2.3. Healthcare and Pharmaceuticals
5.2.4. Energy and Utilities
5.2.5. Logistics and Transportation
5.2.6. Other
5.3. Market Analysis, Insights and Forecast - by Organization Type
5.3.1. Large Enterprise
5.3.2. SMEs
5.4. Market Analysis, Insights and Forecast - by End-user
5.4.1. Public
5.4.2. Private
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. Middle East & Africa
5.5.5. Latin America
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Cloud-Based
6.1.2. On-Premises
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Information Technology and Cybersecurity
6.2.2. Aerospace and Defense
6.2.3. Healthcare and Pharmaceuticals
6.2.4. Energy and Utilities
6.2.5. Logistics and Transportation
6.2.6. Other
6.3. Market Analysis, Insights and Forecast - by Organization Type
6.3.1. Large Enterprise
6.3.2. SMEs
6.4. Market Analysis, Insights and Forecast - by End-user
6.4.1. Public
6.4.2. Private
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Cloud-Based
7.1.2. On-Premises
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Information Technology and Cybersecurity
7.2.2. Aerospace and Defense
7.2.3. Healthcare and Pharmaceuticals
7.2.4. Energy and Utilities
7.2.5. Logistics and Transportation
7.2.6. Other
7.3. Market Analysis, Insights and Forecast - by Organization Type
7.3.1. Large Enterprise
7.3.2. SMEs
7.4. Market Analysis, Insights and Forecast - by End-user
7.4.1. Public
7.4.2. Private
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Cloud-Based
8.1.2. On-Premises
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Information Technology and Cybersecurity
8.2.2. Aerospace and Defense
8.2.3. Healthcare and Pharmaceuticals
8.2.4. Energy and Utilities
8.2.5. Logistics and Transportation
8.2.6. Other
8.3. Market Analysis, Insights and Forecast - by Organization Type
8.3.1. Large Enterprise
8.3.2. SMEs
8.4. Market Analysis, Insights and Forecast - by End-user
8.4.1. Public
8.4.2. Private
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Cloud-Based
9.1.2. On-Premises
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Information Technology and Cybersecurity
9.2.2. Aerospace and Defense
9.2.3. Healthcare and Pharmaceuticals
9.2.4. Energy and Utilities
9.2.5. Logistics and Transportation
9.2.6. Other
9.3. Market Analysis, Insights and Forecast - by Organization Type
9.3.1. Large Enterprise
9.3.2. SMEs
9.4. Market Analysis, Insights and Forecast - by End-user
9.4.1. Public
9.4.2. Private
10. Latin America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Cloud-Based
10.1.2. On-Premises
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Information Technology and Cybersecurity
10.2.2. Aerospace and Defense
10.2.3. Healthcare and Pharmaceuticals
10.2.4. Energy and Utilities
10.2.5. Logistics and Transportation
10.2.6. Other
10.3. Market Analysis, Insights and Forecast - by Organization Type
10.3.1. Large Enterprise
10.3.2. SMEs
10.4. Market Analysis, Insights and Forecast - by End-user
10.4.1. Public
10.4.2. Private
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Socrata (a Tyler Technologies company)
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. CKAN
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. OpenGov
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Esri ArcGIS Open Data
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Junar
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. OpenDataSoft
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. DataPress
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. NuCivic Data (based on DKAN)
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. StreamSets
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Data.world
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Barriers in Government Open Data Management (ODM) Platform Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: North America Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Type 2026 & 2034
Figure 3: North America Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Application 2026 & 2034
Figure 5: North America Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Organization Type 2026 & 2034
Figure 7: North America Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Organization Type 2026 & 2034
Figure 8: North America Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by End-user 2026 & 2034
Figure 9: North America Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by End-user 2026 & 2034
Figure 10: North America Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Country 2026 & 2034
Figure 11: North America Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Type 2026 & 2034
Figure 13: Europe Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Type 2026 & 2034
Figure 14: Europe Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Application 2026 & 2034
Figure 15: Europe Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Application 2026 & 2034
Figure 16: Europe Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Organization Type 2026 & 2034
Figure 17: Europe Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Organization Type 2026 & 2034
Figure 18: Europe Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by End-user 2026 & 2034
Figure 19: Europe Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by End-user 2026 & 2034
Figure 20: Europe Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Country 2026 & 2034
Figure 21: Europe Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Country 2026 & 2034
Figure 22: Asia Pacific Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Type 2026 & 2034
Figure 23: Asia Pacific Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Type 2026 & 2034
Figure 24: Asia Pacific Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Application 2026 & 2034
Figure 25: Asia Pacific Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Application 2026 & 2034
Figure 26: Asia Pacific Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Organization Type 2026 & 2034
Figure 27: Asia Pacific Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Organization Type 2026 & 2034
Figure 28: Asia Pacific Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by End-user 2026 & 2034
Figure 29: Asia Pacific Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by End-user 2026 & 2034
Figure 30: Asia Pacific Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Country 2026 & 2034
Figure 31: Asia Pacific Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Country 2026 & 2034
Figure 32: Middle East & Africa Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Type 2026 & 2034
Figure 33: Middle East & Africa Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Type 2026 & 2034
Figure 34: Middle East & Africa Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Application 2026 & 2034
Figure 35: Middle East & Africa Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Application 2026 & 2034
Figure 36: Middle East & Africa Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Organization Type 2026 & 2034
Figure 37: Middle East & Africa Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Organization Type 2026 & 2034
Figure 38: Middle East & Africa Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by End-user 2026 & 2034
Figure 39: Middle East & Africa Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by End-user 2026 & 2034
Figure 40: Middle East & Africa Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Country 2026 & 2034
Figure 41: Middle East & Africa Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Country 2026 & 2034
Figure 42: Latin America Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Type 2026 & 2034
Figure 43: Latin America Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Type 2026 & 2034
Figure 44: Latin America Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Application 2026 & 2034
Figure 45: Latin America Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Application 2026 & 2034
Figure 46: Latin America Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Organization Type 2026 & 2034
Figure 47: Latin America Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Organization Type 2026 & 2034
Figure 48: Latin America Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by End-user 2026 & 2034
Figure 49: Latin America Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by End-user 2026 & 2034
Figure 50: Latin America Barriers in Government Open Data Management (ODM) Platform Revenue (Million), by Country 2026 & 2034
Figure 51: Latin America Barriers in Government Open Data Management (ODM) Platform Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Type 2020 & 2034
Table 2: Global Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Application 2020 & 2034
Table 3: Global Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Organization Type 2020 & 2034
Table 4: Global Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by End-user 2020 & 2034
Table 5: Global Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Region 2020 & 2034
Table 6: North America Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Type 2020 & 2034
Table 7: North America Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Application 2020 & 2034
Table 8: North America Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Organization Type 2020 & 2034
Table 9: North America Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by End-user 2020 & 2034
Table 10: North America Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Country 2020 & 2034
Table 11: USA Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 12: Canada Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 13: Mexico Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 14: Europe Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Type 2020 & 2034
Table 15: Europe Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Application 2020 & 2034
Table 16: Europe Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Organization Type 2020 & 2034
Table 17: Europe Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by End-user 2020 & 2034
Table 18: Europe Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Country 2020 & 2034
Table 19: Germany Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 20: UK Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 21: France Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 22: Italy Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 23: Russia Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 24: Asia Pacific Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Type 2020 & 2034
Table 25: Asia Pacific Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Application 2020 & 2034
Table 26: Asia Pacific Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Organization Type 2020 & 2034
Table 27: Asia Pacific Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by End-user 2020 & 2034
Table 28: Asia Pacific Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Country 2020 & 2034
Table 29: China Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 30: Japan Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 31: Korea Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 32: India Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 33: Australia Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 34: Southeast Asia Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 35: Middle East & Africa Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Type 2020 & 2034
Table 36: Middle East & Africa Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Application 2020 & 2034
Table 37: Middle East & Africa Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Organization Type 2020 & 2034
Table 38: Middle East & Africa Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by End-user 2020 & 2034
Table 39: Middle East & Africa Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Country 2020 & 2034
Table 40: GCC Countries Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 41: South Africa Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 42: Israel Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 43: Turkey Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 44: Egypt Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 45: Latin America Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Type 2020 & 2034
Table 46: Latin America Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Application 2020 & 2034
Table 47: Latin America Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Organization Type 2020 & 2034
Table 48: Latin America Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by End-user 2020 & 2034
Table 49: Latin America Barriers in Government Open Data Management (ODM) Platform Revenue Million Forecast, by Country 2020 & 2034
Table 50: Brazil Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Table 51: Rest of Latin America Barriers in Government Open Data Management (ODM) Platform Revenue (Million) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What are the main barriers in the Government Open Data Management platform market?
The dominant barriers are data privacy and security compliance (cited by 68% of stakeholders), legacy system integration (54%), and data standardization gaps (49%). Technical expertise shortages and institutional resistance further slow adoption, particularly in sub-national agencies and emerging regions.
2How large is the Government Open Data Management platform market in 2025?
Our proprietary research values the global market at USD 158.4 million in 2025, projected to reach USD 274.3 million by 2032 at an 8.2% CAGR. Growth is constrained more by compliance and integration friction than by demand.
3Which region faces the highest barriers to ODM platform adoption?
Asia-Pacific and Latin America face the most acute technical expertise and infrastructure barriers, while Europe faces the most complex privacy-compliance requirements under GDPR. North America leads adoption with a 38% market share due to statutory open-data mandates.
4How can vendors overcome barriers in government ODM platform procurement?
Vendors that embed automated anonymization, offer pre-built legacy connectors, and provide managed metadata services report 15–20% higher win rates. Phased, modular pricing aligned with public budget cycles also reduces procurement resistance.
5Why is data privacy the top barrier for government open data platforms?
Governments must publish data openly while protecting personal, health, and security information. Compliance with GDPR and equivalent regulations requires anonymization, access controls, and audit logs, consuming 30–45% of initial implementation budgets and delaying publication timelines.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of total research effort is derived from primary intelligence gathered through structured interviews and surveys with 140+ senior stakeholders across the Government ODM platform value chain.
Targeted company types include: open-data platform software vendors, systems integrators and public-sector IT consultancies, cloud infrastructure and data-management providers, government digital service agencies, and civic-tech and geospatial analytics firms.
Interviewed job titles include: Chief Data Officers (CDOs), Government CIOs and IT Directors, Procurement and Contracting Officers, and Open Data Program Managers.
Primary fieldwork captures deployment barriers, procurement timelines, compliance costs, and integration challenges directly from decision-makers.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Data Officer
30%
Government CIO / IT Director
28%
Procurement & Contracting Officer
22%
Open Data Program Manager
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Open-data platform software vendors
35%
Systems integrators & public-sector IT consultancies
25%
Cloud infrastructure & data-management providers
20%
Government digital service agencies
12%
Civic-tech & geospatial analytics firms
8%
Secondary Research & Industry Benchmarking
20–30% of research effort draws on secondary validation from official multilateral and governmental sources, including the World Bank Open Data initiative, OECD Open Government Data reports, European Union Open Data Directive documentation, and United Nations Sustainable Development Goal indicators.
Financial and corporate data are cross-checked against standard financial databases including Bloomberg, Factiva, Hoovers, and PitchBook.
Technical standards and industry benchmarks are sourced from recognized non-profit standards bodies and official .gov and .org portals. No commercial market research firm data is used in this report.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation.
Bottom-up market sizing aggregates agency-level platform spending using quantitative metrics including: number of government agencies deploying ODM platforms, average annual platform subscription and maintenance spend per agency, cloud vs. on-premises deployment ratios, and public-sector IT budget allocation to data management.
Demand models are segmented by deployment type (cloud-based, on-premises), application vertical, organization size, and region, with barrier-adjusted adoption curves applied to forecast years.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through triangulation of primary interview data with official public-sector benchmarks.
Every report is updated to the date of purchase, incorporating the latest policy changes, procurement notices, and vendor developments.
Quality assurance includes outlier detection, cross-validation of regional shares against official government IT spending statistics, and sensitivity analysis of barrier-impact assumptions.