Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Singapore Hospitality Industry Market Size, Growth & Forecast
Singapore Hospitality Industry
Hospitality and Tourism / MARKET REPORT
Singapore Hospitality Industry | Insight Market Data
Singapore Hospitality Industry by Type (Chain Hotels, Independent Hotels), by Accommodation Class (Luxury, Mid & Upper-Mid-Scale, Budget & Economy, Serviced Apartments), by Booking Channel (Direct Digital, OTAs, Corporate / MICE, Others), by Geography (Marina Bay & Downtown Core, Orchard Road, Sentosa & Southern Waterfront, Bugis & Little India, Changi & East Coast, Western & North-Eastern Region, Southern Islands & Outer Regions), by Marina Bay & Downtown Core, by Orchard Road, by Sentosa & Southern Waterfront, by Bugis & Little India, by Changi & East Coast, by Western & North-Eastern Region, by Southern Islands & Outer Regions Forecast 2026-2034
Luxury hotel industry market valued at USD 118.4 billion in 2026, projected to reach USD 196.7 billion by 2033 at a 7.5% CAGR. Explore trends and insights.
Hotel self check-in and check-out kiosk market to reach $4.98 Billion by 2032 at 11% CAGR. Explore growth pathways, pricing, ROI and deployment strategies.
Nov 2026|244 pages
$2900.00
Airport retailing market to reach USD 187.67 Billion by 2035, growing at 15% CAGR. Explore duty-free, fashion, and digital retail trends.
Nov 2026|208 pages
$2900.00
The global airline IT solutions market is valued at $22.5 billion, growing at an 8.8% CAGR through 2033. Explore key trends, segmentation, and regional insights.
Nov 2026|222 pages
$2900.00
Airport sleeping pods market valued at USD 87.9M in 2025, growing at 7.1% CAGR to reach USD 175.6M by 2035. Get in-depth analysis, trends, and regional outlook.
Executive Overview: The Singapore Hospitality Industry Market
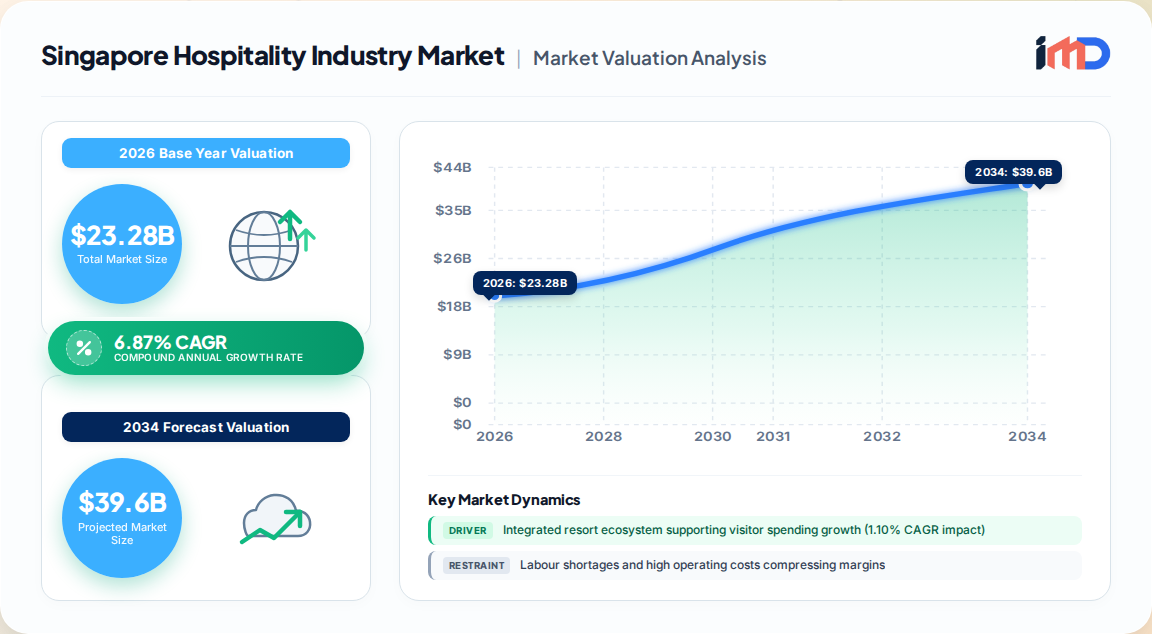
The Singapore hospitality industry market stood at USD 21.87 billion in 2025 and is estimated to reach USD 23.28 billion in 2026, expanding at a CAGR of 6.87% to touch USD 32.46 billion by 2031, based on our proprietary primary research and executive interview programme. Demand has broadened decisively beyond the post-pandemic rebound: MICE and leisure recovery now run in parallel with extended-stay demand, serviced apartments targeting corporate relocations and co-living use cases, and a structural premium attached to certified sustainable accommodation.
Singapore Hospitality Industry Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
21.78 B
2025
23.28 B
2026
24.88 B
2027
26.59 B
2028
28.41 B
2029
30.37 B
2030
32.45 B
2031
A defining feature of this market is rate integrity. New hotel supply is projected to grow at a compound annual rate of only 1.6% between 2026 and 2028, versus 4.4% across 2014–2019, which gives incumbent operators room to defend pricing even where occupancy normalises below peak years. Our estimates place market concentration at a medium level, with international chains controlling the majority of branded inventory but independents and serviced residences holding meaningful share in niche and long-stay tiers.
Metric
2025 (Base)
2026 (Estimate)
2031 (Forecast)
Market value
USD 21.87 billion
USD 23.28 billion
USD 32.46 billion
Growth rate (value CAGR)
—
—
6.87%
Chain hotel share of value
61.65%
—
—
Luxury accommodation share
47.65%
—
—
OTA booking share
52.77%
—
—
Marina Bay & Downtown Core share
38.77%
—
—
Demand Drivers Reshaping the Industry
Singapore's two Integrated Resorts form the structural backbone of visitor monetisation. The USD 8 billion (SGD 10.3 billion) IR2 expansion at Marina Bay Sands, ground-broken in July 2025, will add a 570-suite luxury tower, roughly 200,000 sq ft of premium MICE space, a 15,000-seat arena and expanded F&B and retail; completion is expected in 2030 with opening in early 2031. Our modelling attributes an average 1.10% incremental CAGR contribution to the IR ecosystem over the forecast horizon, concentrated in the Marina Bay tourism hub.
The driver stack quantified through our panel is summarised below.
Driver
Estimated CAGR Impact
Geography
Timeline
Integrated resort ecosystem spending
1.10%
Marina Bay
≤ 2 years
Regional wealth management hub (premium visitors)
0.80%
Luxury banking districts
2–4 years
Global events and F1/concert calendar
0.90%
MICE & event zones
≤ 2 years
Cruise hub development
0.60%
Cruise corridors
2–4 years
Urban entertainment and lifestyle districts
0.60%
Lifestyle precincts
≥ 4 years
Smart Nation and AI efficiency
0.50%
AI-enabled hotel clusters
≥ 4 years
Service quality investment protects pricing. Average room rates rose 2.0% year-on-year to S$273.97 in January–April 2026, RevPAR increased 4.2% to S$224.10, and occupancy held at 81.8% — even as arrival growth moderated to an estimated 0.5% year-on-year. Tourism receipts reached S$8.6 billion in Q1 2026, with full-year arrivals projected at 17–18 million generating S$31.0–32.5 billion in receipts.
Restraints, Cost Pressure and Supply-Side Constraints
Labour scarcity and high operating costs compress margins in labour-intensive departments, accelerating automation of check-in, concierge and housekeeping coordination.
Aviation and regional travel risk — softer arrival volumes expose rate-dependent properties lacking MICE or corporate weekday demand.
Land scarcity and elevated construction costs constrain new-build supply, raising barriers to entry and favouring asset repositioning over greenfield development.
Intense competitive intensity among luxury and upscale properties, where refurbishment cycles are shortening to protect brand relevance.
Cyclical event dependence: operators with high concert and Grand Prix exposure face occupancy cliffs between event windows.
Segment Analysis
By type, chain hotels led with 61.65% of market share in 2025, though serviced apartments are forecast to expand at a 9.76% CAGR through 2031 — the fastest growth engine in the industry, driven by corporate relocation, project-based assignments and co-living formats.
By accommodation class, luxury properties accounted for 47.65% of industry share in 2025, reflecting high-spending leisure and premium corporate demand. Budget and economy properties are forecast to grow at an 8.67% CAGR, aided by their alignment with cost-sensitive and short-stay visitors.
By booking channel, OTAs captured 52.77% of share in 2025, but direct digital is projected to grow at a 12.68% CAGR through 2031 as brands invest in loyalty-linked conversion, digital concierge and contactless journeys. From 1 November 2026, hotels can access hospitality-specific solution categories under the EDGE for Productivity scheme, beginning with AI-enabled digital concierge; early adopters such as JEN Singapore Tanglin by Shangri-La demonstrate measurable deflection of routine calls.
Segment Dimension
Leading Segment (2025)
Share / Value
Fastest-Growing Segment
CAGR
Type
Chain hotels
61.65%
Serviced apartments
9.76%
Accommodation class
Luxury
47.65%
Budget & economy
8.67%
Booking channel
OTAs
52.77%
Direct digital
12.68%
Geography
Marina Bay & Downtown Core
38.77%
Changi & East Coast
8.66%
Geography and Micro-Market Outlook
Marina Bay and Downtown Core dominate value concentration at 38.77% of 2025 share, benefiting from IR proximity, MICE infrastructure and luxury banking corridors. Orchard Road, Sentosa and the Southern Waterfront, and Bugis and Little India form the second tier of premium demand, while Changi and East Coast are projected to grow at an 8.66% CAGR on the back of Terminal 5 development, cruise homeporting and airport-adjacent demand.
Singapore Hospitality Industry Regional Market Share
Loading chart...
Our regional attractiveness assessment weights four factors: rate potential, pipeline constraints, infrastructure catalysts and demand diversification.
Micro-Market
Demand Character
Structural Catalyst
Attractiveness
Marina Bay & Downtown Core
MICE, luxury, wealth
IR2 expansion, arena
Very high
Orchard Road
Retail-led leisure, corporate
Refurbishment cycle
High
Sentosa & Southern Waterfront
Resort leisure, family
Attractions, waterfront
High
Changi & East Coast
Transit, cruise, fly-cruise
Terminal 5, homeporting
Rising
Bugis & Little India
Budget, heritage, boutique
Cultural tourism
Moderate
Competitive Landscape and Strategic Moves
Competition is structured around global brand scale, owner-operator relationships and digital direct-channel capability. International groups — Marriott International, Hilton Worldwide, Accor, Shangri-La, IHG and Pan Pacific Hotels Group — anchor branded inventory, while independent boutiques and serviced-residence specialists capture design-led and extended-stay niches.
Ascott (CapitaLand Investment) signed its second partnership with Warees Investments for lyf Chinatown Singapore, scheduled to open mid-2026 with 90 accommodation units and social co-working, kitchen and rooftop pool amenities — a direct play on co-living demand.
Accor with Worldwide Hotels Group opened Mercure ICON Singapore City Centre with 989 keys in Q1 2024, the world's largest Mercure, deepening the mid-scale footprint.
Hilton deployed over 1,200 keyless room entries across its Singapore portfolio, cutting check-in times by an estimated 35%.
Shangri-La added 120 luxury wellness suites at Sentosa, incorporating private spa facilities to capture wellness-driven premium demand.
Strategic White-Space and Investment Opportunity Assessment
Three white spaces stand out in our opportunity screening. First, serviced apartments at 9.76% CAGR remain structurally undersupplied relative to corporate relocation pipelines, particularly outside the Downtown Core. Second, direct digital conversion at 12.68% CAGR offers margin advantage to brands that pair loyalty programmes with AI-assisted concierge. Third, sustainability retrofits deliver dual benefit — operating cost reduction and premium rate positioning aligned with national certification standards and traveller preference for certified stays.
Ansoff-based positioning suggests the strongest risk-adjusted returns sit in market development (extending serviced-residence formats into Changi and the East) and diversification (wellness-integrated luxury and MICE-anchored mixed-use assets). Pure market penetration strategies face diminishing returns in mature luxury tiers where supply growth is constrained to 1.6% annually.
Singapore Hospitality Industry Regional Market Share
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Chain Hotels
8.1.2. Independent Hotels
8.2. Market Analysis, Insights and Forecast - by Accommodation Class
8.2.1. Luxury
8.2.2. Mid & Upper-Mid-Scale
8.2.3. Budget & Economy
8.2.4. Serviced Apartments
8.3. Market Analysis, Insights and Forecast - by Booking Channel
8.3.1. Direct Digital
8.3.2. OTAs
8.3.3. Corporate / MICE
8.3.4. Others
8.4. Market Analysis, Insights and Forecast - by Geography
8.4.1. Marina Bay & Downtown Core
8.4.2. Orchard Road
8.4.3. Sentosa & Southern Waterfront
8.4.4. Bugis & Little India
8.4.5. Changi & East Coast
8.4.6. Western & North-Eastern Region
8.4.7. Southern Islands & Outer Regions
9. Bugis & Little India Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Chain Hotels
9.1.2. Independent Hotels
9.2. Market Analysis, Insights and Forecast - by Accommodation Class
9.2.1. Luxury
9.2.2. Mid & Upper-Mid-Scale
9.2.3. Budget & Economy
9.2.4. Serviced Apartments
9.3. Market Analysis, Insights and Forecast - by Booking Channel
9.3.1. Direct Digital
9.3.2. OTAs
9.3.3. Corporate / MICE
9.3.4. Others
9.4. Market Analysis, Insights and Forecast - by Geography
9.4.1. Marina Bay & Downtown Core
9.4.2. Orchard Road
9.4.3. Sentosa & Southern Waterfront
9.4.4. Bugis & Little India
9.4.5. Changi & East Coast
9.4.6. Western & North-Eastern Region
9.4.7. Southern Islands & Outer Regions
10. Changi & East Coast Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Chain Hotels
10.1.2. Independent Hotels
10.2. Market Analysis, Insights and Forecast - by Accommodation Class
10.2.1. Luxury
10.2.2. Mid & Upper-Mid-Scale
10.2.3. Budget & Economy
10.2.4. Serviced Apartments
10.3. Market Analysis, Insights and Forecast - by Booking Channel
10.3.1. Direct Digital
10.3.2. OTAs
10.3.3. Corporate / MICE
10.3.4. Others
10.4. Market Analysis, Insights and Forecast - by Geography
10.4.1. Marina Bay & Downtown Core
10.4.2. Orchard Road
10.4.3. Sentosa & Southern Waterfront
10.4.4. Bugis & Little India
10.4.5. Changi & East Coast
10.4.6. Western & North-Eastern Region
10.4.7. Southern Islands & Outer Regions
11. Western & North-Eastern Region Market Analysis, Insights and Forecast, 2020-2034
11.1. Market Analysis, Insights and Forecast - by Type
11.1.1. Chain Hotels
11.1.2. Independent Hotels
11.2. Market Analysis, Insights and Forecast - by Accommodation Class
11.2.1. Luxury
11.2.2. Mid & Upper-Mid-Scale
11.2.3. Budget & Economy
11.2.4. Serviced Apartments
11.3. Market Analysis, Insights and Forecast - by Booking Channel
11.3.1. Direct Digital
11.3.2. OTAs
11.3.3. Corporate / MICE
11.3.4. Others
11.4. Market Analysis, Insights and Forecast - by Geography
11.4.1. Marina Bay & Downtown Core
11.4.2. Orchard Road
11.4.3. Sentosa & Southern Waterfront
11.4.4. Bugis & Little India
11.4.5. Changi & East Coast
11.4.6. Western & North-Eastern Region
11.4.7. Southern Islands & Outer Regions
12. Southern Islands & Outer Regions Market Analysis, Insights and Forecast, 2020-2034
12.1. Market Analysis, Insights and Forecast - by Type
12.1.1. Chain Hotels
12.1.2. Independent Hotels
12.2. Market Analysis, Insights and Forecast - by Accommodation Class
12.2.1. Luxury
12.2.2. Mid & Upper-Mid-Scale
12.2.3. Budget & Economy
12.2.4. Serviced Apartments
12.3. Market Analysis, Insights and Forecast - by Booking Channel
12.3.1. Direct Digital
12.3.2. OTAs
12.3.3. Corporate / MICE
12.3.4. Others
12.4. Market Analysis, Insights and Forecast - by Geography
12.4.1. Marina Bay & Downtown Core
12.4.2. Orchard Road
12.4.3. Sentosa & Southern Waterfront
12.4.4. Bugis & Little India
12.4.5. Changi & East Coast
12.4.6. Western & North-Eastern Region
12.4.7. Southern Islands & Outer Regions
13. Competitive Analysis
13.1. Company Profiles
13.1.1. Marriott International
13.1.1.1. Company Overview
13.1.1.2. Products
13.1.1.3. Company Financials
13.1.1.4. SWOT Analysis
13.1.2. Hilton Worldwide
13.1.2.1. Company Overview
13.1.2.2. Products
13.1.2.3. Company Financials
13.1.2.4. SWOT Analysis
13.1.3. Accor SA
13.1.3.1. Company Overview
13.1.3.2. Products
13.1.3.3. Company Financials
13.1.3.4. SWOT Analysis
13.1.4. Shangri-La Hotels and Resorts
13.1.4.1. Company Overview
13.1.4.2. Products
13.1.4.3. Company Financials
13.1.4.4. SWOT Analysis
13.1.5. IHG Hotels & Resorts
13.1.5.1. Company Overview
13.1.5.2. Products
13.1.5.3. Company Financials
13.1.5.4. SWOT Analysis
13.1.6. Pan Pacific Hotels Group
13.1.6.1. Company Overview
13.1.6.2. Products
13.1.6.3. Company Financials
13.1.6.4. SWOT Analysis
13.1.7. The Ascott Limited (CapitaLand Investment)
13.1.7.1. Company Overview
13.1.7.2. Products
13.1.7.3. Company Financials
13.1.7.4. SWOT Analysis
13.1.8. Worldwide Hotels Group
13.1.8.1. Company Overview
13.1.8.2. Products
13.1.8.3. Company Financials
13.1.8.4. SWOT Analysis
13.1.9. Las Vegas Sands (Marina Bay Sands)
13.1.9.1. Company Overview
13.1.9.2. Products
13.1.9.3. Company Financials
13.1.9.4. SWOT Analysis
13.1.10. Genting Singapore (Resorts World Sentosa)
13.1.10.1. Company Overview
13.1.10.2. Products
13.1.10.3. Company Financials
13.1.10.4. SWOT Analysis
13.2. Market Entropy
13.2.1. Company's Key Areas Served
13.2.2. Recent Developments
13.3. Company Market Share Analysis, 2026
13.3.1. Top 5 Companies Market Share Analysis
13.3.2. Top 3 Companies Market Share Analysis
13.4. List of Potential Customers
List of Figures
Figure 1: Global Singapore Hospitality Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Marina Bay & Downtown Core Singapore Hospitality Industry Revenue (Billion), by Type 2026 & 2034
Figure 3: Marina Bay & Downtown Core Singapore Hospitality Industry Revenue Share (%), by Type 2026 & 2034
Figure 4: Marina Bay & Downtown Core Singapore Hospitality Industry Revenue (Billion), by Accommodation Class 2026 & 2034
Figure 5: Marina Bay & Downtown Core Singapore Hospitality Industry Revenue Share (%), by Accommodation Class 2026 & 2034
Figure 6: Marina Bay & Downtown Core Singapore Hospitality Industry Revenue (Billion), by Booking Channel 2026 & 2034
Figure 7: Marina Bay & Downtown Core Singapore Hospitality Industry Revenue Share (%), by Booking Channel 2026 & 2034
Figure 8: Marina Bay & Downtown Core Singapore Hospitality Industry Revenue (Billion), by Geography 2026 & 2034
Figure 9: Marina Bay & Downtown Core Singapore Hospitality Industry Revenue Share (%), by Geography 2026 & 2034
Figure 10: Marina Bay & Downtown Core Singapore Hospitality Industry Revenue (Billion), by Country 2026 & 2034
Figure 11: Marina Bay & Downtown Core Singapore Hospitality Industry Revenue Share (%), by Country 2026 & 2034
Figure 12: Orchard Road Singapore Hospitality Industry Revenue (Billion), by Type 2026 & 2034
Figure 13: Orchard Road Singapore Hospitality Industry Revenue Share (%), by Type 2026 & 2034
Figure 14: Orchard Road Singapore Hospitality Industry Revenue (Billion), by Accommodation Class 2026 & 2034
Figure 15: Orchard Road Singapore Hospitality Industry Revenue Share (%), by Accommodation Class 2026 & 2034
Figure 16: Orchard Road Singapore Hospitality Industry Revenue (Billion), by Booking Channel 2026 & 2034
Figure 17: Orchard Road Singapore Hospitality Industry Revenue Share (%), by Booking Channel 2026 & 2034
Figure 18: Orchard Road Singapore Hospitality Industry Revenue (Billion), by Geography 2026 & 2034
Figure 19: Orchard Road Singapore Hospitality Industry Revenue Share (%), by Geography 2026 & 2034
Figure 20: Orchard Road Singapore Hospitality Industry Revenue (Billion), by Country 2026 & 2034
Figure 21: Orchard Road Singapore Hospitality Industry Revenue Share (%), by Country 2026 & 2034
Figure 22: Sentosa & Southern Waterfront Singapore Hospitality Industry Revenue (Billion), by Type 2026 & 2034
Figure 23: Sentosa & Southern Waterfront Singapore Hospitality Industry Revenue Share (%), by Type 2026 & 2034
Figure 24: Sentosa & Southern Waterfront Singapore Hospitality Industry Revenue (Billion), by Accommodation Class 2026 & 2034
Figure 25: Sentosa & Southern Waterfront Singapore Hospitality Industry Revenue Share (%), by Accommodation Class 2026 & 2034
Figure 26: Sentosa & Southern Waterfront Singapore Hospitality Industry Revenue (Billion), by Booking Channel 2026 & 2034
Figure 27: Sentosa & Southern Waterfront Singapore Hospitality Industry Revenue Share (%), by Booking Channel 2026 & 2034
Figure 28: Sentosa & Southern Waterfront Singapore Hospitality Industry Revenue (Billion), by Geography 2026 & 2034
Figure 29: Sentosa & Southern Waterfront Singapore Hospitality Industry Revenue Share (%), by Geography 2026 & 2034
Figure 30: Sentosa & Southern Waterfront Singapore Hospitality Industry Revenue (Billion), by Country 2026 & 2034
Figure 31: Sentosa & Southern Waterfront Singapore Hospitality Industry Revenue Share (%), by Country 2026 & 2034
Figure 32: Bugis & Little India Singapore Hospitality Industry Revenue (Billion), by Type 2026 & 2034
Figure 33: Bugis & Little India Singapore Hospitality Industry Revenue Share (%), by Type 2026 & 2034
Figure 34: Bugis & Little India Singapore Hospitality Industry Revenue (Billion), by Accommodation Class 2026 & 2034
Figure 35: Bugis & Little India Singapore Hospitality Industry Revenue Share (%), by Accommodation Class 2026 & 2034
Figure 36: Bugis & Little India Singapore Hospitality Industry Revenue (Billion), by Booking Channel 2026 & 2034
Figure 37: Bugis & Little India Singapore Hospitality Industry Revenue Share (%), by Booking Channel 2026 & 2034
Figure 38: Bugis & Little India Singapore Hospitality Industry Revenue (Billion), by Geography 2026 & 2034
Figure 39: Bugis & Little India Singapore Hospitality Industry Revenue Share (%), by Geography 2026 & 2034
Figure 40: Bugis & Little India Singapore Hospitality Industry Revenue (Billion), by Country 2026 & 2034
Figure 41: Bugis & Little India Singapore Hospitality Industry Revenue Share (%), by Country 2026 & 2034
Figure 42: Changi & East Coast Singapore Hospitality Industry Revenue (Billion), by Type 2026 & 2034
Figure 43: Changi & East Coast Singapore Hospitality Industry Revenue Share (%), by Type 2026 & 2034
Figure 44: Changi & East Coast Singapore Hospitality Industry Revenue (Billion), by Accommodation Class 2026 & 2034
Figure 45: Changi & East Coast Singapore Hospitality Industry Revenue Share (%), by Accommodation Class 2026 & 2034
Figure 46: Changi & East Coast Singapore Hospitality Industry Revenue (Billion), by Booking Channel 2026 & 2034
Figure 47: Changi & East Coast Singapore Hospitality Industry Revenue Share (%), by Booking Channel 2026 & 2034
Figure 48: Changi & East Coast Singapore Hospitality Industry Revenue (Billion), by Geography 2026 & 2034
Figure 49: Changi & East Coast Singapore Hospitality Industry Revenue Share (%), by Geography 2026 & 2034
Figure 50: Changi & East Coast Singapore Hospitality Industry Revenue (Billion), by Country 2026 & 2034
Figure 51: Changi & East Coast Singapore Hospitality Industry Revenue Share (%), by Country 2026 & 2034
Figure 52: Western & North-Eastern Region Singapore Hospitality Industry Revenue (Billion), by Type 2026 & 2034
Figure 53: Western & North-Eastern Region Singapore Hospitality Industry Revenue Share (%), by Type 2026 & 2034
Figure 54: Western & North-Eastern Region Singapore Hospitality Industry Revenue (Billion), by Accommodation Class 2026 & 2034
Figure 55: Western & North-Eastern Region Singapore Hospitality Industry Revenue Share (%), by Accommodation Class 2026 & 2034
Figure 56: Western & North-Eastern Region Singapore Hospitality Industry Revenue (Billion), by Booking Channel 2026 & 2034
Figure 57: Western & North-Eastern Region Singapore Hospitality Industry Revenue Share (%), by Booking Channel 2026 & 2034
Figure 58: Western & North-Eastern Region Singapore Hospitality Industry Revenue (Billion), by Geography 2026 & 2034
Figure 59: Western & North-Eastern Region Singapore Hospitality Industry Revenue Share (%), by Geography 2026 & 2034
Figure 60: Western & North-Eastern Region Singapore Hospitality Industry Revenue (Billion), by Country 2026 & 2034
Figure 61: Western & North-Eastern Region Singapore Hospitality Industry Revenue Share (%), by Country 2026 & 2034
Figure 62: Southern Islands & Outer Regions Singapore Hospitality Industry Revenue (Billion), by Type 2026 & 2034
Figure 63: Southern Islands & Outer Regions Singapore Hospitality Industry Revenue Share (%), by Type 2026 & 2034
Figure 64: Southern Islands & Outer Regions Singapore Hospitality Industry Revenue (Billion), by Accommodation Class 2026 & 2034
Figure 65: Southern Islands & Outer Regions Singapore Hospitality Industry Revenue Share (%), by Accommodation Class 2026 & 2034
Figure 66: Southern Islands & Outer Regions Singapore Hospitality Industry Revenue (Billion), by Booking Channel 2026 & 2034
Figure 67: Southern Islands & Outer Regions Singapore Hospitality Industry Revenue Share (%), by Booking Channel 2026 & 2034
Figure 68: Southern Islands & Outer Regions Singapore Hospitality Industry Revenue (Billion), by Geography 2026 & 2034
Figure 69: Southern Islands & Outer Regions Singapore Hospitality Industry Revenue Share (%), by Geography 2026 & 2034
Figure 70: Southern Islands & Outer Regions Singapore Hospitality Industry Revenue (Billion), by Country 2026 & 2034
Figure 71: Southern Islands & Outer Regions Singapore Hospitality Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Singapore Hospitality Industry Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Global Singapore Hospitality Industry Revenue Billion Forecast, by Accommodation Class 2020 & 2034
Table 3: Global Singapore Hospitality Industry Revenue Billion Forecast, by Booking Channel 2020 & 2034
Table 4: Global Singapore Hospitality Industry Revenue Billion Forecast, by Geography 2020 & 2034
Table 5: Global Singapore Hospitality Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 6: Marina Bay & Downtown Core Singapore Hospitality Industry Revenue Billion Forecast, by Type 2020 & 2034
Table 7: Marina Bay & Downtown Core Singapore Hospitality Industry Revenue Billion Forecast, by Accommodation Class 2020 & 2034
Table 8: Marina Bay & Downtown Core Singapore Hospitality Industry Revenue Billion Forecast, by Booking Channel 2020 & 2034
Table 9: Marina Bay & Downtown Core Singapore Hospitality Industry Revenue Billion Forecast, by Geography 2020 & 2034
Table 10: Marina Bay & Downtown Core Singapore Hospitality Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 11: Orchard Road Singapore Hospitality Industry Revenue Billion Forecast, by Type 2020 & 2034
Table 12: Orchard Road Singapore Hospitality Industry Revenue Billion Forecast, by Accommodation Class 2020 & 2034
Table 13: Orchard Road Singapore Hospitality Industry Revenue Billion Forecast, by Booking Channel 2020 & 2034
Table 14: Orchard Road Singapore Hospitality Industry Revenue Billion Forecast, by Geography 2020 & 2034
Table 15: Orchard Road Singapore Hospitality Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 16: Sentosa & Southern Waterfront Singapore Hospitality Industry Revenue Billion Forecast, by Type 2020 & 2034
Table 17: Sentosa & Southern Waterfront Singapore Hospitality Industry Revenue Billion Forecast, by Accommodation Class 2020 & 2034
Table 18: Sentosa & Southern Waterfront Singapore Hospitality Industry Revenue Billion Forecast, by Booking Channel 2020 & 2034
Table 19: Sentosa & Southern Waterfront Singapore Hospitality Industry Revenue Billion Forecast, by Geography 2020 & 2034
Table 20: Sentosa & Southern Waterfront Singapore Hospitality Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 21: Bugis & Little India Singapore Hospitality Industry Revenue Billion Forecast, by Type 2020 & 2034
Table 22: Bugis & Little India Singapore Hospitality Industry Revenue Billion Forecast, by Accommodation Class 2020 & 2034
Table 23: Bugis & Little India Singapore Hospitality Industry Revenue Billion Forecast, by Booking Channel 2020 & 2034
Table 24: Bugis & Little India Singapore Hospitality Industry Revenue Billion Forecast, by Geography 2020 & 2034
Table 25: Bugis & Little India Singapore Hospitality Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 26: Changi & East Coast Singapore Hospitality Industry Revenue Billion Forecast, by Type 2020 & 2034
Table 27: Changi & East Coast Singapore Hospitality Industry Revenue Billion Forecast, by Accommodation Class 2020 & 2034
Table 28: Changi & East Coast Singapore Hospitality Industry Revenue Billion Forecast, by Booking Channel 2020 & 2034
Table 29: Changi & East Coast Singapore Hospitality Industry Revenue Billion Forecast, by Geography 2020 & 2034
Table 30: Changi & East Coast Singapore Hospitality Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 31: Western & North-Eastern Region Singapore Hospitality Industry Revenue Billion Forecast, by Type 2020 & 2034
Table 32: Western & North-Eastern Region Singapore Hospitality Industry Revenue Billion Forecast, by Accommodation Class 2020 & 2034
Table 33: Western & North-Eastern Region Singapore Hospitality Industry Revenue Billion Forecast, by Booking Channel 2020 & 2034
Table 34: Western & North-Eastern Region Singapore Hospitality Industry Revenue Billion Forecast, by Geography 2020 & 2034
Table 35: Western & North-Eastern Region Singapore Hospitality Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 36: Southern Islands & Outer Regions Singapore Hospitality Industry Revenue Billion Forecast, by Type 2020 & 2034
Table 37: Southern Islands & Outer Regions Singapore Hospitality Industry Revenue Billion Forecast, by Accommodation Class 2020 & 2034
Table 38: Southern Islands & Outer Regions Singapore Hospitality Industry Revenue Billion Forecast, by Booking Channel 2020 & 2034
Table 39: Southern Islands & Outer Regions Singapore Hospitality Industry Revenue Billion Forecast, by Geography 2020 & 2034
Table 40: Southern Islands & Outer Regions Singapore Hospitality Industry Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1How big is the Singapore hospitality industry market?
The Singapore hospitality industry market was valued at **USD 21.87 billion in 2025** and is estimated at **USD 23.28 billion in 2026**. Our forecasts project it to reach **USD 32.46 billion by 2031**.
2What is the growth rate of the Singapore hospitality market?
The market is expanding at a **CAGR of 6.87%** over the 2026–2031 forecast period, supported by MICE recovery, integrated resort investment and serviced apartment demand.
3Which segment leads the Singapore hospitality market by type?
Chain hotels led with **61.65% of market share in 2025**, while serviced apartments are the fastest-growing segment at a **9.76% CAGR through 2031**.
4Which region dominates Singapore hospitality demand?
Marina Bay and Downtown Core accounted for **38.77% of market share in 2025**, while Changi and East Coast are projected to grow fastest at an **8.66% CAGR**.
5What booking channel is growing fastest in Singapore hospitality?
OTAs captured **52.77% of share in 2025**, but direct digital booking is projected to grow at a **12.68% CAGR through 2031** as brands invest in loyalty and AI-enabled concierge.
6Who are the key players in the Singapore hospitality market?
Leading operators include Marriott International, Hilton Worldwide, Accor, Shangri-La Hotels and Resorts, IHG Hotels & Resorts, Pan Pacific Hotels Group and The Ascott Limited.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Between 70% and 80% of every engagement is built on primary research, including structured interviews, executive briefings and proprietary operator panels conducted specifically for the Singapore hospitality industry market.
We interview hotel general managers and asset managers, revenue and distribution directors, serviced-residence and co-living operators, MICE and event venue commercial leads, and hotel investment and development heads.
Stakeholder job titles sampled include Chief Commercial Officer, VP Revenue Strategy, Director of Sales & Marketing, Head of Asset Management, and Development Director.
All interview outputs are cross-validated against published operational disclosures and statutory filings, with a guaranteed estimated data accuracy level of 85–90%.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Commercial Officer / VP Revenue Strategy
30%
General Manager / Hotel Manager
28%
Director of Sales & Marketing
22%
Head of Asset Management / Development Director
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Hotel owners and operators (chain and independent)
34%
Serviced apartment and co-living operators
18%
OTA and travel distribution platforms
15%
MICE, venue and events organisers
13%
Hotel investment, development and asset management firms
Financial databases employed include Bloomberg, Factiva, Hoovers and PitchBook for corporate filings, ownership structures, transaction values and capital expenditure benchmarks.
Trade and association data from non-profit technical bodies are used to benchmark service standards, sustainability certification adoption and labour productivity.
Every report is updated to the date of purchase, incorporating the latest arrivals, RevPAR and pipeline disclosures.
Demand Modeling & Market Estimation
We run top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation across property-level, portfolio-level and national aggregates.
The bottom-up calculation combines room-night inventory by accommodation class, achieved average room rate, occupancy percentage, and ancillary F&B and MICE revenue per occupied room.
Model inputs are reconciled against international visitor arrivals, tourism receipts, pipeline room additions (1.6% CAGR 2026–2028) and segment-level CAGR estimates.
Sensitivity scenarios test arrival growth shocks, rate compression and event-calendar concentration to produce defensible forecast ranges.
Data Accuracy & Quality Check
Every dataset passes a three-stage validation: source verification, cross-database reconciliation, and senior analyst sign-off.
We enforce a guaranteed estimated data accuracy level of 85–90%, with outlier detection applied to occupancy, rate and pipeline inputs.
Segment shares are normalised to sum to 100% across type, accommodation class, booking channel and micro-market geography.
Final figures are reviewed against official tourism receipts and arrivals benchmarks before release.