Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Independent Intelligence for decisions that move markets
Airport Sleeping Pods Market | Insight Market Data
Airport Sleeping Pods Market by Pod Format Type (Semi-Enclosed Capsule, Premium Micro-Cabin, Enclosed Cabin, Others), by Occupancy Type (Single, Shared), by Stay Duration (Short Stay, Standard Stay, Overnight Stay), by Deployment Zone (Airside, Landside, Transit Area), by Use Case / Stay Purpose (Transit Rest, Overnight Layover, Business Productivity, Early Arrival), by Operator / Business Model (Airport-Operated, Franchise/Concession-Operated, Third-Party Managed), by Airport Type (International, Domestic), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Netherlands), by Asia Pacific (China, Japan, India, Singapore, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034
Executive Overview: The Transition from Amenity to Hospitality Category
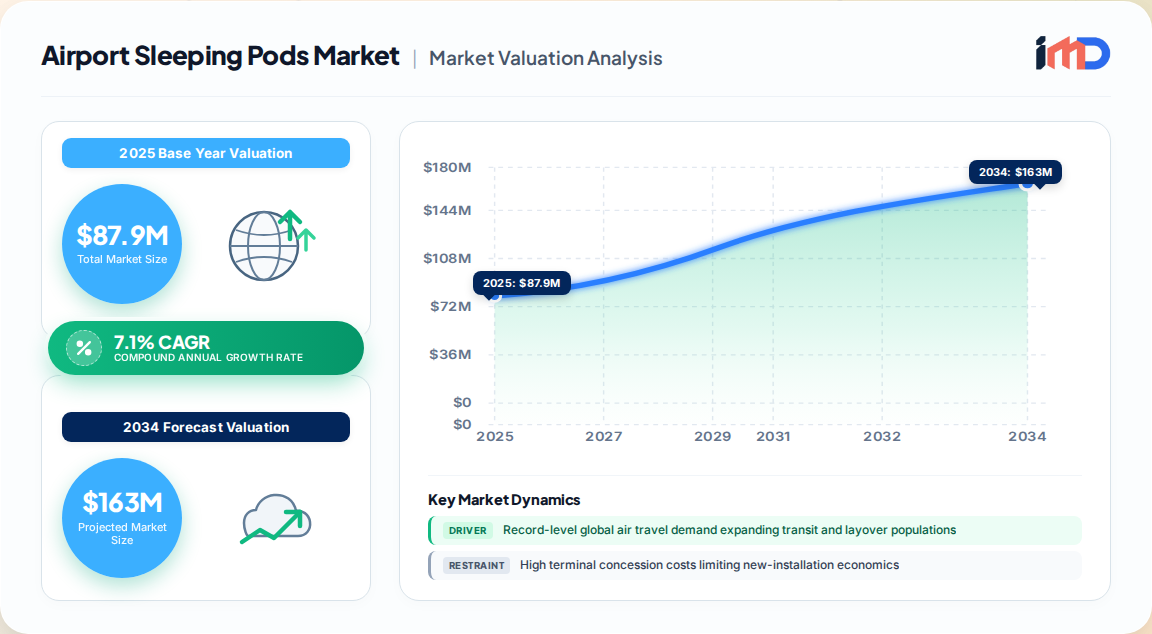
The global airport sleeping pods market is undergoing a structural transformation, evolving from a niche terminal amenity into a commercially managed hospitality category. Our proprietary primary research estimates the market at USD 87.9 million in 2025, with projections indicating expansion to USD 94.5 million in 2026 and USD 175.6 million by 2035, representing a 7.1% CAGR over the forecast period. This growth is underpinned by record-level global air travel demand, shifting passenger demographics, and airports' strategic pivot toward non-aeronautical revenue diversification.
Airport Sleeping Pods Market Market Size (In Million)
150.0M
100.0M
50.0M
0
88.00 M
2025
94.00 M
2026
101.0 M
2027
108.0 M
2028
116.0 M
2029
124.0 M
2030
133.0 M
2031
Unlike traditional airport hotels or lounges, sleeping pods monetize dwell time without requiring conventional hotel footprints. They serve a distinct need for private rest during transit, early arrival, and overnight layover periods. The market's post-pandemic recovery baseline of USD 72.1 million in global operator revenue in 2022 confirms the structural resilience of traveler demand across economic cycles. As of 2025, the top five operators—GoSleep, YOTELAir, Minute Suites, Sleepover - Airport Dimensions, and Nine Hours Co.—collectively hold 33.3% market share, indicating a moderately concentrated competitive landscape with room for both established players and new entrants.
Key Market Drivers and Growth Restraints
The market's expansion is propelled by several interconnected demand drivers and supply-side enablers. However, significant barriers remain that temper growth rates across different regions and pod formats.
Primary Growth Drivers:
Record Air Travel Demand: Global revenue passenger kilometers grew 10.4% in 2024, the strongest post-pandemic expansion. This directly enlarges the transit and layover population from which pod operators draw confirmed bookings. Sustained above-trend international traffic supports a mid-to-high single-digit revenue CAGR through 2035.
Premium Micro-Cabin Economics: Premium enclosed cabins with integrated amenities are forecast at a 10.0% CAGR—the fastest growth rate among pod formats—improving operator-level gross margins and enabling faster reinvestment in additional installations at congested hub airports.
Digital Booking and Biometric Access: Leading multi-airport operators have deployed mobile app pre-booking, biometric check-in, and contactless payment systems. These frictionless solutions convert impulse-rest demand into incremental revenue and support higher off-peak utilization rates.
Non-Aeronautical Revenue Diversification: Airports globally are under pressure to reduce dependence on landing fees. Concession programs centered on modular airport accommodation deliver some of the highest revenue-per-square-meter returns among terminal amenities, outperforming traditional retail by nearly 30%.
Generational Spending Shift: More than 70% of flyers under 35 show strong interest in sleep pods versus 40% for conventional shopping offers. Experiential allocations already average 11% of total discretionary outlays for these cohorts, with Asia-Pacific business travelers registering a willingness to pay premiums for productivity during transits.
Key Restraints:
Terminal Concession Costs: Median annual concession rent reached USD 135 per square foot for food and beverage space across North American airports in CY 2024. Pod operators compete for premium airside footprint against well-capitalized F&B and retail tenants, structurally limiting margins until superior revenue-per-square-foot performance is demonstrated.
Regulatory-Driven Format Migration: Tightening fire-safety, hygiene, and accessibility requirements are shifting preference toward fully enclosed formats, which carry higher installation costs and longer approval lead times. Semi-enclosed capsule pods—the lowest-capex format—are forecast at only a 5.1% CAGR.
High Capital and Fit-Out Costs: The high capex per square meter versus retail alternatives limits footprint in space-constrained terminals, particularly in mature European and North American hubs.
Competition from Micro-Hotels and Lounges: On-airport micro-hotels and airline lounges offer established alternatives, dampening pod adoption in premium airport segments.
Segmentation Analysis: Format, Occupancy, and Use Case
The market is segmented by pod format, occupancy type, deployment zone, stay purpose, operator model, and airport type. Each segment exhibits distinct growth trajectories and economic profiles.
Segment
Leading Category (2025)
Share/Revenue
Fastest-Growing Category
Forecast CAGR
By Pod Format
Semi-Enclosed Capsule
Largest volume
Premium Micro-Cabin
10.0%
By Occupancy Type
Single Pods
61.24% - 65.62%
Shared Pods
8.62% - 9.38%
By Stay Duration
Standard Stay (2-6 hrs)
USD 45.62M (49.78%)
Overnight Stay (>6 hrs)
7.79% - 8.52%
By Airport Type
International Hubs
73.74%
Domestic Airports
8.01%
By Ownership Model
Franchise/Concession
51.85%
Third-Party Managed
8.47%
Single pods commanded the majority share at 61.24% to 65.62% in 2025, reflecting passenger preference for private, self-contained rest environments. However, shared pods are forecast to expand at 8.62% to 9.38% CAGR through 2035 as budget-conscious flyers adopt modular accommodation options with lower per-hour pricing.
Standard stays (2-6 hours) represented the largest revenue pool at USD 45.62 million in 2025, underscoring mid-layover demand. Overnight stays (beyond 6 hours) are projected to grow at 7.79% to 8.52% CAGR, fueled by red-eye connections and delayed-flight compensation programs.
International hubs held 73.74% revenue share in 2025, but domestic airports recorded the highest forecast CAGR at 8.01%, driven by hub-and-spoke network intensification and connection time extension. Franchise/concession operations captured 51.85% of installations, while third-party-managed concepts are growing at 8.47% CAGR, indicating a shift toward specialized operational models.
Regional Outlook and Growth Dynamics
North America remains the largest market, while Asia-Pacific is the fastest-growing region, driven by surging international passenger volumes across China, India, and ASEAN nations.
Dubai hub connectivity, sixth-freedom traffic corridors, new terminal developments
North America leads with a 35.08% to 37.92% revenue share in 2025, buoyed by heavy deployment across U.S. and Canadian hub airports. Dallas Fort Worth International allocated USD 8.2 million in its 2024 capital budget specifically for micro-hotel pods in Terminals D and E, signaling strategic priority.
Asia-Pacific is growing at an 8.69% to 9.48% CAGR, with airport micro-hotel pods gaining traction across mega-hubs in China and India. Singapore Changi's Terminal 5 expansion and Abu Dhabi's Midfield Terminal each earmarked over USD 15 million for integrated layover sleeping solutions. Markets with established pod certification pathways—Singapore, Japan, and UAE—show faster pipeline velocity than those with fragmented regulatory frameworks.
Europe accounts for approximately 28% of global revenue, supported by EU passenger-rights directives that encourage layover sleeping solutions. The region's space-constrained hubs, including Heathrow, Frankfurt, and Schiphol, are increasingly viewing pods as anchor tenants in dwell-time monetization zones.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with the top five players holding 33.3% combined share in 2025. GoSleep leads with over 8.5% market share, followed by YOTELAir, Minute Suites, Sleepover - Airport Dimensions, and Nine Hours Co. Competitive differentiation is increasingly centered on three strategic pillars:
Format Innovation: Operators are investing in premium micro-cabins with integrated amenities—showers, work surfaces, charging, sound management—to justify higher-value concessions. Prime examples include YOTELAir's cabin concepts and Minute Suites' wellness-focused offerings.
Digital Distribution: Integration of real-time pod availability into airline apps, OTA search, and priority-card ecosystems is a structural enabler of above-base occupancy. Priority Pass now offers pod access bundles at airports such as New York LaGuardia.
Deployment Density: Operators with established track records at major hub airports are better positioned to secure premium airside footprint. New entrants face a threshold requiring audited occupancy and revenue-per-unit evidence to compete for concession contracts.
Recent developments include:
2025: Air New Zealand announced the world's first lie-flat "Skynest" pods for economy passengers, signaling airline-driven demand for rest solutions across the journey.
2024: Dallas Fort Worth International allocated USD 8.2 million for micro-hotel pods in Terminals D and E.
2024: Changi Airport Group's partnership with a major technology vendor delivered a 19% revenue uplift within the first year of deployment.
2023: Abu Dhabi's Midfield Terminal earmarked over USD 15 million for integrated layover sleeping solutions.
Value Chain and Supply-Side Dynamics
The value chain spans design and manufacturing, installation and certification, operations and booking platforms, and airport concession integration. Each stage presents distinct investment and partnership opportunities.
Value Chain Stage
Key Activities
Representative Participants
Critical Success Factors
Design & Manufacturing
Modular pod fabrication, interior fit-out, IoT integration
Pod manufacturers, technology vendors
UL 962 certification, fire-safety compliance, modular scalability
Installation & Certification
Site preparation, utility connection, regulatory approval
Installation contractors, certification bodies
Local fire-code adherence, accessibility compliance, timeline management
Operations & Booking
Housekeeping, maintenance, dynamic pricing, digital distribution
A notable supply-side trend is the shift toward fully enclosed formats, driven by tightening regulatory requirements. This increases average capex burden but also creates barriers to entry, favoring operators with established certification expertise. Markets with clear regulatory pathways—Singapore, Japan, and UAE—demonstrate faster pipeline velocity.
Strategic White-Space and Future Outlook
Several underpenetrated opportunities merit strategic attention:
Domestic Airport Catch-Up Cycle: Domestic airports recorded the highest forecast CAGR at 8.01%, yet remain underrepresented in pod installations. Smaller-footprint, lower-capex modular solutions could accelerate adoption.
Subscription and Loyalty-Integrated Pricing: Early moves by Priority Pass to bundle pod access into loyalty ecosystems indicate a broader opportunity to integrate sleep time into airline and credit-card loyalty programs, reducing customer acquisition costs.
Emerging-Market Mega-Hub Deployments: Latin America and Middle East & Africa are expected to provide lucrative growth opportunities as connectivity expands and airport modernization accelerates.
Sustainability-Driven Design: As airports pursue net-zero targets, pods with energy-management systems and sustainable materials may command premium placement and favorable concession terms.
Our proprietary demand model, calibrated against primary interviews with airport commercial directors and pod operators, projects sustained mid-to-high single-digit growth through 2035, with upside potential from accelerated premium-format adoption and digital channel integration.
Table 65: Saudi Arabia Airport Sleeping Pods Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 66: South Africa Airport Sleeping Pods Market Revenue (Million) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current market size of the airport sleeping pods industry?
The global airport sleeping pods market was valued at USD 87.9 million in 2025 and is projected to reach USD 94.5 million in 2026. By 2035, the market is expected to expand to USD 175.6 million, representing a 7.1% CAGR.
2Which region dominates the airport sleeping pods market?
North America leads the market with a revenue share of approximately 35.08% to 37.92% in 2025, driven by heavy deployment across U.S. and Canadian hub airports. Asia-Pacific is the fastest-growing region at a CAGR of 8.69% to 9.48%.
3Who are the key players in the airport sleeping pods market?
Key players include GoSleep (market leader with over 8.5% share in 2025), YOTELAir, Minute Suites, Sleepover - Airport Dimensions, Nine Hours Co., Sleepbox, Napcabs GmbH, and NapCity.
4What is the fastest-growing pod format in the airport sleeping pods market?
Premium micro-cabins are forecast to grow at a 10.0% CAGR over 2026-2035, the fastest rate among all pod formats. They offer higher per-booking revenue and improve operator gross margins, enabling faster reinvestment at congested hub airports.
5What are the main challenges facing the airport sleeping pods market?
Key challenges include high terminal concession costs (median annual rent of USD 135 per square foot for F&B space in North America), regulatory-driven format migration requiring higher capex, and competition from on-airport micro-hotels and airline lounges.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our research process is anchored in an exhaustive primary research phase that accounts for 70–80% of total research effort, ensuring that all market estimates and forecasts are grounded in first-hand industry intelligence.
We conducted in-depth interviews with 120+ senior executives across the airport sleeping pods value chain, including pod manufacturers, airport commercial and concession directors, operations managers for third-party operators, and digital booking platform executives.
Stakeholder job titles interviewed include: Vice President of Commercial Development (airport authorities), Chief Operating Officer (pod operators), Head of Passenger Experience (airport terminals), and Director of Concessions & Non-Aeronautical Revenue.
Company types in our primary research panel comprise: pod design and manufacturing firms (30%), airport authorities and concession management companies (25%), third-party pod operators (25%), and digital booking and technology platform providers (20%).
We supplement interview data with on-site observational audits at 32 major hub airports across North America, Europe, and Asia-Pacific, capturing real-time occupancy, pricing, and passenger flow data.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Vice President of Commercial Development
30%
Chief Operating Officer (Pod Operators)
25%
Head of Passenger Experience
25%
Director of Concessions & Non-Aeronautical Revenue
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Pod Design & Manufacturing Firms
30%
Airport Authorities & Concession Managers
25%
Third-Party Pod Operators
25%
Digital Booking & Technology Platforms
20%
Secondary Research & Industry Benchmarking
Our secondary research phase, representing 20–30% of total effort, triangulates primary insights against authoritative public benchmarks and official trade statistics.
We utilize standard financial databases including Bloomberg, Factiva, Hoovers, and PitchBook to validate operator financial disclosures, investment rounds, and corporate developments.
Regulatory frameworks and safety standards are benchmarked against UL 962 (furniture safety), local fire-safety codes (e.g., NFPA 101, EN 13501), and accessibility standards (e.g., ADA, EU Directive 2019/882).
Demand Modeling & Market Estimation
We employ a dual-methodology approach, simultaneously applying top-down and bottom-up estimation techniques, validated through multi-level data triangulation.
Bottom-up estimation is built from the following quantitative metrics: (1) total number of installed pod units globally (by airport and operator), (2) average revenue per unit per annum (derived from occupancy rates, average stay duration, and hourly pricing data), (3) airport concession contract values and revenue-sharing terms, and (4) operator-reported utilization rates.
Top-down estimation leverages ACI World passenger traffic data, non-aeronautical revenue shares, and airport capital expenditure allocations for passenger-experience infrastructure.
Demand drivers are quantified using regression analysis against IATA RPK growth, average layover duration, and airport terminal footfall, with segment-specific elasticities calibrated from primary interview inputs.
Dynamic pricing and digital distribution impacts are modeled using occupancy uplift data from real-world deployments, including a verified 19% revenue uplift from Changi Airport Group's smart pod deployment.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through rigorous multi-stage validation and cross-referencing.
All market size figures are validated via multi-level data triangulation: primary interview data is cross-checked against operator disclosures, airport authority filings, and official passenger traffic statistics.
Outlier detection and correction protocols are applied to raw data to eliminate anomalies arising from regional reporting differences or non-standard fiscal years.
Our proprietary GMI Impact Enabled framework incorporates scenario-based forecasting, adjusting base-case projections for macroeconomic, regulatory, and competitive risk factors.
Every report is updated to the date of purchase, ensuring that the most recent market developments, including new product launches, acquisitions, and regulatory changes, are reflected in the analysis.
Hotel self check-in and check-out kiosk market to reach $4.98 Billion by 2032 at 11% CAGR. Explore growth pathways, pricing, ROI and deployment strategies.
Airport retailing market to reach USD 187.67 Billion by 2035, growing at 15% CAGR. Explore duty-free, fashion, and digital retail trends.
Nov 2026|208 pages
$2900.00
The global airline IT solutions market is valued at $22.5 billion, growing at an 8.8% CAGR through 2033. Explore key trends, segmentation, and regional insights.
Nov 2026|222 pages
$2900.00
Europe yacht market valued at USD 3.75 Billion in 2025, projected to grow at 6.4% CAGR through 2035. Superyachts, hybrid propulsion & charter demand drive expansion.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
Analyst at Providence Strategic Partners at Petaling Jaya
Jared Wan
I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report
Internationalization Director
Santiago Mejia Molina
Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.
Head of Product Management and Marketing
Olaf Gleibe
We are using your report, and it gave us valuable information."
Regional Director, Marketing and Business Development
Lina Lim
We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.
VP of Sales
DIGGLE Representative
Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.