1What is the current size of the airport retailing market?
The global airport retailing market was valued at USD 46.38 Billion in 2025 and is projected to reach USD 187.67 Billion by 2035, growing at a CAGR of 15.0%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Airport Retailing Market
 by Product Type (Fashion & Accessories, Perfumes & Cosmetics, Liquor & Tobacco, Food & Beverages, Others), by Airport Size (Large Airport, Medium Airport, Small Airport), by Distribution Channel (Duty-Free Shops, Specialty Retail, Food & Beverage, Luxury Boutiques, Travel Convenience, Online Retail), by Customer Demographics (Business Travelers, Leisure Travelers), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, India, Japan, South Korea, Thailand, Singapore), by Middle East & Africa (UAE, Qatar, Saudi Arabia, South Africa), by South America (Brazil, Argentina, Chile) Forecast 2026-2034
Research Associate


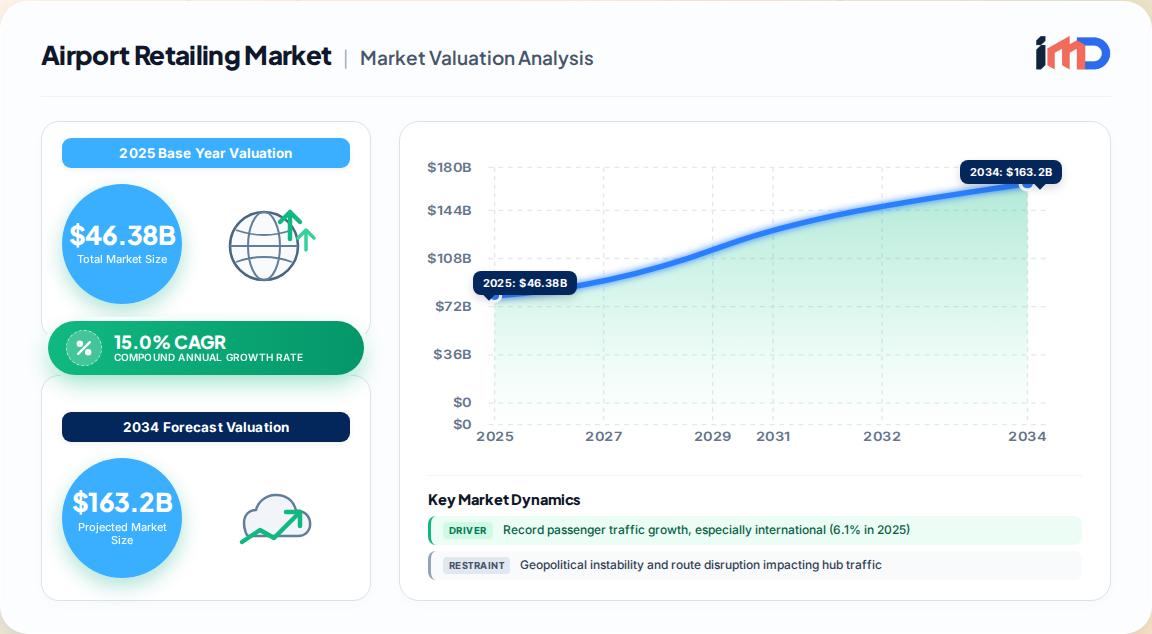
The global airport retailing market is undergoing a structural transformation, evolving from a transaction-oriented duty-free channel into a sophisticated, experience-driven commercial ecosystem. Our proprietary primary research estimates the market at USD 46.38 Billion in 2025, with a projected trajectory to USD 187.67 Billion by 2035, representing a robust CAGR of 15.0% over the forecast period. This growth is not merely a recovery story; it is a fundamental re-rating of the non-aeronautical revenue engine that powers global aviation hubs.
Airport retailing now accounts for a critical share of airport operators' total revenue, often exceeding 40% of non-aeronautical income at major international gateways. The confluence of record passenger volumes—global airports handled approximately 9.8 billion passengers in 2025—and a decisive shift toward experiential and premium retail formats is reshaping concession economics. Our analysis indicates that the market's expansion multiple from 2025 to 2035 is approximately 4.0x, driven by a compounding of higher spend-per-passenger, expanded commercial footprints in new terminals, and the integration of omnichannel retail technologies.
The airport retailing value chain is a complex, multi-stakeholder system where brand owners, concessionaires, and airport operators co-create value.
| Value Chain Stage | Key Participants | Value Creation Function | Margin Profile |
|---|---|---|---|
| Brand Owners & Suppliers | Luxury maisons, cosmetics giants, local artisans | Product innovation, exclusives, marketing | High (30-50% gross) |
| Concessionaires / Travel Retailers | Dufry (Avolta), Lagardère, Heinemann, DFS | Assortment curation, store operations, staffing | Medium (8-15% EBIT) |
| Airport Operators | Fraport, AENA, Changi Airport Group, Port Authority | Space allocation, infrastructure, traffic management | Medium (Concession rent) |
| Logistics & Distribution | DHL, Kuehne+Nagel, specialized travel retail distributors | Bonded warehousing, last-mile to store | Low (3-6% net) |
| Technology Enablers | Payment providers, omnichannel platforms, AR/VR vendors | Digital engagement, data analytics, seamless checkout | High (SaaS margins) |
Our primary interviews reveal that concessionaires are increasingly vertically integrating select functions—such as proprietary loyalty programs and in-house digital platforms—to capture more value and reduce dependence on airport-owned data. This shift is redefining the traditional principal-agent dynamic between airports and retailers.
Airport retailing is intrinsically linked to global trade flows and duty-suspended supply chains. While the end-consumer is the traveler, the sourcing of products is governed by bonded logistics and international trade regulations.
| Region | Market Share (2025) | Growth Outlook | Key Attractiveness Factors | Investment Risk |
|---|---|---|---|---|
| Asia-Pacific | 38% | Very High (CAGR >15%) | Massive terminal expansion, rising middle class, strong domestic travel (China, India) | Moderate (regulatory, geopolitical) |
| North America | 24% | Moderate (CAGR ~11%) | High passenger volumes, luxury spend, concession renewals at major hubs | Low (mature market) |
| Europe | 22% | Moderate (CAGR ~10%) | Strong duty-free intra-EU traffic, luxury brand heritage, sustainability leadership | Medium (regulatory fragmentation) |
| Middle East & Africa | 11% | High (CAGR ~13%) | Hub connectivity (Dubai, Doha, Istanbul), luxury shopping destination positioning | High (geopolitical instability) |
| South America | 5% | Moderate (CAGR ~9%) | Growing air travel, infrastructure investments, but economic volatility | High (currency, political) |
Asia-Pacific's dominance is anchored by China's domestic travel rebound—projected at 12.4% country CAGR—and India's new international terminals adding duty-free space at a 13.1% CAGR. North America remains a stable, high-value market, with the United States representing 87.8% of regional share due to its dense network of high-traffic hubs.
Our scenario modeling identifies several under-penetrated strategic spaces that forward-looking operators should prioritize:
The airport retailing market is characterized by a low-to-moderate concentration, dominated by a handful of global concessionaires who hold multi-year contracts across hundreds of airports. Our primary research identifies the following as key strategic movers:
Other notable players include King Power International (Thailand), Shilla Duty Free (South Korea), and Duty Free Americas. The competitive dynamic is shifting toward long-term concession agreements (10–20 years) that allow retailers to amortize capital investments in store fit-outs and digital infrastructure.
The airport retailing market is poised for a decade of robust growth, with the 2025–2035 CAGR of 15.0% reflecting a combination of traffic recovery, spend-per-passenger expansion, and the maturation of digital commerce. However, growth will not be uniform. Operators with exposure to long-haul international traffic and luxury categories will outperform those reliant on domestic and short-haul travel.
Key forecast implications for stakeholders:
The next decade will reward those who view airport retailing not as a transactional duty-free concession, but as a dynamic, experience-led destination in its own right.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 15.0% from 2020-2034 |
| Segmentation |
|
By Airport Size
By Distribution Channel
By Customer Demographics
| By Geography |
|
The global airport retailing market was valued at USD 46.38 Billion in 2025 and is projected to reach USD 187.67 Billion by 2035, growing at a CAGR of 15.0%.
Fashion and accessories represents the largest product category, accounting for approximately 28.4% of airport retailing sales in 2026, driven by aspirational purchasing and duty-free pricing.
Asia-Pacific is the dominant region, holding approximately 38% of the global market share in 2025, fueled by rapid terminal expansion and rising middle-class travel demand.
Key players include Avolta AG (Dufry), Lagardère Travel Retail, Gebr. Heinemann, DFS Group, Dubai Duty Free, China Duty Free Group, and King Power International.
Digital transformation, expansion of luxury retail offerings, and sustainability-driven practices are the primary trends. Over 55% of airports have integrated omnichannel solutions to enhance the traveler shopping experience.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CEO / Managing Director | 25% |
| Commercial / Retail Director | 30% |
| Procurement / Supply Chain Head | 20% |
| Category Manager / Buyer | 15% |
| Digital / Omnichannel Manager | 10% |
| Company Type | Representation (%) |
|---|---|
| Global Concessionaires (Dufry, Lagardère, Heinemann) | 35% |
| Regional Duty-Free Operators (Dubai Duty Free, China Duty Free) | 20% |
| Luxury Brand Boutiques (LVMH, Kering, Estée Lauder) | 15% |
| Specialty Retailers & F&B Chains (RELAY, SSP, Autogrill) | 18% |
| Technology & Omnichannel Solution Providers | 12% |
 Related Reports
