Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Airline IT Solutions Market Size, Share & Growth Forecast
Airline IT Solutions Market by Software Type (MRO Software, Flight Operations Software, Passenger Service Software, Revenue Management Software, Air Traffic Management Software, Cybersecurity Software), by Deployment Mode (Cloud, On-Premises), by Application (Airlines, Airports, Ground Handlers, MRO Providers), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, Japan, India, South Korea, Australia, Rest of Asia Pacific), by Middle East & Africa (UAE, Saudi Arabia, South Africa, Rest of MEA), by South America (Brazil, Argentina, Rest of South America) Forecast 2026-2034
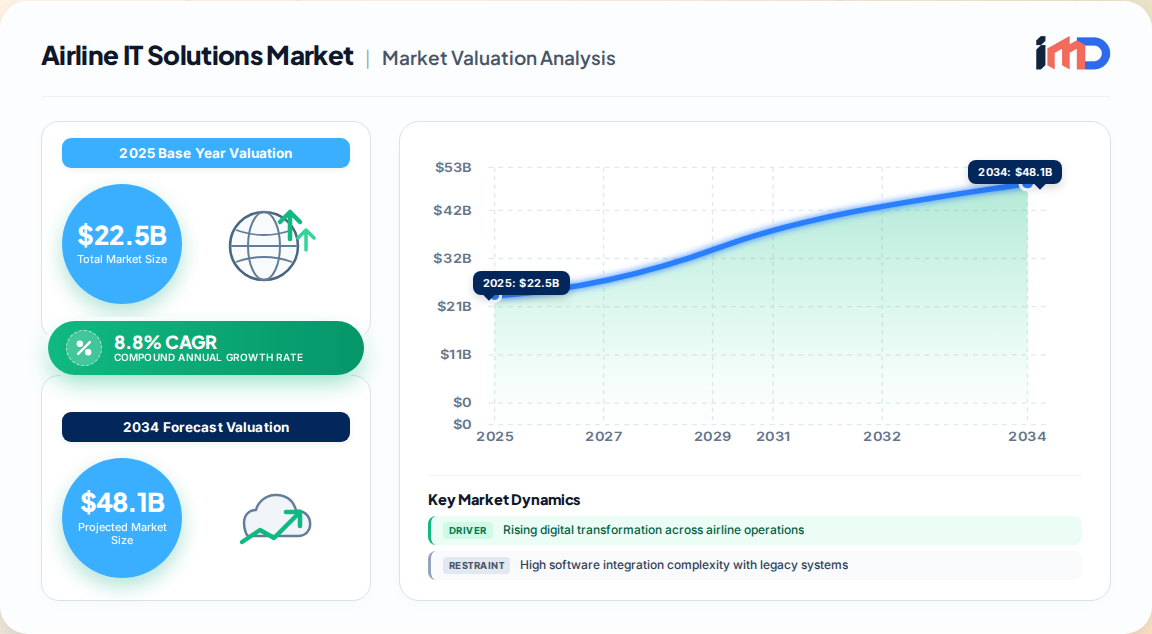
The global Airline IT Solutions Market is undergoing a profound transformation, driven by the imperative to enhance operational efficiency, elevate passenger experience, and ensure regulatory compliance. Our proprietary primary research and expert interviews estimate the market at $22.5 billion in 2025, with a projected compound annual growth rate (CAGR) of 8.8% from 2026 to 2033. This growth trajectory reflects a fundamental shift from legacy, siloed systems to integrated, cloud-native, and AI-powered platforms.
Airline IT Solutions Market Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
22.50 B
2025
24.48 B
2026
26.63 B
2027
28.98 B
2028
31.53 B
2029
34.30 B
2030
37.32 B
2031
Key market takeaways include:
Software Type: Maintenance, Repair, and Overhaul (MRO) software holds the dominant share at 34.0% in 2025, as airlines prioritize asset longevity and cost control.
Deployment: Cloud-based solutions command a 66.0% share, favored for scalability and real-time analytics.
Application: The airline segment accounts for 77.0% of demand, with airports and ground handlers representing the remainder.
Regional Dominance: North America leads with 36.0% revenue share, while Asia Pacific is the fastest-growing region.
Key Challenge: Integration complexity with legacy infrastructure remains a critical restraint, requiring substantial upfront investments.
Key Market Drivers & Restraints
Drivers
Rising Digital Transformation across Airline Operations: Airlines are rapidly adopting integrated software platforms to streamline flight operations, optimize fuel management, and automate scheduling. The push for real-time data analytics, operational visibility, and cost-effective fleet optimization is accelerating investments in next-generation IT solutions.
Demand for Enhanced Passenger Experience: Passengers expect seamless, personalized travel from booking to arrival. IT solutions enabling biometric verification, self-service kiosks, and personalized ancillaries are becoming non-negotiable for competitive differentiation.
Proliferation of AI and Predictive Analytics: AI-driven predictive maintenance, dynamic pricing, and revenue management software are enabling airlines to reduce downtime, maximize ancillary revenues, and improve profitability.
Regulatory Compliance and Cybersecurity: Increasing emphasis on aviation safety, data protection, and compliance with international standards is driving upgrades from legacy systems to secure, modern platforms.
Restraints
High Software Integration Complexity: Many airlines and airports rely on outdated operational technologies that are difficult to integrate with advanced cloud-based solutions. The transition requires substantial investments in infrastructure, training, and customization, which can slow adoption, particularly among small and medium-sized operators.
Threat of Malicious Cyber-Attacks: The growing digitalization of critical aviation infrastructure exposes airlines to significant cybersecurity risks. High-profile breaches can erode passenger trust and lead to regulatory penalties, acting as a deterrent to rapid IT adoption.
High Cost of Technology: For smaller airlines with limited IT budgets, the upfront costs of advanced solutions and the need for continuous updates pose a financial barrier.
Segmentation Analysis
The market is segmented by software type, deployment mode, and application.
Software Type: MRO software leads due to its critical role in reducing aircraft downtime and ensuring safety compliance. Flight operations and revenue management software are also significant, driven by the need for real-time decision-making and profitability optimization. Cybersecurity solutions are gaining traction as a distinct segment, with airlines investing heavily in threat detection and data protection.
Deployment Mode: Cloud-based deployment is preferred for its scalability, cost-efficiency, and ability to support real-time analytics across distributed operations. However, on-premises solutions retain a loyal base among airlines with stringent data security requirements or custom integration needs.
Application: Airlines are the primary end-users, leveraging IT solutions for everything from crew scheduling to predictive maintenance. Airports are increasingly adopting integrated platforms for baggage handling, resource management, and passenger flow optimization.
Regional Outlook
North America dominates the global market with a 36.0% revenue share, underpinned by advanced aviation infrastructure and early adoption of AI and cloud technologies. The U.S. is the largest single market, with airlines investing heavily in digital transformation to enhance operational resilience.
Airline IT Solutions Market Regional Market Share
Loading chart...
Europe follows, with a focus on regulatory compliance (e.g., GDPR) and modernization of air traffic management infrastructure. The region is witnessing significant investments in cybersecurity and passenger experience technologies.
Asia Pacific is the fastest-growing region, driven by rapid air traffic growth, airport expansions, and rising middle-class demand for air travel. Countries like China and India are investing heavily in smart airport initiatives and airline IT upgrades.
The Middle East & Africa and South America regions are also expected to grow, albeit at a slower pace, as airlines in these regions focus on cost-effective solutions and gradual digitalization.
Competitive Landscape & Strategic Developments
The market is highly competitive, with a mix of established aviation technology providers and emerging software specialists. Key players include Airbus, Amadeus IT Group SA, Boeing, Collins Aerospace, General Electric, Honeywell International Inc., IBM, L3Harris Technologies, Lufthansa Technik, Oracle, Raytheon Technologies Corporation, Sabre, SAP SE, SITA, and Thales Group.
Recent strategic developments include:
March 2023: Honeywell and Lufthansa Technik collaborated to enhance aviation analytics by integrating Lufthansa’s digital platform with Honeywell’s connected aircraft solutions.
2022: Amadeus acquired a cloud-based revenue management software firm to strengthen its airline IT portfolio.
2023: SITA launched a new biometric-enabled passenger processing platform to streamline airport operations.
Companies are focusing on strategic partnerships, product innovation, and mergers and acquisitions to expand their capabilities and geographic reach. The competitive landscape is characterized by a strong emphasis on R&D, particularly in AI, IoT, and cybersecurity.
Value Chain Analysis
The airline IT solutions value chain comprises several distinct stages:
Software Development: Includes requirements gathering, design, coding, and testing. Companies invest heavily in R&D to incorporate AI, machine learning, and advanced analytics.
System Integration: Deployment and customization of software to integrate with existing airline and airport systems, often requiring specialized consulting services.
Hardware Infrastructure: Provision of servers, networking equipment, and IoT devices (e.g., sensors for predictive maintenance).
Operations & Maintenance: Ongoing support, updates, and managed services to ensure system reliability and security.
End-users: Airlines, airports, ground handlers, and MRO providers.
Each stage is critical, with system integration often being the most complex and time-consuming, contributing to the high costs and implementation challenges noted in the market.
Strategic White-Space Analysis
Several untapped opportunities exist for IT solution providers:
Small and Medium-Sized Airlines: Offering modular, cost-effective cloud solutions that can be deployed incrementally to reduce upfront investment.
Cybersecurity as a Service: Providing subscription-based cybersecurity solutions tailored to the aviation industry, addressing the growing threat landscape.
Predictive Maintenance for Regional Carriers: Developing AI-driven predictive maintenance tools specifically designed for older aircraft fleets, which are common among regional airlines.
Integrated Passenger Experience Platforms: Creating unified platforms that combine booking, check-in, baggage tracking, and in-flight services to deliver a seamless passenger journey.
These white spaces represent significant growth avenues for providers that can address the unique needs of underserved segments with flexible, scalable solutions.
Airline IT Solutions Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Airline IT Solutions Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.8% from 2020-2034
Segmentation
By Software Type
MRO Software
Flight Operations Software
Passenger Service Software
Revenue Management Software
Air Traffic Management Software
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Rising digital transformation across airline operations
3.1.2. Demand for enhanced passenger experience
3.1.3. Proliferation of AI and predictive analytics
3.1.4. Regulatory compliance and safety requirements
3.2. Market Trends
3.2.1. Rising adoption of cloud-based SaaS platforms
3.2.2. Integration of AI and predictive analytics for operational efficiency
3.2.3. Growth of biometric and self-service passenger processing
3.2.4. Increasing focus on cybersecurity solutions
3.3. Market Restrains
3.3.1. High software integration complexity with legacy systems
3.3.2. Threat of malicious cyber-attacks
3.3.3. High cost of technology upgrades
3.4. Market Restraints
3.4.1. High software integration complexity with legacy systems
3.4.2. Threat of malicious cyber-attacks
3.4.3. High cost of technology upgrades
3.5.
Cybersecurity Software
By Deployment Mode
Cloud
On-Premises
By Application
Airlines
Airports
Ground Handlers
MRO Providers
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Rest of Europe
Asia Pacific
China
Japan
India
South Korea
Australia
Rest of Asia Pacific
Middle East & Africa
UAE
Saudi Arabia
South Africa
Rest of MEA
South America
Brazil
Argentina
Rest of South America
Market Challenges
3.5.1. Managing data privacy and regulatory compliance across regions
3.5.2. Shortage of skilled IT talent in aviation
3.5.3. Resistance to change from legacy system users
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Software Type
5.1.1. MRO Software
5.1.2. Flight Operations Software
5.1.3. Passenger Service Software
5.1.4. Revenue Management Software
5.1.5. Air Traffic Management Software
5.1.6. Cybersecurity Software
5.2. Market Analysis, Insights and Forecast - by Deployment Mode
5.2.1. Cloud
5.2.2. On-Premises
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Airlines
5.3.2. Airports
5.3.3. Ground Handlers
5.3.4. MRO Providers
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. Europe
5.4.3. Asia Pacific
5.4.4. Middle East & Africa
5.4.5. South America
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Software Type
6.1.1. MRO Software
6.1.2. Flight Operations Software
6.1.3. Passenger Service Software
6.1.4. Revenue Management Software
6.1.5. Air Traffic Management Software
6.1.6. Cybersecurity Software
6.2. Market Analysis, Insights and Forecast - by Deployment Mode
6.2.1. Cloud
6.2.2. On-Premises
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Airlines
6.3.2. Airports
6.3.3. Ground Handlers
6.3.4. MRO Providers
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Software Type
7.1.1. MRO Software
7.1.2. Flight Operations Software
7.1.3. Passenger Service Software
7.1.4. Revenue Management Software
7.1.5. Air Traffic Management Software
7.1.6. Cybersecurity Software
7.2. Market Analysis, Insights and Forecast - by Deployment Mode
7.2.1. Cloud
7.2.2. On-Premises
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Airlines
7.3.2. Airports
7.3.3. Ground Handlers
7.3.4. MRO Providers
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Software Type
8.1.1. MRO Software
8.1.2. Flight Operations Software
8.1.3. Passenger Service Software
8.1.4. Revenue Management Software
8.1.5. Air Traffic Management Software
8.1.6. Cybersecurity Software
8.2. Market Analysis, Insights and Forecast - by Deployment Mode
8.2.1. Cloud
8.2.2. On-Premises
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Airlines
8.3.2. Airports
8.3.3. Ground Handlers
8.3.4. MRO Providers
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Software Type
9.1.1. MRO Software
9.1.2. Flight Operations Software
9.1.3. Passenger Service Software
9.1.4. Revenue Management Software
9.1.5. Air Traffic Management Software
9.1.6. Cybersecurity Software
9.2. Market Analysis, Insights and Forecast - by Deployment Mode
9.2.1. Cloud
9.2.2. On-Premises
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Airlines
9.3.2. Airports
9.3.3. Ground Handlers
9.3.4. MRO Providers
10. South America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Software Type
10.1.1. MRO Software
10.1.2. Flight Operations Software
10.1.3. Passenger Service Software
10.1.4. Revenue Management Software
10.1.5. Air Traffic Management Software
10.1.6. Cybersecurity Software
10.2. Market Analysis, Insights and Forecast - by Deployment Mode
10.2.1. Cloud
10.2.2. On-Premises
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Airlines
10.3.2. Airports
10.3.3. Ground Handlers
10.3.4. MRO Providers
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Airbus
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Amadeus IT Group SA
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Boeing
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Collins Aerospace
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. General Electric
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Honeywell International Inc.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. IBM
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. L3Harris Technologies
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Lufthansa Technik
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Oracle
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Raytheon Technologies Corporation
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Sabre
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. SAP SE
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. SITA
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Thales Group
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Airline IT Solutions Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Airline IT Solutions Market Revenue (Billion), by Software Type 2026 & 2034
Figure 3: North America Airline IT Solutions Market Revenue Share (%), by Software Type 2026 & 2034
Figure 4: North America Airline IT Solutions Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 5: North America Airline IT Solutions Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 6: North America Airline IT Solutions Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Airline IT Solutions Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Airline IT Solutions Market Revenue (Billion), by Country 2026 & 2034
Figure 9: North America Airline IT Solutions Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Airline IT Solutions Market Revenue (Billion), by Software Type 2026 & 2034
Figure 11: Europe Airline IT Solutions Market Revenue Share (%), by Software Type 2026 & 2034
Figure 12: Europe Airline IT Solutions Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 13: Europe Airline IT Solutions Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 14: Europe Airline IT Solutions Market Revenue (Billion), by Application 2026 & 2034
Figure 15: Europe Airline IT Solutions Market Revenue Share (%), by Application 2026 & 2034
Figure 16: Europe Airline IT Solutions Market Revenue (Billion), by Country 2026 & 2034
Figure 17: Europe Airline IT Solutions Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia Pacific Airline IT Solutions Market Revenue (Billion), by Software Type 2026 & 2034
Figure 19: Asia Pacific Airline IT Solutions Market Revenue Share (%), by Software Type 2026 & 2034
Figure 20: Asia Pacific Airline IT Solutions Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 21: Asia Pacific Airline IT Solutions Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 22: Asia Pacific Airline IT Solutions Market Revenue (Billion), by Application 2026 & 2034
Figure 23: Asia Pacific Airline IT Solutions Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Asia Pacific Airline IT Solutions Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Asia Pacific Airline IT Solutions Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Airline IT Solutions Market Revenue (Billion), by Software Type 2026 & 2034
Figure 27: Middle East & Africa Airline IT Solutions Market Revenue Share (%), by Software Type 2026 & 2034
Figure 28: Middle East & Africa Airline IT Solutions Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 29: Middle East & Africa Airline IT Solutions Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 30: Middle East & Africa Airline IT Solutions Market Revenue (Billion), by Application 2026 & 2034
Figure 31: Middle East & Africa Airline IT Solutions Market Revenue Share (%), by Application 2026 & 2034
Figure 32: Middle East & Africa Airline IT Solutions Market Revenue (Billion), by Country 2026 & 2034
Figure 33: Middle East & Africa Airline IT Solutions Market Revenue Share (%), by Country 2026 & 2034
Figure 34: South America Airline IT Solutions Market Revenue (Billion), by Software Type 2026 & 2034
Figure 35: South America Airline IT Solutions Market Revenue Share (%), by Software Type 2026 & 2034
Figure 36: South America Airline IT Solutions Market Revenue (Billion), by Deployment Mode 2026 & 2034
Figure 37: South America Airline IT Solutions Market Revenue Share (%), by Deployment Mode 2026 & 2034
Figure 38: South America Airline IT Solutions Market Revenue (Billion), by Application 2026 & 2034
Figure 39: South America Airline IT Solutions Market Revenue Share (%), by Application 2026 & 2034
Figure 40: South America Airline IT Solutions Market Revenue (Billion), by Country 2026 & 2034
Figure 41: South America Airline IT Solutions Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Airline IT Solutions Market Revenue Billion Forecast, by Software Type 2020 & 2034
Table 2: Global Airline IT Solutions Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 3: Global Airline IT Solutions Market Revenue Billion Forecast, by Application 2020 & 2034
Table 4: Global Airline IT Solutions Market Revenue Billion Forecast, by Region 2020 & 2034
Table 5: North America Airline IT Solutions Market Revenue Billion Forecast, by Software Type 2020 & 2034
Table 6: North America Airline IT Solutions Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 7: North America Airline IT Solutions Market Revenue Billion Forecast, by Application 2020 & 2034
Table 8: North America Airline IT Solutions Market Revenue Billion Forecast, by Country 2020 & 2034
Table 9: USA Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 10: Canada Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 11: Mexico Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Europe Airline IT Solutions Market Revenue Billion Forecast, by Software Type 2020 & 2034
Table 13: Europe Airline IT Solutions Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 14: Europe Airline IT Solutions Market Revenue Billion Forecast, by Application 2020 & 2034
Table 15: Europe Airline IT Solutions Market Revenue Billion Forecast, by Country 2020 & 2034
Table 16: Germany Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: UK Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: France Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 19: Italy Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: Spain Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: Rest of Europe Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Asia Pacific Airline IT Solutions Market Revenue Billion Forecast, by Software Type 2020 & 2034
Table 23: Asia Pacific Airline IT Solutions Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 24: Asia Pacific Airline IT Solutions Market Revenue Billion Forecast, by Application 2020 & 2034
Table 25: Asia Pacific Airline IT Solutions Market Revenue Billion Forecast, by Country 2020 & 2034
Table 26: China Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: Japan Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: India Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: South Korea Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: Australia Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Rest of Asia Pacific Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: Middle East & Africa Airline IT Solutions Market Revenue Billion Forecast, by Software Type 2020 & 2034
Table 33: Middle East & Africa Airline IT Solutions Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 34: Middle East & Africa Airline IT Solutions Market Revenue Billion Forecast, by Application 2020 & 2034
Table 35: Middle East & Africa Airline IT Solutions Market Revenue Billion Forecast, by Country 2020 & 2034
Table 36: UAE Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 37: Saudi Arabia Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: South Africa Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: Rest of MEA Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: South America Airline IT Solutions Market Revenue Billion Forecast, by Software Type 2020 & 2034
Table 41: South America Airline IT Solutions Market Revenue Billion Forecast, by Deployment Mode 2020 & 2034
Table 42: South America Airline IT Solutions Market Revenue Billion Forecast, by Application 2020 & 2034
Table 43: South America Airline IT Solutions Market Revenue Billion Forecast, by Country 2020 & 2034
Table 44: Brazil Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 45: Argentina Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 46: Rest of South America Airline IT Solutions Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current market size of the airline IT solutions market?
The global airline IT solutions market was valued at $22.5 billion in 2025 and is projected to grow at a CAGR of 8.8% from 2026 to 2033, reaching approximately $40.8 billion by 2033.
2Which region dominates the airline IT solutions market?
North America holds the largest share at 36.0% in 2025, driven by advanced aviation infrastructure and early adoption of AI and cloud technologies.
3What are the key drivers for the airline IT solutions market?
Key drivers include rising digital transformation across airline operations, demand for enhanced passenger experience, proliferation of AI and predictive analytics, and regulatory compliance requirements.
4What is the leading deployment mode in the airline IT solutions market?
Cloud-based deployment dominates with a 66.0% share in 2025, favored for its scalability, cost-efficiency, and support for real-time analytics.
5Who are the major players in the airline IT solutions market?
Major players include Amadeus IT Group, Sabre, SITA, IBM, Oracle, SAP, Airbus, Boeing, Honeywell, and Thales Group, among others.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 70–80% of research via primary interviews with 150+ industry executives, including airline CIOs, IT directors, airport technology officers, and MRO software specialists.
Interviewed stakeholders such as Chief Information Officers (Airlines), VP of Operations, Product Managers for Aviation Software, and Procurement Heads for IT solutions.
Engaged with industry associations including IATA (International Air Transport Association), ACI (Airports Council International), and ICAO (International Civil Aviation Organization) for regulatory and operational insights.
Gathered quantitative data on IT spending per passenger, number of software licenses deployed, cloud adoption rates, and integration timelines to inform bottom-up market sizing.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
CIO / IT Director
40%
VP of Operations
25%
Product Manager
20%
Procurement Head
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Airline IT Departments
35%
Airport Technology Providers
25%
MRO Software Specialists
20%
Aviation Consultants
10%
Regulatory Bodies
10%
Secondary Research & Industry Benchmarking
Utilized 20–30% secondary research from official sources such as the U.S. Department of Transportation (DOT), Eurostat, and the World Bank’s air transport data.
Benchmarked against financial databases including Bloomberg, Factiva, Hoovers, and PitchBook for company financials and investment trends.
Referenced non-profit trade associations such as the Aviation Maintenance Software Association (AMSA) and the International Society of Transport Aircraft Trading (ISTAT) for technical standards and market norms.
Ensured all data is validated through multi-level triangulation, cross-referencing primary interviews with secondary statistics.
Demand Modeling & Market Estimation
Employed both top-down and bottom-up methodologies simultaneously. Top-down approach used global airline IT spending budgets from IATA and allocated by segment. Bottom-up approach built market size from unit shipments (software licenses, subscriptions) multiplied by average pricing, validated by expert interviews.
Key metrics used: number of commercial aircraft worldwide (approx. 25,000), average IT spend per aircraft ($80,000–$120,000), number of airports investing in IT upgrades (1,200+), and cloud adoption rate (66%).
Demand models segmented by software type, deployment, application, and region, with each segment validated through primary interviews.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90%, achieved through rigorous multi-level data triangulation and iterative validation.
Every report is updated to the date of purchase to ensure latest market developments are incorporated.
Conducted sanity checks on all quantitative outputs, comparing with historical trends and industry benchmarks from official sources.
Final validation through a panel of internal experts and external advisors from aviation and IT domains.
Independent Intelligence for decisions that move markets
Hotel self check-in and check-out kiosk market to reach $4.98 Billion by 2032 at 11% CAGR. Explore growth pathways, pricing, ROI and deployment strategies.
Airport retailing market to reach USD 187.67 Billion by 2035, growing at 15% CAGR. Explore duty-free, fashion, and digital retail trends.
Nov 2026|208 pages
$2900.00
Airport sleeping pods market valued at USD 87.9M in 2025, growing at 7.1% CAGR to reach USD 175.6M by 2035. Get in-depth analysis, trends, and regional outlook.
Nov 2026|256 pages
$2900.00
Europe yacht market valued at USD 3.75 Billion in 2025, projected to grow at 6.4% CAGR through 2035. Superyachts, hybrid propulsion & charter demand drive expansion.