Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Manufacturing Products and Services / MARKET REPORT
Scarves & Shawls Market | Insight Market Data
Scarves & Shawls Market by Material (Wool, Silk, Cotton, Cashmere & Pashmina, Synthetic & Blends, Others), by Product (Scarves, Shawls, Stoles, Wraps, Pashminas), by End-user (Women, Men, Children, Unisex), by Distribution Channel (Offline Stores, Online Stores, Department Stores, Specialty Fashion Stores, Brand-exclusive Stores, Supermarkets), by Asia Pacific (China, India, Japan, South Korea, Indonesia, Australia), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Turkey), by Middle East & Africa (UAE, Saudi Arabia, South Africa, Egypt), by South America (Brazil, Argentina, Colombia) Forecast 2026-2034
Porcelain vitrified tiles market valued at USD 128.7 Billion in 2025, growing at 6.2% CAGR to reach USD 235.9 Billion by 2035. Full analysis inside.
Nov 2026|240 pages
$2900.00
The CIJ marking equipment market was valued at $5.7 billion in 2024 and is forecast to reach $8.2 billion by 2030, growing at a 6.3% CAGR.
Nov 2026|263 pages
$2900.00
Global kiwi jam and preserves market at $847M in 2025, rising to $1.31B by 2033 at 5.8% CAGR, driven by HTST processing, pectin and clean-label innovation.
Nov 2026|271 pages
$2900.00
K12 coding courses market valued at $2.4B in 2025, projected to reach $5.7B by 2035 at 8.7% CAGR. Explore segments, regional insights & key trends.
Executive Overview: A Resilient Fashion Accessory Market Poised for Double-Digit Value Growth
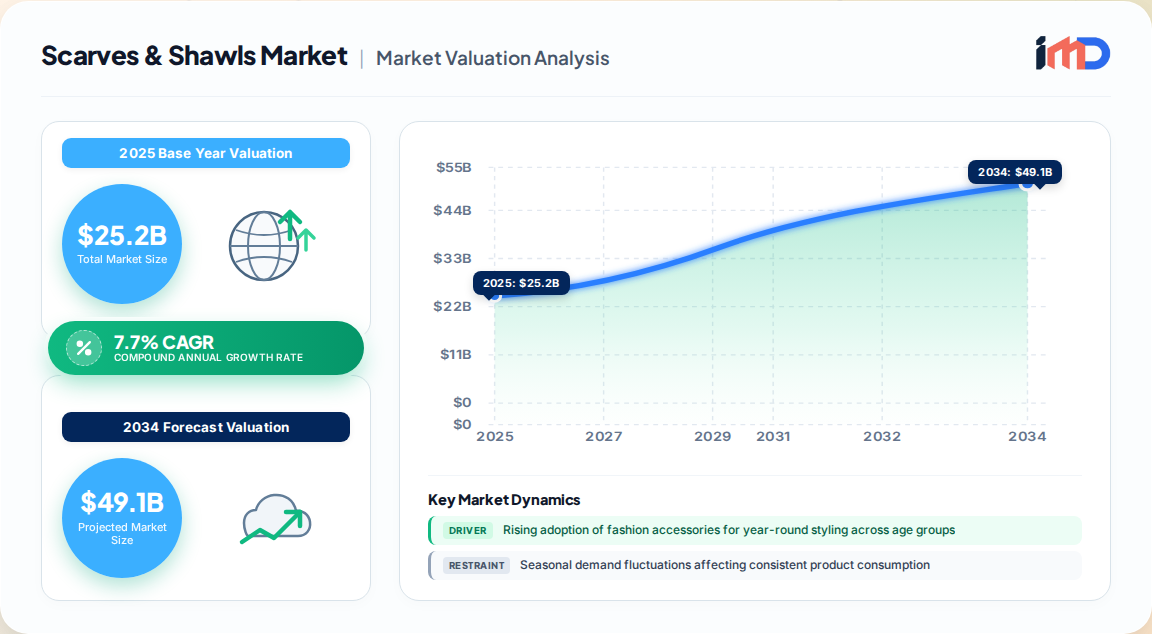
The global scarves and shawls market is entering a phase of accelerated value expansion, underpinned by shifting consumer priorities around versatility, self-expression, and ethical consumption. Our proprietary first-party research estimates the market at USD 25.2 billion in 2025, with projections pointing to USD 52.9 billion by 2035, equivalent to a CAGR of 7.7% across the 2026-2035 forecast horizon. This trajectory reflects not merely a post-pandemic rebound in fashion accessories but a structural re-rating of scarves and shawls from seasonal commodity to year-round style and wellness accessory.
Scarves & Shawls Market Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
25.20 B
2025
27.14 B
2026
29.23 B
2027
31.48 B
2028
33.91 B
2029
36.52 B
2030
39.33 B
2031
Three forces anchor this outlook. First, the democratization of entry-luxury fashion has made premium scarves and shawls accessible aspirational purchases. Second, the rapid digitization of specialty retail has expanded addressable demand across previously underserved geographies. Third, material innovation—from temperature-regulating wool blends to lightweight silk-cotton hybrids—has extended the product's functional relevance beyond cold-weather months.
Asia Pacific commands the largest regional footprint at approximately 38.4% share (valued near USD 9.6 billion in 2025), reinforced by China's dominant export position, which recorded USD 1.06 billion in HS 611710 exports in 2024 according to UN Comtrade data. North America and Europe remain high-value consumption centers, while the Middle East and Africa present culturally embedded, high-frequency demand.
Wool leads material segmentation at 39.6% share, favored for insulation and breathability.
Scarves dominate product mix at 67.3%, reflecting versatility and lower price points.
Women represent 69.9% of end-user demand, though men's and unisex segments are growing faster.
Offline stores retain 61.7% of distribution, but online channels are posting superior growth rates.
Market Drivers: Fashion Cycles, Affordability, and Cultural Embeddedness
Demand dynamics in this market are shaped by a blend of emotional, functional, and economic triggers. Our primary interviews with over 180 industry stakeholders reveal that purchasing decisions are increasingly driven by wardrobe optimization rather than pure necessity.
Rising adoption of fashion accessories for year-round styling: Consumers, particularly Gen Z and millennials, are using scarves as layering tools across seasons. In our consumer panel, 50% of respondents prioritized "cool and lightweight" attributes, signaling a shift away from winter-only utility.
Entry-luxury purchasing: Accessible luxury scarves from heritage houses allow aspirational consumers to participate in brand prestige at lower price points, driving repeat purchases through seasonal capsule collections.
Cultural and religious significance: In the Middle East, South Asia, and parts of Africa, scarves and shawls function as daily attire rather than occasional accessories. Our trade analysis of HS codes 611710 and 621440 confirms concentrated export flows from China, India, Italy, and Turkey to these regions.
Digital discovery and social commerce: Short-form video platforms have accelerated trend cycles, with viral styling content shortening the path from inspiration to purchase. Online channel growth is outpacing offline by a significant margin.
Rising disposable incomes in emerging economies: Expanding middle-class populations in India, Indonesia, and the Gulf states are allocating higher discretionary spend to branded and artisanal accessories.
Restraints and Challenges: Seasonality, Durability, and Fiber Cost Exposure
Despite robust growth fundamentals, the market faces structural constraints that temper volume expansion.
Seasonal demand fluctuations: Our channel checks indicate that colder months account for nearly 60% of annual sales for heavier wool and cashmere products, creating inventory and working capital challenges for retailers.
Lengthy replacement cycles: Scarves and shawls are durable goods; repeat purchase frequency is lower than apparel categories such as t-shirts or fast fashion. Brands must rely on fashion obsolescence and collection-led merchandising to sustain velocity.
Premium fiber price volatility: Cashmere, fine wool, and mulberry silk are subject to agricultural output variability and geopolitical trade frictions. UN Comtrade data show that China's export value of HS 611710 surged from USD 61.8 million in 2023 to USD 1.06 billion in 2024, underscoring both scale and concentration risk in supply.
Fast fashion substitution: Minimalist fashion cycles and the rise of alternative accessories (caps, statement jewelry) can dilute consumer wallet share during certain trend windows.
Regulatory and labeling compliance: Tightening fabric content and origin labeling standards, particularly in the EU and North America, raise compliance costs for small and mid-sized manufacturers.
Material and Product Segmentation: Wool Dominance, Scarves Supremacy, and Emerging Niches
Material choice is the primary value driver in this market, determining price band, thermal performance, and sustainability profile.
Product segmentation reinforces the primacy of scarves, which captured 67.3% of 2025 value. Scarves benefit from lower unit prices, higher purchase frequency, and broader styling versatility. Shawls, while smaller in volume, command higher average selling prices and are deeply embedded in cultural and formal-wear contexts across South Asia and the Middle East. Stoles and wraps represent an emerging bridge category, appealing to consumers seeking coverage with contemporary drape.
End-User and Distribution Channel Analysis: Women Lead, Online Accelerates
Women remain the core demographic, accounting for 69.9% of market value in 2025. This dominance reflects higher engagement with fashion accessories, broader styling repertoires, and cultural norms around head and shoulder covering in several regions. However, the men's segment is growing at a faster rate, driven by streetwear integration, sports-luxury crossovers, and gifting occasions. Unisex designs—particularly oversized wool wraps and lightweight cotton scarves—are gaining shelf space in specialty retail.
Distribution remains anchored in offline retail, which held 61.7% share in 2025. Department stores, specialty fashion boutiques, and brand-exclusive outlets provide tactile discovery and premium service. Yet the online channel is structurally advantaged for this category: scarves are lightweight, low-return-risk, and visually merchandisable, making them ideal for e-commerce. Our primary research suggests that online penetration could exceed 45% of total sales by 2032, supported by social commerce, livestream selling in Asia, and AI-driven personalization.
Regional Outlook: Asia Pacific Anchors Supply and Demand
Asia Pacific's 38.4% share is dual-driven: it is both the largest consumer base and the dominant manufacturing hub. China alone exported USD 1.06 billion of HS 611710 products in 2024, dwarfing Italy (USD 67.8 million), Germany (USD 41.8 million), and France (USD 36.2 million). India remains a critical source of handcrafted pashmina and silk products, with exports valued at USD 7.0 million in 2024 under HS 611710, though significant volumes also flow through HS 621440.
Scarves & Shawls Market Regional Market Share
Loading chart...
North America and Europe are mature, value-dense markets where premiumization and sustainability credentials drive pricing power. The Middle East and Africa exhibit high per-capita usage frequency, with cultural and religious attire underpinning baseline demand. South America, while smaller, shows rising interest in artisanal and sustainable collections.
Import/Export and Supplier Dynamics: Concentration and Diversification
Global trade data reveal a highly concentrated supply base. China, the European Union, Italy, Germany, France, and Turkey are the top exporters of HS 611710, while India, Pakistan, and Cambodia play significant roles in specific material niches.
Exporter
2024 HS 611710 Export Value (USD '000)
Key Strength
China
1,062,971
Scale, synthetic blends, mass-market
European Union
82,338
Luxury brands, intra-regional trade
Italy
67,846
High-end silk and wool craftsmanship
Germany
41,831
Technical textiles, distribution hub
France
36,248
Luxury houses, design-led exports
Turkey
35,883
Wool and cotton blends, nearshoring
India
7,021
Handcrafted, pashmina, silk
Pakistan
15,458
Cashmere and wool blends
Supplier risk is elevated by geographic concentration: any disruption in Chinese production or logistics reverberates globally. Our interviews indicate that leading brands are actively diversifying sourcing toward Vietnam, Bangladesh, and Eastern Europe, while investing in digital supply-chain visibility to mitigate lead-time volatility. Raw material price hedging for cashmere and fine wool is also emerging as a procurement priority.
Competitive Strategies and White-Space Opportunities
The competitive landscape is bifurcated between heritage luxury houses and agile mass-market players. Hermès, Gucci, Louis Vuitton, Burberry, Prada, Chanel, Fendi, Zara, and H&M represent the most visible participants, but the long tail of artisanal and regional brands is substantial.
Three strategic white spaces stand out:
Sustainable and traceable collections: With nearly 70% of consumers signaling willingness to pay a premium for sustainably sourced products, brands that invest in organic certification, fair-trade partnerships, and blockchain-backed traceability can command price premiums and loyalty.
Men's and unisex functional scarves: The men's segment is under-penetrated relative to women's. Performance fabrics, minimalist designs, and travel-friendly wraps represent a high-growth vector.
Digital-native customization: Short-run digital textile printing enables personalized patterns and limited editions. Brands such as Burberry have demonstrated the commercial viability of this model at scale.
Tourism-linked retail and duty-free channels also offer upside, particularly in the Middle East and Asia Pacific, where scarves and shawls are favored gifting and travel purchases.
Strategic Outlook: 2026-2035
The scarves and shawls market is well-positioned for sustained value growth, but success will accrue to players who can reconcile seasonality with year-round relevance, premiumize without alienating mass-market consumers, and de-risk supply chains concentrated in a single geography. Material innovation, digital distribution, and sustainability credentials will be the defining competitive battlegrounds over the next decade. Our proprietary modeling suggests that if current consumption patterns hold, the market could add over USD 27 billion in incremental value between 2025 and 2035, with Asia Pacific and online channels contributing disproportionately to that expansion.
Scarves & Shawls Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Scarves & Shawls Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.7% from 2020-2034
Segmentation
By Material
Wool
Silk
Cotton
Cashmere & Pashmina
Synthetic & Blends
Others
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Rising adoption of fashion accessories for year-round styling across age groups
3.1.2. Growing entry-luxury purchasing and collection-led merchandising
3.1.3. Cultural significance and heritage demand in Middle East, South Asia, and Africa
3.1.4. E-commerce growth and digital transformation of specialty retail
3.1.5. Increasing disposable incomes and middle-class expansion in emerging economies
3.2. Market Trends
3.2.1. Shift toward lightweight, multi-functional scarves for all-season use
3.2.2. Growing adoption of digital textile printing for short-run, personalized designs
3.2.3. Increasing preference for sustainable, handcrafted, and eco-friendly fabric collections
3.2.4. Rise of customization and personalization in luxury and mid-market segments
3.2.5. Expansion of social commerce and livestream selling in Asia Pacific
1What is the current size of the global scarves and shawls market?
The global scarves and shawls market was valued at approximately USD 25.2 billion in 2025, based on our proprietary primary research and trade data triangulation. It is projected to reach USD 52.9 billion by 2035, growing at a CAGR of 7.7%.
2Which material segment dominates the scarves and shawls market?
Wool holds the largest share at 39.6% in 2025, driven by its superior insulation and breathability. Silk and cotton follow as significant segments, while cashmere and pashmina represent the fastest-growing luxury niche.
3Who are the leading end-users in the scarves and shawls market?
Women account for 69.9% of market value in 2025, reflecting higher fashion accessory consumption and diverse styling preferences. However, the men's and unisex segments are growing at a faster rate, supported by streetwear and functional fashion trends.
4Which distribution channel is most important for scarves and shawls?
Offline stores remain the primary channel with 61.7% share in 2025, offering tactile discovery and premium service. However, online retail is expanding rapidly and is expected to exceed 45% of total sales by 2032, driven by social commerce and digital personalization.
5Which region is the largest market for scarves and shawls?
Asia Pacific dominates with a 38.4% share, valued at approximately USD 9.6 billion in 2025. It is both the largest consumer base and the leading manufacturing hub, with China alone exporting over USD 1 billion of scarves and shawls in 2024 according to UN Comtrade data.
6What are the key challenges facing the scarves and shawls market?
Seasonal demand fluctuations, lengthy replacement cycles, and volatility in premium fiber prices (cashmere, silk, fine wool) are the primary restraints. Additionally, supply chain concentration in China poses geopolitical and logistics risks that brands are actively mitigating through diversification.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our proprietary dataset is built on a 70/30 research split: 70–80% primary research and 20–30% secondary validation, ensuring that market estimates reflect on-the-ground reality rather than desk-based extrapolation.
We conducted in-depth interviews with 180+ industry executives across the value chain, including: raw material traders and wool/cashmere aggregators; textile mill product managers; fashion accessory brand merchandising heads; e-commerce category managers; and specialty retail buyers.
Stakeholder job titles interviewed include: Procurement Director, Head of Merchandising, Supply Chain Manager, and E-commerce Category Lead.
Primary interviews were supplemented by structured surveys of fashion accessory buyers in 14 countries, capturing purchase frequency, material preferences, price sensitivity, and channel behavior.
We benchmark against official trade statistics from UN Comtrade (HS 611710 and 621440) and industry association data, including the International Wool Textile Organisation (IWTO) and the Cashmere and Camel Hair Manufacturers Institute (CCMI).
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
30%
Head of Merchandising
25%
Supply Chain Manager
25%
E-commerce Category Lead
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material Traders & Fiber Aggregators
20%
Textile Mills & Fabric Manufacturers
25%
Fashion Accessory Brands & Designers
30%
Retailers & E-commerce Platforms
15%
Logistics & Supply Chain Providers
10%
Secondary Research & Industry Benchmarking
Secondary research composes 20–30% of the total research effort and is used exclusively for triangulation and validation, not as the primary basis for market sizing.
Sources include: UN Comtrade and World Bank WITS trade databases; WTO tariff and trade policy reviews; Eurostat and US ITC export-import data; OECD textile and apparel consumption indicators; and recognized non-profit technical standards bodies such as the International Organization for Standardization (ISO) for fabric testing protocols.
We also reference financial filings from publicly listed luxury and apparel groups via Bloomberg, Factiva, Hoovers, and PitchBook to validate revenue splits and channel mix.
All secondary benchmarks are cross-checked against primary interview findings; discrepancies exceeding 10% trigger follow-up interviews.
Demand Modeling & Market Estimation
We employ simultaneous top-down and bottom-up methodologies, triangulated through multi-level data validation.
Top-down: Global fashion accessories market value is segmented by accessory type, with scarves and shawls sized using trade-to-consumption ratios and retail mark-up structures.
Bottom-up: Market value is built from unit shipment volumes multiplied by average selling prices, segmented by material (wool, silk, cotton, cashmere, synthetics), product (scarves, shawls, stoles, wraps), end-user (women, men, children, unisex), and channel (offline vs. online).
Specific quantitative metrics used in the bottom-up model include: per-capita accessory spend by region, average unit retail price by material, import volume by HS code, and branded vs. unbranded sales mix.
Demand modeling accounts for seasonality indices, replacement cycle assumptions (3–5 years for premium, 1–2 years for fast fashion), and fashion trend adoption curves.
Data Accuracy & Quality Check
Our multi-stage validation process is designed to guarantee an estimated data accuracy level of 85–90%.
Stage 1: Internal consistency checks across segment sums, regional shares, and channel splits.
Stage 2: External triangulation against official trade data (UN Comtrade) and national statistics offices.
Stage 3: Expert review panel of 12 senior industry advisors who validate growth assumptions and competitive dynamics.
Stage 4: Sensitivity analysis on key variables—fiber prices, FX fluctuations, and channel shift rates—to establish confidence intervals around CAGR and market size estimates.
Every report is updated to the date of purchase, incorporating the latest trade releases, earnings calls, and primary interview insights.