1What is the RIP bushing market size in 2025?
The global RIP bushing market was valued at USD 592.7 million in 2025 and is projected to reach USD 1.23 billion by 2035, growing at a 7.6% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 RIP Bushing Market
 by By Insulation (RIP, OIP, Other), by By Voltage (Medium Voltage, High Voltage, Extra High Voltage), by By Application (Transformer, Switchgear, Others), by By End Use (Utility, Industries, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, India, Japan, South Korea, Rest of Asia Pacific), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Rest of Middle East & Africa) Forecast 2026-2034

Senior Research Analyst


 Related Reports

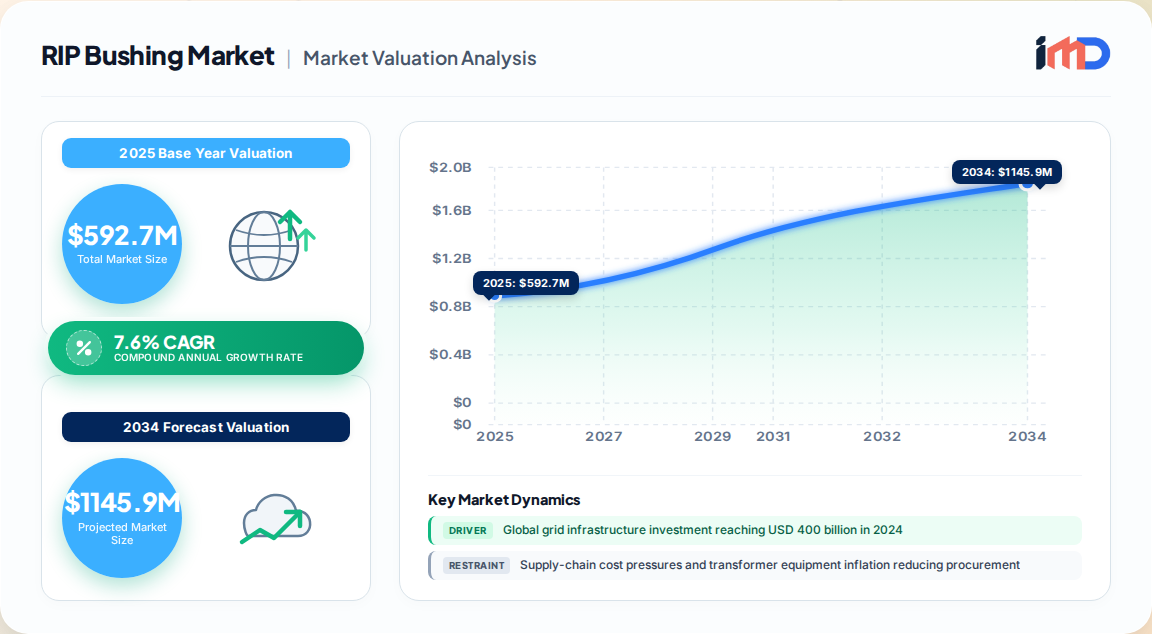
The global RIP (Resin Impregnated Paper) bushing market is undergoing a structural transformation as utilities and OEMs prioritize dry, oil-free insulation systems for high-voltage transmission and distribution infrastructure. Our proprietary primary research estimates the market at USD 592.7 million in 2025, advancing to USD 637.8 million in 2026 and projected to reach USD 1.23 billion by 2035, expanding at a 7.6% CAGR over the forecast period. Volume shipments reached approximately 7.0 million units in 2025, with revenue growth increasingly shaped by specification intensity as higher-rated dry-type designs gain prominence in EHV and HVDC applications. Asia-Pacific commands the largest regional share at 43%, driven by China's State Grid build-out and India's renewable integration corridors, while Europe and North America follow with 23% and 20% respectively, supported by grid modernization and SF₆ phase-out mandates.
The RIP bushing market is segmented by insulation, voltage, application, and end use. High-voltage bushings account for 55% of the market, driven by extensive deployment in power transmission systems. The transformer segment holds the largest application share at approximately 62%, reflecting massive ongoing grid development and fleet replacement. Utilities lead the end-use segment, fueled by large-scale investments in transmission and distribution networks.
| Segment | Sub-Segment | Market Share (2025) | Key Characteristics |
|---|---|---|---|
| By Voltage | Medium Voltage | ~25% | Distribution networks, industrial applications |
| High Voltage | ~55% | Power transmission, substation upgrades | |
| Extra High Voltage | ~20% | HVDC corridors, converter stations, CAGR 11.5% | |
| By Application | Transformer | ~62% | Dominant application, replacement and new-build |
| Switchgear | ~30% | GIS and AIS, CAGR 5.8% | |
| Others | ~8% | Railway electrification, industrial | |
| By End Use | Utility | ~70% | Transmission and distribution operators |
| Industries | ~20% | Industrial power infrastructure | |
| Others | ~10% | Transportation, commercial |
Asia-Pacific leads the global RIP bushing market with an estimated 43% share, underpinned by China and India's grid investment programs. China's State Grid build-out and India's Green Energy Corridor program are driving large-scale adoption of RIP bushings in transformers and switchgear. Europe holds the second-largest position with approximately 23% share, supported by TEN-E corridor investments, aging fleet replacement, and regulatory mandates for SF₆-free switchgear. North America follows with 20% share, with substantial grid-hardening spend under the U.S. Bipartisan Infrastructure Law fueling demand through 2030 and beyond. The Middle East & Africa region is the fastest-growing, albeit from a smaller base, driven by grid expansion and renewable integration projects.
The market features strong competition among global manufacturers focused on innovation, reliability, and sustainability. Hitachi Energy led with over 35% market share in 2025, and the top five players—including Siemens Energy, GE Vernova, PFISTERER Holding SE, and Jiangxi Johnson—collectively held 64% of the market. These companies emphasize dry-type, oil-free insulation systems designed to meet high-voltage grid demands and minimize maintenance. Competitive advantage increasingly relies on insulation performance, lifecycle efficiency, and compliance with international reliability standards such as IEC 60137. Hitachi Energy and ABB dominate the premium segment with advanced polymer and epoxy technologies, while Eaton and GE strengthen their presence through grid modernization projects.
The RIP bushing value chain encompasses raw material suppliers (resin, paper, fiberglass), component manufacturers, OEM integrators (transformers and switchgear), and end-users (utilities and industrial operators). Key raw materials include epoxy resins, crepe paper, and aluminum conductors. Manufacturing involves specialized impregnation and curing processes, with quality control critical for partial discharge performance. OEMs such as Hitachi Energy, Siemens Energy, and GE Vernova integrate bushings into transformers and switchgear, while utilities specify and procure replacement bushings. The aftermarket and retrofit segment represents a significant revenue stream, particularly in mature markets with aging infrastructure.
Significant opportunities exist in the EHV and HVDC segment, where ASP premiums of 30–40% above conventional AC counterparts create value expansion. Emerging markets in Southeast Asia, Africa, and Latin America present grid build-out opportunities, although price sensitivity may limit adoption of premium RIP designs. Smart monitoring and condition-based maintenance services represent an emerging aftermarket revenue stream, with digital monitoring enabling predictive maintenance and extending asset life. The transition from OIP to RIP in retrofit applications offers a growing addressable market, particularly in Europe and North America where regulatory pressures and fire-safety concerns are most acute.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.6% from 2020-2034 |
| Segmentation |
|
By Application
By End Use
| By Geography |
|
The global RIP bushing market was valued at USD 592.7 million in 2025 and is projected to reach USD 1.23 billion by 2035, growing at a 7.6% CAGR.
Asia-Pacific leads the market with a 43% share, driven by China's State Grid build-out and India's renewable integration programs, followed by Europe at 23% and North America at 20%.
Hitachi Energy leads with over 35% market share, and the top five players—including Siemens Energy, GE Vernova, PFISTERER Holding SE, and Jiangxi Johnson—collectively hold 64% of the market.
Key drivers include global grid infrastructure investment reaching USD 400 billion in 2024, EHV and HVDC segment demand growing at 11.5% CAGR, and SF₆ phase-out regulations mandating dry-type bushings.
The market is projected to grow at a 7.6% CAGR from 2026 to 2035, with volume growing at 4.2% annually, indicating revenue growth driven primarily by ASP premiums.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Grid Asset Manager | 25% |
| Chief Engineer | 25% |
| Specification Consultant | 20% |
| Company Type | Representation (%) |
|---|---|
| Transformer OEMs | 35% |
| Switchgear Manufacturers | 20% |
| Utility Transmission Operators | 25% |
| EPC Contractors | 10% |
| Industrial End-Users | 10% |