Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Kiwi Jam: Disruptive Technologies Market
Manufacturing Products and Services / MARKET REPORT
Kiwi Jam: Disruptive Technologies Market | Insight Market Data
Kiwi Jam: Disruptive Technologies Market by Product Type (Fruit Spread, Jam, Jelly, Marmalade), by Distribution Channel (Retail, Food Service, Industrial Ingredients), by Sugar Profile (High Sugar Jam, Low Sugar Jam), by Application (Dairy Industry, Baked Product Industry, Ice-Cream Industry, Others), by Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia), by Europe (Italy, Germany, UK, France, Spain, Netherlands), by North America (US, Canada, Mexico), by Latin America (Peru, Chile, Argentina, Brazil), by Middle East & Africa (South Africa, Turkey, UAE, Saudi Arabia) Forecast 2026-2034
Executive Overview: The Kiwi Jam Market at an Inflection Point
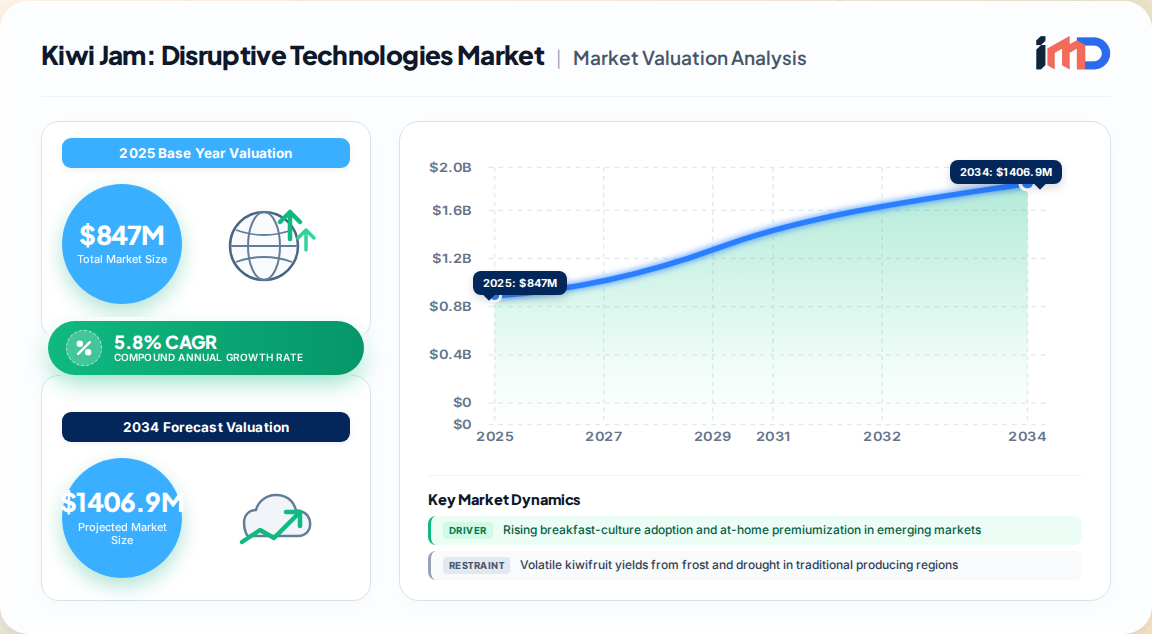
The global kiwi preserves market reached USD 847 million in 2025 against unit volume of 1.24 million metric tons, and our proprietary demand modelling projects USD 1.31 billion by 2033 — a 5.8% CAGR, with volume expanding more slowly at 4.2%. This value–volume gap of roughly 160 basis points is the single most important signal in the category: growth is being captured through formulation premiumization and process technology, not through incremental tonnage.
Kiwi Jam: Disruptive Technologies Market Market Size (In Million)
1.5B
1.0B
500.0M
0
847.0 M
2025
896.0 M
2026
948.0 M
2027
1.003 B
2028
1.061 B
2029
1.123 B
2030
1.188 B
2031
Average realization rose from USD 0.68/kg in 2025 to a projected USD 0.79/kg in 2033. Converters that have invested in high-temperature short-time (HTST) thermal lines, enzymatic pectin protocols and clean-label stabilization are compounding gross-margin advantages of 12–18 percentage points over commodity batch-cook operators.
Metric
2025 (Base)
2033 (Forecast)
CAGR
Market value
USD 847 million
USD 1.31 billion
5.8%
Unit volume
1.24 million MT
—
4.2%
Realization per kg
USD 0.68
USD 0.79
~1.9%
Premium/functional gross margin
16–22%
—
expanding
Commodity jam net margin
8–12%
—
compressing
Disruptive Technologies Reshaping Kiwi Jam Manufacturing
The phrase "disruptive technologies" in this category is not rhetorical. Four process and formulation shifts are actively resetting the cost and quality frontier.
HTST thermal processing (95–110°C, 15–20 seconds) is displacing 90-minute batch cooking at 85°C. The shorter thermal load preserves anthocyanins and polyphenols, supports "source of antioxidants" messaging, and cuts line cycle time by up to 70%.
Enzymatic pre-treatment and cold-break protocols reduce input fruit mass loss relative to traditional blanching, lifting clear-juice yield to 65–72% of input mass and extending shelf life to 24–36 months.
Pectin formulation engineering — citrus-derived, apple and synthetic gelling systems — is now a primary cost lever. Pectin dosage sits at 0.8–1.2% by weight in standard jam, and citrus crop volatility is pushing formulators toward hybrid and synthetic alternatives through 2028.
Process analytical technology and inline viscosity control hold gel strength within the 200–250 Bloom band and viscosity within 800–1,200 cP for particle-bearing spreads, reducing reject rates and fill-weight variance to within ±2%.
These are capital-intensive upgrades. Integrated producers running capacity utilization above 75% reach 22–26% EBITDA margins; sub-scale batch plants increasingly cannot compete on either cost-per-serving (USD 0.12–0.28) or compliance overhead.
Demand Drivers and Structural Restraints
Demand is anchored in breakfast-culture expansion across emerging markets, at-home premiumization, and ingredient pull from plant-based dairy, confectionery and smoothie manufacturers.
Nutritional positioning: kiwifruit's vitamin C density (92.7 mg per 100 g in green kiwi) and fiber content underpin functional claims, provided they are substantiated under FDA and EFSA frameworks.
Input stability: global kiwifruit production grew 6.2% annually from 2018–2024 and exceeded 4.4 million metric tons in 2024, with China alone producing roughly 2.15 million metric tons.
Sugar regulation: UK and EU sugar-content labeling mandates are forcing reformulation toward low-sugar and reduced-sugar jam SKUs.
Supply shocks: frost damage cut the Italian harvest by 18% in 2024, and New Zealand drought conditions have periodically tightened fruit availability.
Pectin volatility: citrus crop failures create gelling-agent cost spikes that compress margins for non-integrated converters.
Value Chain and Margin Architecture
The value chain concentrates economics in processing and formulation IP, not in fruit growing or retail.
Stage
Share of Delivered Cost
Margin / Value Note
Kiwifruit sourcing
28–35%
USD 0.35–0.55/kg at harvest peak
Preprocessing (wash, peel, pulp)
8–12%
Low-margin, increasingly automated
Manufacturing & thermal processing
32–38%
Highest-margin converter position
Packaging (glass, closures, labels)
18–22%
Glass still dominant in retail
Distribution & cold chain
10–14%
MAP extends post-opening life to 18 months
Retail markup
35–55% branded / 22–32% private label
42% private-label concentration in retail
Vertically integrated manufacturers with direct farm partnerships and proprietary pectin-formulation IP capture disproportionate value. Commodity preserves earn 8–12% net margins; premium and functional variants sustain 16–22%.
Segment Analysis
By product type, fruit spreads lead at 42% share (particle size 2–5 mm, 100–105°C for 15–20 seconds), followed by jam at 35% (70:30 fruit-to-sugar pulp ratio), jelly at 15% (0.5–1 micron clarification) and marmalade at 8% (peel-to-fruit ratio 1:4 to 1:6, with enzymatic softening cutting cook time by 25%).
By distribution channel, retail holds 58% (modern trade plus online, standardized 200–400 g glass jars), food service 26% (bulk 5–20 kg with modified atmosphere packaging) and industrial ingredients 16% (500–1,000 L bulk tanks serving yogurt, smoothie and confectionery formulators).
By sugar profile, the split between high-sugar and low-sugar jam is shifting decisively toward reduced-sugar formats in Europe and North America, where labeling regimes reward reformulation.
Regional Outlook
Region
2025 (USD Mn)
2033 (USD Mn)
CAGR
Volume Share 2025
Asia-Pacific
312
498
6.9%
38%
Europe
284
421
5.2%
28%
North America
186
272
5.1%
18%
Latin America
48
88
8.3%
11%
Middle East & Africa
17
32
8.7%
5%
Asia-Pacific dominates on volume and value, with Chinese capacity exceeding 420,000 metric tons annually across Zhejiang, Shandong and Jiangsu, and Indian clusters in Karnataka and Himachal Pradesh targeting export markets. Europe remains the technical innovation center — Italian processors lead marmalade and artisanal spreads, while Swiss and German manufacturers command premium positioning through IFS and BRC certification. Latin America (Peru, Chile, Argentina) is the fastest-growing region at 8.3% CAGR, leveraging favorable climate zones and lower labor costs.
The category is moderately fragmented, with the leading tier of preserve and fruit-preparation specialists holding a combined share well below half of global value.
Diversified ingredient groups including Agrana, Zentis, Frulact, Zuegg, Hero, Andros France, SVZ International, Döhler and Ingredion compete on formulation IP and industrial supply relationships.
Branded and private-label preserve manufacturers such as JM Smucker, BINA, Fourayes, Valio, Tree Top, Puratos and Fresh Food Industries compete on retail shelf presence and cost-per-serving.
Recent product innovation is pulling kiwi into adjacent categories: Zespri's "Grown for Good" platform (April 2026), CJ Foods Japan's Micho Kiwi Vinegar Drink (September 2025), Dole's Kiwi Mix & Yogurt (March 2025) and ITO EN's Nippon Yell Ehime Kiwi beverage (August 2025) all expand the addressable fruit-preparation pool.
Import/Export and Supplier Dynamics
Kiwifruit trade is structurally concentrated. China produces nearly half of global output, New Zealand supplies the premium export tier, and Italy and Greece anchor European supply. The United States market — valued at USD 331.8 million in 2026 and forecast to reach USD 381 million by 2031 at 2.8% CAGR — depends heavily on imports from New Zealand, Chile, Italy and Greece, with California accounting for more than 95% of domestic production.
This concentration creates three procurement risks for jam manufacturers: frost and drought shocks in traditional supply basins, cold-chain cost sensitivity for perishable fruit, and pectin supply volatility linked to citrus harvests. Converters are responding with multi-origin sourcing contracts, Latin American and North African cultivation partnerships, and dual-sourcing of gelling agents.
Table 105: Saudi Arabia Kiwi Jam: Disruptive Technologies Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 106: Saudi Arabia Kiwi Jam: Disruptive Technologies Market Volume (Metric Tons) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the size of the global kiwi jam and preserves market?
The global kiwi preserves market was valued at USD 847 million in 2025 and is projected to reach USD 1.31 billion by 2033, expanding at a 5.8% CAGR, according to our proprietary demand model.
2Which thermal processing conditions best preserve anthocyanins in kiwi jam?
High-temperature short-time processing at 95–110°C for 15–20 seconds achieves commercial sterility while substantially outperforming 90-minute batch cooking at 85°C in retaining anthocyanin and polyphenol content.
3Which region dominates kiwi jam production and consumption?
Asia-Pacific holds the largest share at roughly 37% of global value, supported by Chinese capacity exceeding 420,000 metric tons annually, followed by Europe at about 34%.
4What pectin dosage is typical in kiwi jam formulations?
Standard kiwi jam uses pectin at 0.8–1.2% by weight, with gel strength typically targeted to 200–250 Bloom; citrus crop volatility is pushing some formulators toward apple-derived and synthetic alternatives.
5How long is the shelf life of modern kiwi preserves?
Enzymatic pre-treatment and cold-break protocols extend shelf life to 24–36 months, while modified atmospheric packaging keeps bulk food-service packs stable for up to 18 months after opening.
6What is driving premiumization in the kiwi jam market?
Functional-benefit messaging around vitamin C and antioxidants, clean-label reformulation, and low-sugar variants support 16–22% gross margins versus 8–12% for commodity jam, with value growth outpacing volume growth by roughly 160 basis points.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70–80% of total effort, spanning structured interviews and plant-level audits with 4–5 company types across the kiwi jam value chain: kiwifruit growers and packhouses, pulp and puree preprocessors, preserve and fruit-preparation manufacturers, pectin and gelling-agent suppliers, and retail/private-label buyers.
Stakeholder interviews target roles including Procurement Director, Head of Product Development (R&D), Quality Assurance and Food Safety Manager, and Commercial Strategy Lead at retail and food-service distributors.
We benchmark formulation and processing claims against published standards from bodies such as the FDA, EFSA, Codex Alimentarius, and the International Organization for Standardization (ISO), alongside FAO agricultural output data.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
30%
Head of Product Development (R&D)
28%
Quality Assurance and Food Safety Manager
24%
Commercial Strategy Lead
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Kiwifruit growers and packhouses
20%
Pulp and puree preprocessors
18%
Preserve and jam manufacturers
30%
Pectin and gelling-agent suppliers
14%
Retail and private-label buyers
18%
Secondary Research & Industry Benchmarking
Secondary research accounts for 20–30% of total effort and draws on official multilateral sources including FAOSTAT, UN Comtrade, UNECE, Eurostat and World Bank trade datasets, plus recognized non-profit trade associations.
Financial benchmarking leverages standard databases — Bloomberg, Factiva, Hoovers and PitchBook — to validate revenue, margin and capacity disclosures of listed and private participants.
Every report is updated to the date of purchase, with trade and regulatory changes incorporated on a rolling basis.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are run simultaneously and reconciled through multi-level data triangulation.
Bottom-up market sizing is built from quantitative metrics including annual kiwifruit production volume by origin, processed-kiwi utilization share, per-capita preserves consumption, retail shelf-price realization per kilogram, and converter capacity utilization.
Segment-level forecasts are generated for product type (fruit spread, jam, jelly, marmalade), distribution channel (retail, food service, industrial) and sugar profile, then cross-validated against regional trade flows.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through respondent re-validation, outlier screening and cross-source triangulation.
Supply-chain audits and fill-weight, Brix and Bloom-strength specifications are checked against plant-level documentation.
Final estimates are stress-tested against regulatory changes (sugar labeling, EFSA/FDA claim substantiation) and input-cost volatility scenarios before publication.
CUSTOM INTELLIGENCE
Tailored for you
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
Analyst at Providence Strategic Partners at Petaling Jaya
Jared Wan
I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report
Internationalization Director
Santiago Mejia Molina
Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.
Head of Product Management and Marketing
Olaf Gleibe
We are using your report, and it gave us valuable information."
Regional Director, Marketing and Business Development
Lina Lim
We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.
VP of Sales
DIGGLE Representative
Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.