1What is the current size of the K12 coding courses market?
The global K12 coding courses market was valued at USD 2.4 billion in 2025 and is projected to reach USD 5.7 billion by 2035, growing at a CAGR of 8.7%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 K12 Coding Courses Market
 by Product Type (Online Courses, Coding Toys and Tools, Workshops and Bootcamps, Others), by Application (School Curriculum Integration, Extracurricular Programs, Private Tutoring, Others), by Technology (Gamified Learning, Learning Management Systems, AI and Machine Learning, Others), by Grade Level (Elementary School, Middle School, High School, Others), by End-User (Schools, Private Tutors, Educational Institutions, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, India, Japan, South Korea, Singapore, Australia, Rest of Asia Pacific), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (GCC Countries, South Africa, Rest of MEA) Forecast 2026-2034

Senior Research Analyst

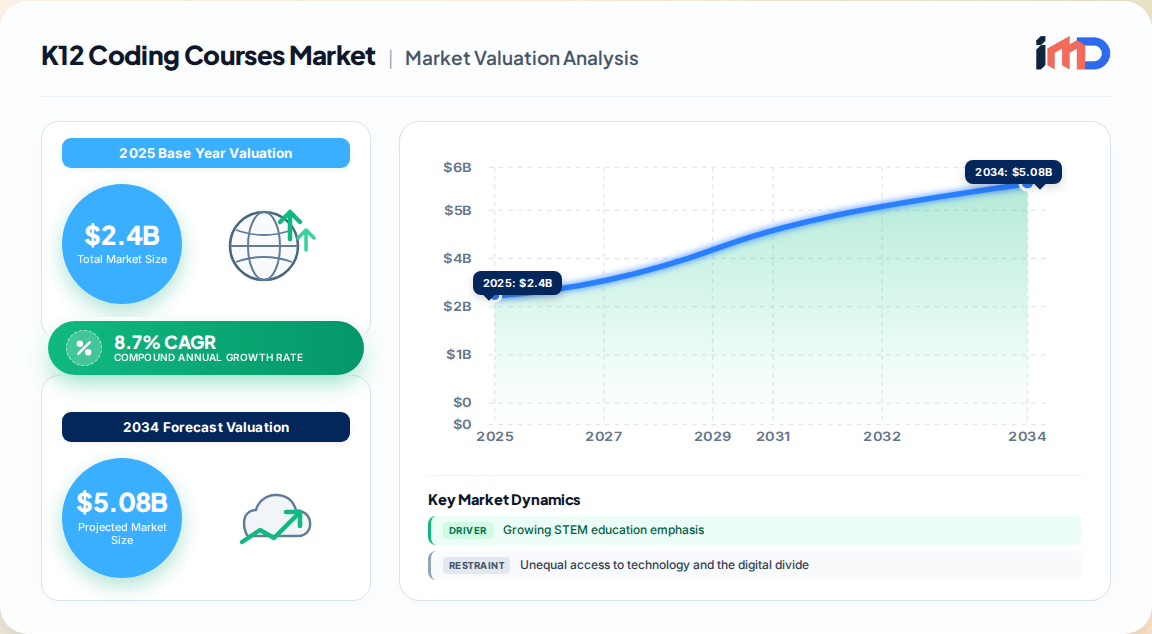
The global K12 coding courses market is undergoing a structural transformation, driven by the systemic integration of computer science into primary and secondary education. Our proprietary primary research estimates the market at USD 2.4 billion in 2025, with a projected expansion to USD 5.7 billion by 2035, reflecting a robust CAGR of 8.7%. This growth is not merely a pandemic-induced anomaly but a fundamental reallocation of educational expenditure toward digital literacy as a core competency.
The market encompasses instructional content, platforms, and tools designed to teach coding and programming skills to students from kindergarten through 12th grade. It has evolved from an extracurricular enrichment activity to a curriculum-embedded requirement across more than 40 countries, creating a recurring, institutionalized demand base.
| Driver | Impact on CAGR | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growing STEM Education Emphasis | +1.5% | Global | Medium to Long Term |
| Technological Advancements in EdTech | +1.2% | North America, Europe | Medium Term |
| Increased Government Initiatives | +1.1% | Asia-Pacific, Europe | Short to Medium Term |
| COVID-19 Pandemic Effects on Online Learning | +0.9% | Global | Short Term |
| Increasing Demand for Qualified Workforce | +0.8% | North America, Asia-Pacific | Long Term |
| Rising Investment in EdTech Startups | +0.7% | Global | Medium Term |
The K12 coding courses market is segmented by product type, application, technology, and grade level. The online courses segment dominates, accounting for 50% of product-type revenue, driven by accessibility and scalability.
| Segmentation Basis | Leading Segment | Share / Contribution |
|---|---|---|
| By Product Type (40%) | Online Courses | 50% |
| Coding Toys and Tools | 25% | |
| Workshops and Bootcamps | 15% | |
| By Application (30%) | School Curriculum Integration | 60% |
| Extracurricular Programs | 30% | |
| Private Tutoring | 10% | |
| By Technology (20%) | Gamified Learning | 45% |
| Learning Management Systems (LMS) | 35% | |
| AI and Machine Learning | 20% | |
| By Grade Level | High School | 71.3% (of end-user share) |
| Middle School | Growing at fastest rate | |
| Elementary School | Foundational segment |
North America leads the global market with a 35% share, valued at approximately USD 1.32 billion in 2025. The region benefits from:
The fastest-growing region, projected to expand at a CAGR of 16.4% through 2035, capturing an estimated 29% of global revenue.
Europe accounted for approximately 21% of global market share in 2025, growing at an estimated CAGR of 12.1% through 2035.
The K12 coding courses market is moderately concentrated, with a mix of global EdTech platforms, curriculum providers, and regional bootcamps. Key players are pursuing strategies centered on AI personalization, gamification, and institutional partnerships.
| Strategic Initiative | Description |
|---|---|
| AI Integration | Platforms are embedding AI-driven adaptive learning engines to reduce dropout rates and improve course completion metrics. Top platforms report completion rates as high as 78%, versus the traditional MOOC average of under 15%. |
| Gamification | Game-based learning is being deployed to enhance student engagement, particularly in elementary and middle school segments. |
| Public-Private Partnerships | Companies such as Google, Microsoft, and Amazon have collectively committed more than USD 1.5 billion toward K12 computer science education initiatives between 2023 and 2026. |
| Mergers and Acquisitions | Strategic acquisitions are enabling platform providers to expand their offerings and geographic reach. |
The market is witnessing a technology-driven transformation, with gamification and AI/ML as key trends. Active product development and R&D investment are focused on:
The K12 coding courses value chain comprises content developers, platform providers, distributors, and end-users. Key dynamics include:
While the K12 coding courses market is primarily digital, the coding toys and tools segment (25% of product-type revenue) involves physical supply chains, including hardware components and educational kits. Trade data on physical coding tools is fragmented, but the overall supply chain faces limited risk compared to traditional educational hardware. Key considerations include:
The K12 coding courses market is positioned for sustained double-digit growth trajectory, underpinned by structural forces including national STEM mandates, workforce demands, and technological innovation. The transition from discretionary enrichment to core curriculum integration creates a recurrent, institutionalized demand base that distinguishes this market from other education segments. Asia-Pacific represents the most significant growth frontier, while North America remains the largest and most mature market. Stakeholders should prioritize investments in AI-driven personalization, gamified content, and public-private partnerships to capture emerging opportunities. The market's future is one where coding is not an elective, but a fundamental literacy, seamlessly integrated into the educational fabric of nations worldwide.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.7% from 2020-2034 |
| Segmentation |
|
By Technology
By Grade Level
By End-User
| By Geography |
|
The global K12 coding courses market was valued at USD 2.4 billion in 2025 and is projected to reach USD 5.7 billion by 2035, growing at a CAGR of 8.7%.
North America holds the largest share at approximately 35% of the global market, valued at around USD 1.32 billion in 2025, driven by strong digital infrastructure and government initiatives like Computer Science for All.
Key drivers include growing STEM education emphasis (+1.5% CAGR impact), technological advancements in EdTech (+1.2%), and increased government initiatives (+1.1%), particularly in Asia-Pacific and Europe.
Online courses dominate the product-type segment with a 50% share, while school curriculum integration leads application segments at 60%. Gamified learning is the fastest-growing technology segment at 45%.
AI-powered personalized learning, gamification, and the integration of LMS platforms are key trends. Public-private partnerships and corporate scholarship programs are also shaping the market landscape.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CEO / Founder | 25% |
| Product Manager | 30% |
| Curriculum Director | 25% |
| Procurement Officer | 20% |
| Company Type | Representation (%) |
|---|---|
| EdTech Platform Providers | 35% |
| Curriculum Content Developers | 25% |
| Coding Bootcamps and Enrichment Providers | 20% |
| School Districts and Educational Institutions | 15% |
| Coding Toy and Hardware Manufacturers | 5% |
 Related Reports
