Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Manufacturing Products and Services / MARKET REPORT
Porcelain Vitrified Tiles Market | Insight Market Data
Porcelain Vitrified Tiles Market by By Product Formulation (Full-body Vitrified Porcelain, Glazed Vitrified Porcelain, Double-Charge Vitrified, Soluble-Salt Vitrified, Gauged Thin Panels), by By Application (Floor Tiles, Internal Wall Tiles, External Wall Tiles, Countertops and Furniture Surfaces), by By End-Use (Residential, Commercial, Industrial), by By Construction Type (New Construction, Renovation and Replacement), by By Distribution Channel (Large Home Centers, Independent Retailers, Specialty Tile and Stone Stores, Online Retail, Direct Sales to Contractors), by Asia-Pacific (China, India, Vietnam, Indonesia, Japan), by Europe (Italy, Spain, Germany, UK, France), by North America (USA, Canada, Mexico), by South America (Brazil, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, Nigeria, South Africa) Forecast 2026-2034
Global kiwi jam and preserves market at $847M in 2025, rising to $1.31B by 2033 at 5.8% CAGR, driven by HTST processing, pectin and clean-label innovation.
Nov 2026|271 pages
$2900.00
K12 coding courses market valued at $2.4B in 2025, projected to reach $5.7B by 2035 at 8.7% CAGR. Explore segments, regional insights & key trends.
Nov 2026|231 pages
$2900.00
Digital Twin in Oil & Gas market to reach USD 911.72 Million by 2032, growing at 26.54% CAGR. Explore drivers, trends, and regional insights.
Executive Overview: The Porcelain Vitrified Tiles Market
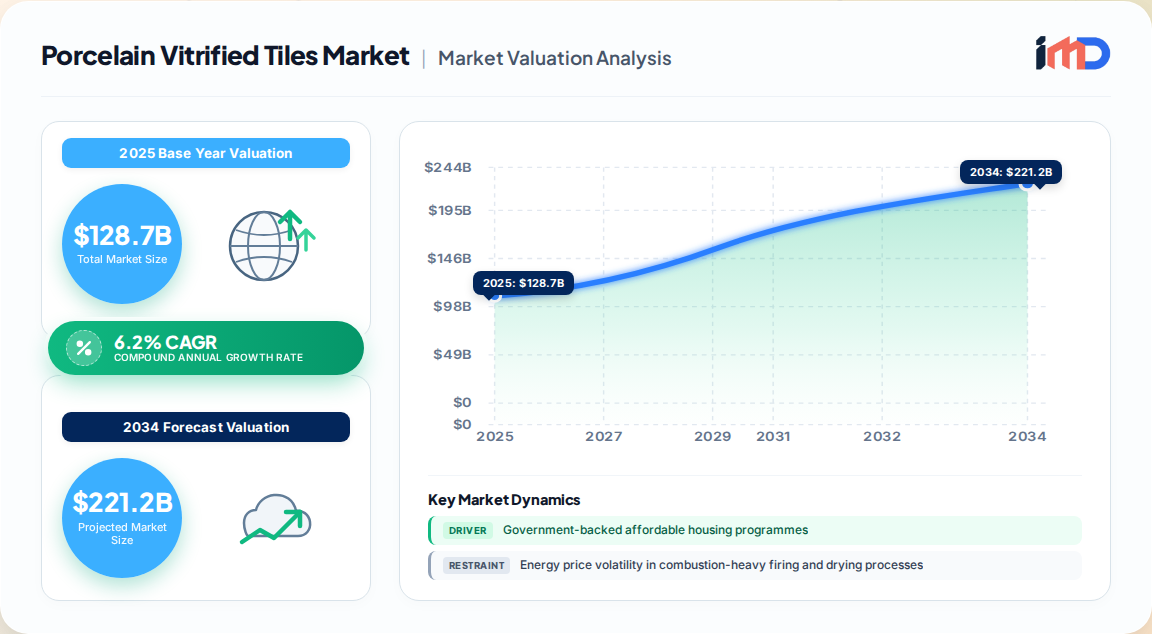
The global porcelain vitrified tiles market represents the most technologically advanced and fastest-value-accreting tier of the broader ceramic surfacing industry. Our proprietary 2025 baseline assessment values this segment at USD 128.7 Billion, equivalent to roughly 75.6% of the total ceramic tile market, and projects expansion to USD 235.9 Billion by 2035 at a CAGR of 6.2%.
Porcelain Vitrified Tiles Market Market Size (In Billion)
200.0B
150.0B
100.0B
50.0B
0
128.7 B
2025
136.7 B
2026
145.2 B
2027
154.2 B
2028
163.7 B
2029
173.9 B
2030
184.6 B
2031
The defining characteristic of this market is its technical specificity: vitrified porcelain is classified under ISO 13006 Group BIa, requiring water absorption at or below 0.5% and a minimum bending strength of 32 N/mm². These thresholds disqualify conventional glazed ceramic and unglazed product families from the definition, making porcelain vitrified tiles a distinct premium-performance category rather than a decorative variant.
Global production capacity reached an estimated 14.95 billion square meters in 2024, down 6.2% year-on-year, with porcelain vitrified formats gaining share within a contracting volume base.
Average service life of approximately 50 years underpins replacement-cycle stability and supports long-duration demand modelling.
Asia-Pacific commands 54% of global value, led by China's installed capacity and India's Morbi manufacturing cluster.
Market Drivers: Structural Demand Anchors
Demand growth in porcelain vitrified tiles is anchored in four durable structural forces, each quantified through our primary interview programme.
Driver
Estimated CAGR Contribution
Geographic Concentration
Impact Horizon
Government-backed affordable housing programmes
+1.4%
Asia-Pacific, Middle East & Africa, South America
Long-term (4+ years)
Urbanisation and household formation
+1.1%
Asia-Pacific, Africa
Long-term (4+ years)
Large-format and gauged porcelain adoption
+0.8%
Global
Medium-term (2–4 years)
Renovation and energy-retrofit policy
+0.7%
Europe, North America
Medium-term (2–4 years)
Digital inkjet decoration and design velocity
+0.6%
Global
Short-term (up to 2 years)
Affordable housing pipelines are the single largest volume lever. India's PMAY-Urban 2.0 has sanctioned cumulative approvals exceeding 2.08 million homes, with central assistance of INR 2.30 lakh crore. Saudi Arabia's Vision 2030 targets 70% homeownership by 2030, while Brazil's Minha Casa, Minha Vida programme targets 2 million homes. Each unit requires finished wet-area surfacing, creating predictable multi-year offtake.
Urbanisation compounds the effect. The United Nations projects the global urban population share will reach 68% by 2050, up from 55% in 2018, with close to 90% of the increment concentrated in Asia and Africa. Falling household sizes multiply dwelling requirements per thousand people.
Large-format adoption is a revenue accelerator, not merely a volume driver. Gauged porcelain panels, now codified under ANSI A137.3, permit thin formats on façades, countertops and furniture. Larger panels mean fewer joints, faster installation and materially higher value per square meter, lifting revenue faster than tonnage.
Restraints and Challenges
Energy cost volatility is the dominant margin risk. Porcelain manufacturing requires 30–40 kWh per square meter, concentrated in combustion-heavy firing and drying stages. Natural gas price shocks in the Morbi cluster alone can swing segment CAGR by an estimated -1.5% in the near term.
Emissions compliance pressure. Benchmarked emission factors of approximately 300 kg CO₂/Mg, 1.6 kg CO/Mg, 0.27 kg NOx/Mg, 2.4 kg SO₂/Mg and 0.23 kg HF/Mg impose retrofit capital expenditure, particularly for smaller operators.
Trade friction in export corridors. Anti-dumping actions and destination-market certification barriers constrain export-led growth from low-cost production clusters.
Housing cycle cyclicality. New construction still represents the majority of consumption, exposing volume to interest-rate and credit conditions.
Regulatory and Standards Framework
The porcelain vitrified category is unusually standards-defined, which creates both a barrier to entry and a quality signal for specifiers.
ISO 13006 classifies tiles by water absorption, with Group BIa (at or below 0.5%) defining vitrified porcelain.
HS code 690721 covers ceramic flags, paving, hearth and wall tiles with water absorption not exceeding 0.5%, providing the primary customs-level proxy for tracking trade in this category.
EU Directive (EU) 2024/1275 and the recast Energy Performance of Buildings Directive require all new buildings to be zero-emission from 2030, steering specification toward durable, low-maintenance surfaces.
The EU ceramics sector sustains over 338,000 jobs and €27.8 billion in annual production value, with SMEs forming the manufacturing bulk.
Import/Export and Supplier Dynamics
Trade flows in porcelain vitrified tiles are structurally concentrated around a small number of export-oriented clusters.
Italy produced approximately 388 million square meters in 2025, up 5% year-on-year, with exports reaching about 300 million square meters — an export ratio near 78%.
Spain recorded sector turnover of €4,834 million in 2025, with exports contributing €3,484 million against domestic sales of €1,350 million.
Brazil produced 817 million square meters in 2025, ranking third globally in production, third in consumption and seventh in exports.
The United States consumed 2.57 billion square feet in 2025, down 4.9%, with imports of 1.86 billion square feet representing 72.4% of consumption by volume — one of the most import-dependent major markets.
Supply chain risk is concentrated in two nodes: fuel energy for firing and freight logistics for high-density finished goods. The Strait of Hormuz disruption risk materially affects delivered energy cost into the Morbi cluster, and producers with multi-fuel kiln capability hold a measurable cost advantage. Raw material exposure is moderate: global ceramic industries consume approximately 140 million tonnes of raw clay annually, but clay is geologically abundant and feldspar supply is diversified — U.S. domestic feldspar production reached 440,000 tons valued at USD 49 million in 2025, with ceramics and pottery absorbing 53% of end-use.
Segmentation Analysis
By Product Formulation:
Full-body vitrified porcelain leads on specification in commercial and high-traffic applications.
Glazed vitrified porcelain (GVT) dominates residential value, supported by digital inkjet decoration now applied to the majority of glazed output globally.
Double-charge and soluble-salt formats retain positions in value-tier residential markets.
Gauged thin panels are the fastest-growing format, expanding revenue per square meter.
By Application: Floor installations account for the largest share, driven by mandatory use in wet areas and high-traffic corridors. Wall applications are growing faster, supported by textured and 3D feature walls in hospitality and retail.
By End-User: Residential demand dominates volume, led by kitchen and bathroom remodelling and new multifamily housing. Commercial demand grows faster on hygiene-driven specification in offices, healthcare and retail.
By Construction Type: New construction holds the majority share as greenfield housing integrates tile at design stage, while renovation and replacement grows faster and provides the most effective hedge against housing-cycle swings.
By Distribution Channel: Direct contractor sales and large home centres dominate bulk procurement. Online retail is the fastest-moving channel, enabled by visualiser tools and sample-box logistics.
India deserves separate emphasis. The India ceramic tiles market is valued at USD 11.3 Billion in 2026, projected to reach USD 17.77 Billion by 2032 at a 7.78% CAGR. Vitrified tiles hold roughly 30% of Indian product mix, with porcelain the fastest-growing segment at an 11.05% CAGR. West India accounts for 35.15% of domestic sales value, while South India grows fastest at 9.95%.
Format capability is the decisive competitive variable. Suppliers qualified for large-format slab production capture spending that established producers with legacy product mixes cannot serve. Capacity additions for larger sizes are the clearest strategic response observed in our interview programme.
Energy transition as a pricing weapon. Hydrogen-ready kiln investment creates value only if delivered fuel cost per unit of heat undercuts piped natural gas. Producers who close that gap convert firing-cost advantage directly into price competitiveness.
Digital design velocity. Inkjet decoration permits design changes without retooling, compressing design cycles and enabling mass customisation for small builders.
Circularity as specification leverage. Up to 90% of broken ceramic tile waste can be reused as road sub-base material in some regions, a credential increasingly material to public procurement scoring.
Channel white space exists in online retail and in digitally enabled design-data business models, both underpenetrated relative to their growth trajectory.
Outlook Summary
The porcelain vitrified tiles market will expand value faster than volume through 2035, driven by format migration toward large panels, premiumisation in residential renovation, and policy-anchored affordable housing delivery. The principal risks are energy cost volatility and emissions-compliance capital intensity, both of which favour scaled operators with multi-fuel capability and access to lower-cost capital.
Table 56: South Africa Porcelain Vitrified Tiles Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the porcelain vitrified tiles market size in 2025?
Our proprietary assessment values the global porcelain vitrified tiles market at USD 128.7 Billion in 2025, representing approximately 75.6% of the total ceramic tile market. This segment is projected to reach USD 235.9 Billion by 2035, expanding at a 6.2% CAGR.
2What water absorption level defines porcelain vitrified tiles?
Under ISO 13006, vitrified porcelain falls into Group BIa, which requires water absorption at or below 0.5%. This group also carries a minimum bending strength requirement of 32 N/mm², materially above the 22 N/mm² threshold for floor tiles with 3–6% absorption. HS code 690721 is the corresponding customs classification.
3Which region dominates the porcelain vitrified tiles market?
Asia-Pacific holds approximately 54% of global value, anchored by China's installed capacity and India's Morbi manufacturing cluster. India alone represents USD 11.3 Billion in 2026, with porcelain tiles growing at an 11.05% CAGR through 2032.
4Why are large-format porcelain panels growing so quickly?
Gauged porcelain panels, now standardised under ANSI A137.3, absorb 0.5% of water or less, allowing thin formats to perform outdoors and on façades. Fewer joints and faster installation lift value per square meter, so revenue grows faster than volume.
5What is the biggest cost risk for porcelain vitrified tile manufacturers?
Energy cost volatility is the primary margin risk. Manufacturing consumes 30–40 kWh per square meter, concentrated in firing and drying. Natural gas price fluctuations in the Morbi cluster can swing near-term segment growth by an estimated -1.5%.
6How dependent is the U.S. market on imported tiles?
Highly dependent. U.S. ceramic tile consumption reached 2.57 billion square feet in 2025, with imports of 1.86 billion square feet accounting for 72.4% of consumption by volume. This makes North America a priority export destination for European and Asian producers.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of total research effort is allocated to primary intelligence gathering, conducted continuously across the 2025–2026 base period.
Structured interviews and survey instruments are deployed across 4–5 highly specific company types in the porcelain vitrified tiles value chain: continuous-compaction press and kiln equipment OEMs, digital inkjet glaze and ink suppliers, mid-to-large scale tile manufacturers (Morbi, Sassuolo and Castellón clusters), regional tile distributors and importers, and commercial specifiers including architectural practices and fit-out contractors.
We interview 3–4 specific stakeholder designations per organisation: Plant Operations Director, Procurement and Sourcing Head, Specification and Design Lead (Architect or Interior Architect), and Commercial or Export Sales Manager.
All primary respondents are screened for direct purchasing or specification authority, with a minimum of five years of category experience.
Guaranteed estimated data accuracy level of 85–90%, with confidence bands documented for each segment estimate.
20–30% of effort is directed to secondary validation and benchmarking against official and non-profit sources.
Standard financial and corporate databases utilised: Bloomberg, Factiva, Hoovers, and PitchBook for company financial disclosures, capital expenditure, and ownership structures.
Official governmental and multilateral sources include UN Comtrade for HS 690721 trade flows, Eurostat for EU ceramics production statistics, USGS for feldspar and clay mineral supply data, and United Nations population and urbanisation projections.
Technical standards and non-profit bodies referenced: ISO 13006 (water absorption classification), ANSI A137.3 (gauged porcelain panels), ASTM test methods, and recognised national tile trade associations for production and consumption statistics.
Regulatory instruments tracked: EU Directive (EU) 2024/1275, the recast Energy Performance of Buildings Directive, and the European Green Deal emissions framework.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are applied simultaneously and reconciled through multi-level data triangulation.
Bottom-up estimation aggregates four quantitative metrics: (1) square meters of porcelain vitrified tile produced and consumed by country, (2) average selling price per square meter by format and grade, (3) sanctioned and completed housing units in affordable-housing programmes, and (4) renovation and replacement expenditure share of domestic surfacing spend.
Top-down estimation begins with total ceramic tile market value and applies a segment-specific share derived from ISO 13006 product-mix tracking and HS 690721 customs volumes.
Producer shipment data, company financial disclosures, and construction activity statistics are reconciled against consumption volumes and regional average selling prices to produce the final forecast.
Historical values are expressed in nominal USD at average annual exchange rates; forecasts assume stable currency parities from the 2025 base year.
Every report is updated to the date of purchase, with the baseline refreshed against the latest available production and trade releases.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90%, enforced through a three-stage validation protocol.
Stage one: cross-validation of each estimate against at least two independent source families (primary interviews and official trade statistics).
Stage two: multi-level data triangulation, comparing top-down segment shares against bottom-up volume-weighted values, with variances above 8% flagged for re-work.
Stage three: expert panel review by senior analysts with direct sector operating experience in the porcelain and vitrified tile clusters.
Confidence bands, base-year assumptions, and any reconciliation adjustments are disclosed transparently in the report scope section.