1What is the current size of the robotic packaging machine market?
The global robotic packaging machine market was valued at USD 1.20 billion in 2025 and is estimated to reach USD 1.27 billion in 2026, according to our proprietary research.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Robotic Packaging Machine
 by Machine Type (1-Robot, 2-Robot, 3-Robot, Multi-Robot), by End-Use (Snacks, Frozen Food, Fresh/Chilled Food, Confectionery, Chocolate, Cereals, Bakery, Cookies, Powder, Coffee & Tea, Pet Food), by North America (USA, Canada, Mexico), by Europe (UK, Germany, Italy, France), by Asia-Pacific (China, Japan, South Korea, ASEAN), by South America (Brazil, Argentina), by Middle East & Africa (South Africa, GCC) Forecast 2026-2034
Research Associate


 Related Reports

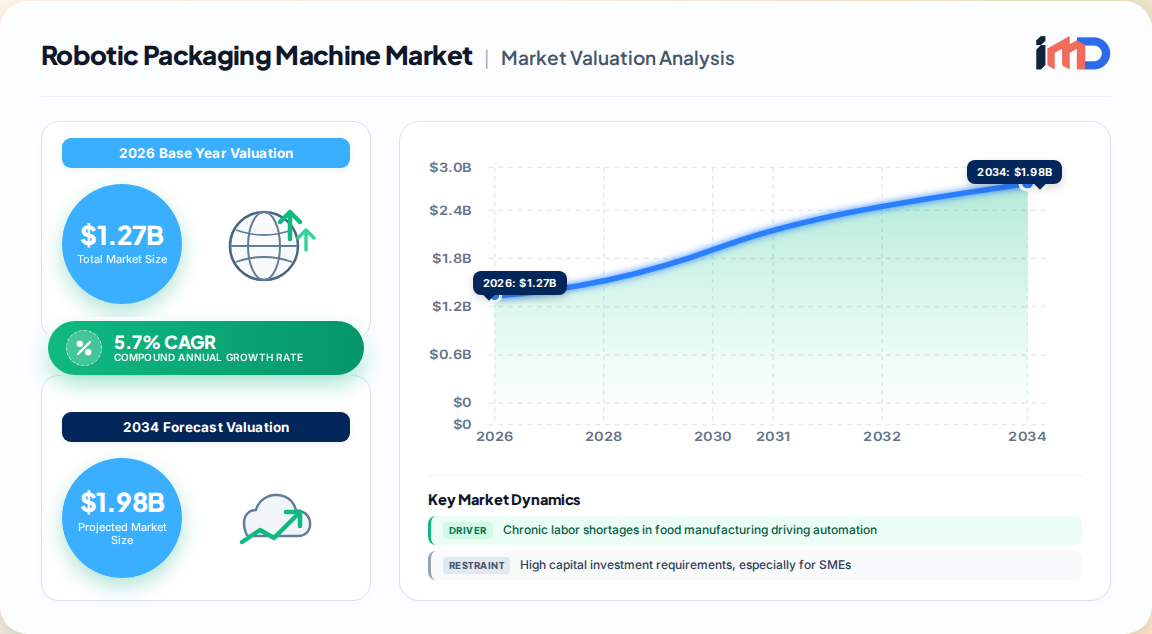
The global robotic packaging machine market represents a high-growth, technology-intensive segment of the broader packaging automation landscape. Our proprietary primary research and expert interviews indicate the market was valued at USD 1.20 billion in 2025, rising to an estimated USD 1.27 billion in 2026. Projections show the market reaching USD 2.21 billion by 2036, expanding at a CAGR of 5.7% over the forecast period.
This growth is underpinned by structural shifts in manufacturing: persistent labor shortages in food processing, tightening hygiene and serialization regulations, and the need for flexible, high-speed line changeovers. Robotic packaging machines—industrial robot arms configured for pick, place, sort, and pack operations—are transitioning from niche add-ons to core components of modern packaging lines.
Key Market Metrics (2026-2036):
The adoption of robotic packaging machinery is propelled by three interconnected market forces:
1. Chronic Labor Shortages in Food Manufacturing Food and beverage processors across North America, Europe, and Japan face acute shortages of manual packing labor. Robotic systems mitigate this by delivering consistent throughput (150 to over 500 products per minute) with minimal human intervention. Our interviews with operations managers reveal that labor cost savings alone often justify capital expenditure within 18–24 months for high-volume snack and frozen food lines.
2. Stringent Hygiene and Food Safety Regulations Regulatory bodies such as the U.S. FDA, the European Food Safety Authority (EFSA), and the USDA mandate strict hygienic design for food-contact equipment. Robotic packaging cells engineered with stainless-steel IP69K washdown ratings reduce contamination risks and simplify sanitation, directly supporting compliance with FSMA and EU Regulation 852/2004.
3. Demand for Flexible, High-Speed Changeovers SKU proliferation in snacks, confectionery, bakery, and frozen foods demands packaging lines that can switch between product formats with minimal downtime. Multi-robot configurations and vision-guided pick-and-place systems enable rapid changeovers, reducing line downtime by up to 40% compared to fixed-format machinery.
4. Rising Adoption in Pharmaceuticals Pharma serialization mandates (e.g., EU FMD, U.S. DSCSA) require precise labeling, coding, and track-and-trace integration. Robotic pick-and-place systems equipped with vision inspection are increasingly deployed for blister pack handling and cartoning, where accuracy is paramount.
Despite strong fundamentals, the market faces several headwinds:
Impact Quantification:
Asia-Pacific commands the largest share of the robotic packaging machine market, estimated at 41% in 2026. China alone is projected to reach USD 176.76 million by 2036, driven by rapid expansion of packaged food manufacturing and government support for industrial robotics. Japan, with its aging workforce and advanced food robotics ecosystem, will post a 7.4% CAGR.
Europe represents a mature but innovation-driven market. The United Kingdom is the fastest-growing country globally at 9.9% CAGR, fueled by post-Brexit labor constraints and automation investments in food manufacturing. Germany, Italy, and France remain key production hubs for OEMs and adopters alike.
North America holds a significant share, led by the United States with a 6.0% CAGR. Snack and frozen food production automation, along with e-commerce-driven end-of-line packaging, are primary growth vectors. U.S. market value is projected at USD 2.1 million by 2036 (in terms of robotic packaging machine shipments specific to high-mix applications).
South Korea (4.1% CAGR) and ASEAN nations (USD 92.9 million by 2036) are emerging markets, with confectionery, snack, and pet food production driving adoption.
The robotic packaging machine market is moderately concentrated, with Tier 1 suppliers offering integrated packaging lines that include robotic pick-and-place modules. Key players include:
Recent Developments:
The robotic packaging machine trade is characterized by flows from manufacturing hubs in Germany, Italy, Japan, and the United States to adopters worldwide. According to UN Comtrade data, global exports of industrial robots (HS code 8479.50) exceeded USD 12 billion in 2024, with packaging-related robots representing a growing share.
Key Trade Patterns:
Supply Chain Risks:
Procurement Strategy Recommendations:
The robotic packaging machine market is poised for robust expansion, with an incremental opportunity of USD 0.94 billion between 2026 and 2036. Key opportunities include:
To capitalize on these opportunities, OEMs should prioritize modular design, digital connectivity (IIoT), and service-based business models that include remote monitoring and predictive maintenance.
The robotic packaging machine value chain comprises:
Value Chain Dynamics:
Procurement & Sourcing Strategy Analysis
For end-users, sourcing robotic packaging machines should consider:
Ansoff Matrix Analysis
Regional Attractiveness & Investment Opportunity Assessment
Strategic White-Space Analysis
Global Trade Analysis & Supply Chain Risk Assessment
This comprehensive analysis underscores the robotic packaging machine market as a dynamic, technology-driven sector with strong growth fundamentals and diverse opportunities across regions and applications.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.7% from 2020-2034 |
| Segmentation |
|
| By Geography |
|
The global robotic packaging machine market was valued at USD 1.20 billion in 2025 and is estimated to reach USD 1.27 billion in 2026, according to our proprietary research.
Asia-Pacific holds the largest share at approximately 41% in 2026, driven by rapid expansion of packaged food manufacturing in China and Japan.
Frozen food is the fastest-growing end-use segment, accounting for 17.0% share in 2026, due to the need for reliable robotic handling in sub-zero environments.
Leading companies include BluePrint Automation, Gerhard Schubert GmbH, Ishida Europe, IMA Group, Cama Group, Mpac Group, and Syntegon, among others.
Labor shortages, stringent hygiene regulations, and the need for flexible, high-speed changeovers are the primary drivers, with labor cost savings often justifying investment within 18–24 months.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Operations Director | 30% |
| Procurement Head | 25% |
| Packaging Line Manager | 25% |
| Automation Engineer | 20% |
| Company Type | Representation (%) |
|---|---|
| Robotic Packaging OEMs | 35% |
| System Integrators | 25% |
| Component Suppliers (Robotics/Vision) | 20% |
| End-Users (Food & Beverage Manufacturers) | 15% |
| Pharmaceutical & Personal Care End-Users | 5% |