About Insight Market Data

Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.

Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

report thumbnailRetail Business in Thailand Market
Retail / MARKET REPORT

Retail Business in Thailand Market | Insight Market Data

Retail Business in Thailand Market by Product Type (Food, Beverage and Tobacco Products, Apparel, Footwear and Accessories, Personal Care and Household Care, Home and Garden, Others), by Retail Channel (Traditional Mom and Pop Retail, Modern Trade Retail, E-commerce and Others), by Format (Convenience Stores, Supermarkets, Hypermarkets, Department Stores, Specialty Stores, Others), by Bangkok Metropolitan, by Central & Eastern, by Northeastern (Isan), by Northern, by Southern Forecast 2026-2034

© Oct 31, 2026|Base Year: 2025|255 Pages
Vijayashree Ugale

Vijayashree Ugale

Research Analyst

Main Logo

Retail Business in Thailand Market: Size, Trends & Forecast


/
/
Buy Now
Home
Industries
Retail
Independent Intelligence for decisions that move markets
+12315155523[email protected]
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Main Logo
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Talk to an analyst

Business Address

Head Office

Ansec House 3 rd floor Tank Road, Yerwada, Pune, Maharashtra 411014

Contact Information

Craig Francis

Business Development Head

+12315155523

[email protected]

Secure Payment Partners

payment image

© 2026 PRDUA Research & Media Private Limited, All rights reserved

••
Retail
Logistics
Packaging
Automotive
Healthcare
Agriculture
Energy & Power
Food & Beverage
Aerospace & Defense
Chemicals & Materials
Hospitality and Tourism
Consumer Goods and Services
Animal Nutrition & Wellness
Real Estate and Construction
Home and Property Improvement
Technology, Media and Telecom
Manufacturing Products and Services
Financial Services and Investment Intelligence
Privacy Policy
Terms and Conditions
FAQ
artwork spiralartwork spiralRelated Reports
artwork underline

Malaysia Luxury Goods Market Size, Share & 2031 Forecast

Malaysia Luxury Goods Market valued at USD 2.31 Billion in 2026, growing at 6.05% CAGR to reach USD 3.1 Billion by 2031. Read our proprietary report.

Nov 2026|274 pages
$2900.00View report

Retail Analytics Industry market valued at USD 12.22 Billion in 2026, projected to reach USD 49.03 Billion by 2035 at a CAGR of 16.74%.

Nov 2026|193 pages
$2900.00

The US retail colocation market is valued at USD 7.36 billion in 2025, growing at a 12.54% CAGR to reach USD 23.97 billion by 2035, driven by AI, hybrid cloud, and interconnection demand.

Nov 2026|278 pages
$2900.00

Australia hair care market to reach USD 2.14 billion by 2031, growing at 3.91% CAGR from USD 1.76 billion in 2026. Explore trends, segments & key players.

Nov 2026|254 pages
$2900.00

E-commerce market to reach $155.98 trillion by 2033, growing at 21.6% CAGR. Explore B2B, B2C, C2C trends, regional insights, and key players.

Nov 2026|189 pages
$2900.00
Author
Vijayashree Ugale

Vijayashree Ugale

Research Analyst

I am a Research Analyst specializing in Consumer Goods and Services, Retail, Consumer Staples, Consumer Discretionary, and Advanced Materials, delivering actionable market intelligence. My core expertise lies in comprehensive secondary research, market segmentation, and deep trend analysis to uncover rapidly evolving consumer and retail dynamics. By providing high-quality data and tailored strategic recommendations, I help organizations confidently support successful market entry, competitive positioning, and long-term expansion.

WHY IMD

Verified research

Analyst-reviewed data

Updated Oct 31, 2026

sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
Retail Analytics Industry Market Size, Trends & Forecast 2026-2035
View report
US Retail Colocation Market Size, Share & Forecast 2026-2035
View report
Australia Hair Care Market Size, Trends & Forecast 2026-2031
View report
E-commerce Market Size, Growth & Forecast 2026-2033
View report
CUSTOM INTELLIGENCE

Tailored for you

  • In-depth Analysis Tailored to Specified Regions or Segments
  • Company Profiles Customized to User Preferences
  • Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
avatar

Analyst at Providence Strategic Partners at Petaling Jaya

Jared Wan

I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

avatar

Internationalization Director

Santiago Mejia Molina

Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

avatar

Head of Product Management and Marketing

Olaf Gleibe

We are using your report, and it gave us valuable information."

avatar

Regional Director, Marketing and Business Development

Lina Lim

We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

avatar

VP of Sales

DIGGLE Representative

Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.
Get In Touch
Retail Business in Thailand Market CAGR, market size, market share

Executive Overview: Thailand's Retail Market at an Inflection Point

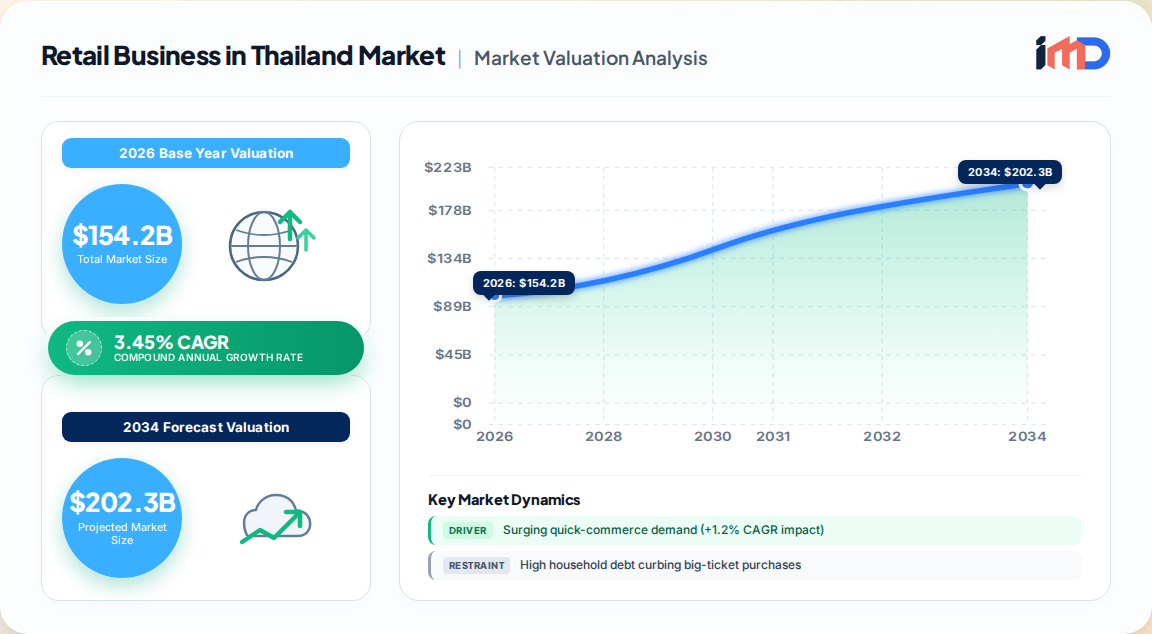
Thailand's retail sector represents one of Southeast Asia's most dynamic and structurally diverse consumer markets. Our proprietary bottom-up assessment values the market at USD 154.2 billion in 2026, with a projected expansion to USD 189.4 billion by 2032, reflecting a steady CAGR of 3.45% across the forecast window. This trajectory is not merely a function of macroeconomic tailwinds but of a profound reconfiguration of channel economics, consumer mobility, and payment infrastructure.

Retail Business in Thailand Market Market Size (In Billion)

200.0B
150.0B
100.0B
50.0B
0
149.1 B
2025
154.2 B
2026
159.5 B
2027
165.0 B
2028
170.7 B
2029
176.6 B
2030
182.7 B
2031
Main Logo
  • Food, beverage, and tobacco remains the anchor category, commanding 55.49% of total retail value in 2026.
  • Traditional mom-and-pop retail still holds a remarkable 43.32% share, underscoring the resilience of fragmented trade despite modern trade's aggressive expansion.
  • Convenience stores dominate format-level dynamics with a 40.98% share and the fastest forecast CAGR in physical formats at 9.65%.
  • E-commerce and alternative channels are forecast to grow at a blistering 15.9% CAGR, albeit from a smaller base, reshaping competitive intensity across all product categories.
Metric 2026 Value 2027 Value 2032 Value CAGR (2027–2032)
Market Size (USD Billion) 154.2 159.8 189.4 3.45%
Leading Product Segment Share Food, Bev. & Tobacco (55.49%) — — —
Leading Channel Share Traditional Mom & Pop (43.32%) — — —
Fastest-Growing Channel E-commerce (15.9% CAGR) — — —
Fastest-Growing Product Category Personal Care & Household (10.65% CAGR) — — —

This report synthesizes primary interviews with retailers, distributors, and payment providers, alongside first-party demand modeling, to deliver an actionable view of where growth will accrue and which structural bottlenecks require mitigation.

Key Market Drivers & Restraints

Growth Drivers

Surging quick-commerce demand in Bangkok and tier-2 cities contributes an estimated +1.2% to the market's CAGR over the short term. Rapid delivery windows of 30–60 minutes are converting top-up shopping missions into incremental baskets, provided fulfillment economics remain viable within tight delivery radii.

Tourism rebound lifting discretionary retail spend adds approximately +1.0% to CAGR. Thailand's tourism authority surveys indicate that 91.05% of international visitors shop during their trips, spanning apparel, souvenirs, Thai food products, cosmetics, and fragrances. This visitor base provides discretionary retailers with a demand pool independent of resident household budgets.

Modern trade expansion into rural provinces is the single largest structural driver, contributing +1.4% to CAGR over the medium term. Home improvement and lifestyle chains are racing to underserved regions, with one major retailer targeting 600+ openings across 2025–2027 and having already reached 1,248 stores across all 77 provinces by mid-2026.

Government 'Thailand 4.0' digital-payment incentives contribute +1.1% to CAGR. Thailand recorded 5.6 billion QR-payment transactions in 2025, up 34% year-on-year, while cross-border QR interoperability with Chinese payment apps launched in late 2025 via six Thai banks, broadening checkout accessibility for inbound tourists.

Restraints

  • High household debt curbs big-ticket purchases and imposes a -1.2% drag on CAGR, particularly in durable goods and home furnishings.
  • Rising minimum wages squeeze retail margins, contributing a -0.7% headwind, especially for labor-intensive formats such as hypermarkets and full-service department stores.
  • Counterfeit product infiltration, especially through online channels, erodes brand equity and consumer trust, disproportionately affecting FMCG and electronics categories.

Segmentation Analysis: Channels, Formats, and Product Mix

Thailand's retail market is best understood through three intersecting lenses: product type, retail channel, and store format. Each reveals distinct growth velocities and competitive dynamics.

Segment 2026 Share Forecast CAGR (2027–2032) Key Insight
Food, Beverage & Tobacco 55.49% — Anchor category; convenience-led demand
Personal Care & Household Care — 10.65% Fastest-growing product category
Traditional Mom & Pop 43.32% — Resilient but under modernization pressure
E-commerce & Others — 15.9% Fastest-growing channel; social commerce led
Convenience Stores 40.98% 9.65% Dominant format; urban and rural expansion

Grocery remains the cornerstone of retail value, with the segment valued at USD 95.76 billion in 2024. Hypermarkets and large supermarkets serve price-sensitive families, while convenience stores capture the fast-paced urban lifestyle through ready-to-eat meals and small-basket top-ups. E-grocery platforms are achieving 40% higher customer acquisition rates in urban areas compared to traditional marketing channels, validating the online-to-offline (O2O) integration strategy.

Personal care and household care is the standout growth category, driven by health and wellness prioritization, influencer-led social commerce, and the proliferation of private-label offerings. Retailers innovating in private labels report up to 10% incremental category growth, as price-conscious consumers trade down without abandoning quality expectations.

Convenience stores are expanding fastest among physical formats, benefiting from Thailand's dense urban geography, rising single-person households, and the integration of bill payment, parcel pickup, and food-to-go services that turn small-footprint outlets into community micro-hubs.

Competitive Landscape & Strategic Developments

The Thai retail market is characterized by medium concentration, with a mix of conglomerates, regional operators, and a vast informal trade base. Competition is increasingly defined by omnichannel capability, supply chain efficiency, and the ability to monetize consumer data.

Company Retail Footprint / Strategy
CP All PCL (7-Eleven Thailand) Largest convenience network; aggressive store densification and food-to-go innovation
Central Retail Corporation Diversified omnichannel portfolio spanning grocery, fashion, and hardlines
Lotus's (CP Axtra PCL) Hypermarket and supermarket format; value-led positioning
Big C Supercenter PCL Supercenter and mini-format expansion; rural penetration
CP Axtra PCL (Makro) Cash & carry leadership; B2B and SME supply chain
MR. D.I.Y. Holding (Thailand) 1,248 stores across 77 provinces; 600+ openings planned 2025–2027
Aeon Co. Ltd. Maxvalu supermarket network around Bangkok and greater Bangkok
Berli Jucker Public Co. Ltd. Big C network including 642 MiniBig C and 135 Pure drugstores
The Mall Group Premium mall and department store operator
Home Product Center PCL Home improvement and lifestyle retail

Recent strategic developments underscore the shift toward provincial expansion and digital integration. The 1,248-store milestone achieved by a leading home improvement retailer as of mid-2026, up from 1,027 a year earlier, exemplifies the 221-store annual net addition pace required to capture rural demand. Simultaneously, the integration of AI-driven demand forecasting is reducing stockouts by nearly 30% compared to traditional methods, providing a tangible margin advantage for early adopters.

Regional Outlook & Investment Attractiveness

Retail demand is unevenly distributed across Thailand's regions, shaped by urbanization, tourism flows, and income disparities. Bangkok and its metropolitan area account for an estimated 38% of national retail value, driven by high disposable incomes, tourist spending, and the densest concentration of modern trade formats.

Retail Business in Thailand Market Regional Market Share

Loading chart...
Main Logo
Region Estimated Share of Retail Value Growth Profile
Bangkok Metropolitan 38% Mature; quick-commerce and premiumization led
Central & Eastern 24% Industrial corridor; modern trade expansion
Northeastern (Isan) 16% Fast-growing; rural modern trade penetration
Northern 12% Tourism and agricultural income dependent
Southern 10% Tourism-heavy; seasonal discretionary spend

The Northeastern region presents the most compelling white-space opportunity, as modern trade chains accelerate store openings in underserved provinces. The region's large population and rising remittance inflows support grocery and household care demand, though logistical complexity and lower basket sizes necessitate tailored format strategies. Southern Thailand, while smaller in absolute value, offers high-margin discretionary retail opportunities tied to tourism seasonality, particularly in Phuket, Krabi, and Surat Thani.

Value Chain & Supply Chain Dynamics

The retail value chain in Thailand is undergoing a structural shift from linear distribution to networked fulfillment. Traditionally, goods flowed from manufacturers to distributors, wholesalers, and then to fragmented retail outlets. Today, leading retailers are integrating backward into sourcing and forward into last-mile delivery, blurring the boundaries between wholesale and retail.

  • Inbound logistics and procurement: Retailers are consolidating supplier bases and investing in regional distribution centers to serve provincial store networks. Cold-chain investment is critical for fresh food and convenience food categories.
  • Operations and fulfillment: Omnichannel fulfillment hubs are being deployed in urban stores, enabling click-and-collect and same-day delivery. AI-driven inventory management reduces waste and stockouts, with advanced systems cutting stockouts by nearly 30%.
  • Outbound logistics and last-mile: Bangkok's last-mile delivery challenges persist due to traffic congestion and fragmented address systems. Quick-commerce players are establishing micro-fulfillment centers to overcome these constraints.
  • Marketing and sales: Social commerce and influencer-led selling are reshaping beauty and fashion retail, while loyalty programs integrated with CRM and POS systems enable personalized offers and retention.

Strategic White-Space & Ansoff Matrix Implications

Retailers operating in Thailand face a clear strategic choice: defend traditional strengths or pivot aggressively toward high-growth adjacencies. Applying an Ansoff lens reveals actionable pathways.

Strategy Opportunity Risk Level
Market Penetration Deepen convenience store density in Bangkok and tier-2 cities; leverage quick commerce Low
Product Development Launch private-label lines in personal care and household care; expand ready-to-eat meal offerings Medium
Market Development Provincial expansion into Isan and Southern Thailand; cross-border QR payment acceptance for tourists Medium-High
Diversification Enter health and wellness retail; integrate financial services (BNPL, insurance) into retail ecosystems High

The most attractive near-term white space lies in personal care and household care, forecast to grow at a 10.65% CAGR, and in e-commerce and social commerce, growing at 15.9%. Retailers that combine physical store networks with digital discovery and payment interoperability will capture disproportionate share of these high-velocity segments.

Conclusion & Strategic Recommendations

Thailand's retail market offers a compelling blend of scale and steady growth, but success requires navigating structural tensions: household debt constrains big-ticket spending while tourism and digital payments unlock discretionary and convenience-driven demand. Our proprietary analysis suggests three imperatives for market participants:

  • Invest in provincial fulfillment infrastructure to capture the +1.4% CAGR contribution from rural modern trade expansion, prioritizing Isan and the Southern tourism corridors.
  • Integrate payment and loyalty ecosystems to monetize the 5.6 billion annual QR transactions and cross-border tourist spending, converting transaction data into personalized offers.
  • Accelerate private-label and ready-to-eat innovation to defend margins against wage inflation and capture the 10.65% CAGR growth in personal care and household care.

The market's 3.45% CAGR masks significant segment-level dispersion; the winners will be those who allocate capital toward the fastest-growing channels and formats while optimizing legacy store networks for profitability rather than sheer footprint.

Retail Business in Thailand Market Regional Market Share

Higher Coverage
Lower Coverage
No Coverage

Retail Business in Thailand Market REPORT HIGHLIGHTS

AspectsDetails
Study Period2020-2034
Base Year2026
Estimated Year2026
Forecast Period2026-2034
Historical Period2020-2025
Growth RateCAGR of 3.45% from 2020-2034
Segmentation
  • By Product Type

    • Food
    • Beverage and Tobacco Products
    • Apparel
    • Footwear and Accessories
    • Personal Care and Household Care

Table of Contents

  1. 1. Introduction
    • 1.1. Research Scope
    • 1.2. Market Segmentation
    • 1.3. Research Objective
    • 1.4. Definitions and Assumptions
  2. 2. Executive Summary
    • 2.1. Market Snapshot
  3. 3. Market Dynamics
    • 3.1. Market Drivers
      • 3.1.1. Surging quick-commerce demand (+1.2% CAGR impact)
      • 3.1.2. Tourism rebound lifting discretionary spend (+1.0% CAGR impact)
      • 3.1.3. Modern trade expansion into rural provinces (+1.4% CAGR impact)
      • 3.1.4. Government 'Thailand 4.0' digital-payment incentives (+1.1% CAGR impact)
    • 3.2. Market Trends
      • 3.2.1. Quick-commerce expansion in Bangkok and tier-2 cities
      • 3.2.2. Tourism rebound lifting discretionary retail spend
      • 3.2.3. Modern trade expansion into rural provinces
      • 3.2.4. Digital payment adoption and cross-border QR interoperability
      • 3.2.5. AI-led hyper-personalized retail analytics
    • 3.3. Market Restrains
      • 3.3.1. High household debt curbing big-ticket purchases
      • 3.3.2. Rising minimum wages squeezing retail margins
      • 3.3.3. Threat from counterfeit products
    • 3.4. Market Restraints
      • 3.4.1. High household debt curbing big-ticket purchases
      • 3.4.2. Rising minimum wages squeezing retail margins
Home and Garden
  • Others
  • By Retail Channel

    • Traditional Mom and Pop Retail
    • Modern Trade Retail
    • E-commerce and Others
  • By Format

    • Convenience Stores
    • Supermarkets
    • Hypermarkets
    • Department Stores
    • Specialty Stores
    • Others
  • By Geography
    • Bangkok Metropolitan

    • Central & Eastern

    • Northeastern

      • Isan
    • Northern

    • Southern

  • 3.4.3. Threat from counterfeit products
  • 3.5. Market Challenges
    • 3.5.1. Last-mile delivery complexities in Bangkok
    • 3.5.2. Counterfeit products eroding brand trust
    • 3.5.3. Margin pressure from wage inflation
  • 4. Market Factor Analysis
    • 4.1. Porters Five Forces
      • 4.1.1. Bargaining Power of Suppliers
      • 4.1.2. Bargaining Power of Buyers
      • 4.1.3. Threat of New Entrants
      • 4.1.4. Threat of Substitutes
      • 4.1.5. Competitive Rivalry
    • 4.2. PESTEL analysis
    • 4.3. BCG Analysis
      • 4.3.1. Stars (High Growth, High Market Share)
      • 4.3.2. Cash Cows (Low Growth, High Market Share)
      • 4.3.3. Question Mark (High Growth, Low Market Share)
      • 4.3.4. Dogs (Low Growth, Low Market Share)
    • 4.4. Ansoff Matrix Analysis
    • 4.5. Supply Chain Analysis
    • 4.6. Regulatory Landscape
    • 4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
    • 4.8. IMD Analyst Note
  • 5. Market Analysis, Insights and Forecast, 2020-2034
    • 5.1. Market Analysis, Insights and Forecast - by Product Type
      • 5.1.1. Food
      • 5.1.2. Beverage and Tobacco Products
      • 5.1.3. Apparel
      • 5.1.4. Footwear and Accessories
      • 5.1.5. Personal Care and Household Care
      • 5.1.6. Home and Garden
      • 5.1.7. Others
    • 5.2. Market Analysis, Insights and Forecast - by Retail Channel
      • 5.2.1. Traditional Mom and Pop Retail
      • 5.2.2. Modern Trade Retail
      • 5.2.3. E-commerce and Others
    • 5.3. Market Analysis, Insights and Forecast - by Format
      • 5.3.1. Convenience Stores
      • 5.3.2. Supermarkets
      • 5.3.3. Hypermarkets
      • 5.3.4. Department Stores
      • 5.3.5. Specialty Stores
      • 5.3.6. Others
    • 5.4. Market Analysis, Insights and Forecast - by Region
      • 5.4.1. Bangkok Metropolitan
      • 5.4.2. Central & Eastern
      • 5.4.3. Northeastern
      • 5.4.4. Northern
      • 5.4.5. Southern
  • 6. Bangkok Metropolitan Market Analysis, Insights and Forecast, 2020-2034
    • 6.1. Market Analysis, Insights and Forecast - by Product Type
      • 6.1.1. Food
      • 6.1.2. Beverage and Tobacco Products
      • 6.1.3. Apparel
      • 6.1.4. Footwear and Accessories
      • 6.1.5. Personal Care and Household Care
      • 6.1.6. Home and Garden
      • 6.1.7. Others
    • 6.2. Market Analysis, Insights and Forecast - by Retail Channel
      • 6.2.1. Traditional Mom and Pop Retail
      • 6.2.2. Modern Trade Retail
      • 6.2.3. E-commerce and Others
    • 6.3. Market Analysis, Insights and Forecast - by Format
      • 6.3.1. Convenience Stores
      • 6.3.2. Supermarkets
      • 6.3.3. Hypermarkets
      • 6.3.4. Department Stores
      • 6.3.5. Specialty Stores
      • 6.3.6. Others
  • 7. Central & Eastern Market Analysis, Insights and Forecast, 2020-2034
    • 7.1. Market Analysis, Insights and Forecast - by Product Type
      • 7.1.1. Food
      • 7.1.2. Beverage and Tobacco Products
      • 7.1.3. Apparel
      • 7.1.4. Footwear and Accessories
      • 7.1.5. Personal Care and Household Care
      • 7.1.6. Home and Garden
      • 7.1.7. Others
    • 7.2. Market Analysis, Insights and Forecast - by Retail Channel
      • 7.2.1. Traditional Mom and Pop Retail
      • 7.2.2. Modern Trade Retail
      • 7.2.3. E-commerce and Others
    • 7.3. Market Analysis, Insights and Forecast - by Format
      • 7.3.1. Convenience Stores
      • 7.3.2. Supermarkets
      • 7.3.3. Hypermarkets
      • 7.3.4. Department Stores
      • 7.3.5. Specialty Stores
      • 7.3.6. Others
  • 8. Northeastern Market Analysis, Insights and Forecast, 2020-2034
    • 8.1. Market Analysis, Insights and Forecast - by Product Type
      • 8.1.1. Food
      • 8.1.2. Beverage and Tobacco Products
      • 8.1.3. Apparel
      • 8.1.4. Footwear and Accessories
      • 8.1.5. Personal Care and Household Care
      • 8.1.6. Home and Garden
      • 8.1.7. Others
    • 8.2. Market Analysis, Insights and Forecast - by Retail Channel
      • 8.2.1. Traditional Mom and Pop Retail
      • 8.2.2. Modern Trade Retail
      • 8.2.3. E-commerce and Others
    • 8.3. Market Analysis, Insights and Forecast - by Format
      • 8.3.1. Convenience Stores
      • 8.3.2. Supermarkets
      • 8.3.3. Hypermarkets
      • 8.3.4. Department Stores
      • 8.3.5. Specialty Stores
      • 8.3.6. Others
  • 9. Northern Market Analysis, Insights and Forecast, 2020-2034
    • 9.1. Market Analysis, Insights and Forecast - by Product Type
      • 9.1.1. Food
      • 9.1.2. Beverage and Tobacco Products
      • 9.1.3. Apparel
      • 9.1.4. Footwear and Accessories
      • 9.1.5. Personal Care and Household Care
      • 9.1.6. Home and Garden
      • 9.1.7. Others
    • 9.2. Market Analysis, Insights and Forecast - by Retail Channel
      • 9.2.1. Traditional Mom and Pop Retail
      • 9.2.2. Modern Trade Retail
      • 9.2.3. E-commerce and Others
    • 9.3. Market Analysis, Insights and Forecast - by Format
      • 9.3.1. Convenience Stores
      • 9.3.2. Supermarkets
      • 9.3.3. Hypermarkets
      • 9.3.4. Department Stores
      • 9.3.5. Specialty Stores
      • 9.3.6. Others
  • 10. Southern Market Analysis, Insights and Forecast, 2020-2034
    • 10.1. Market Analysis, Insights and Forecast - by Product Type
      • 10.1.1. Food
      • 10.1.2. Beverage and Tobacco Products
      • 10.1.3. Apparel
      • 10.1.4. Footwear and Accessories
      • 10.1.5. Personal Care and Household Care
      • 10.1.6. Home and Garden
      • 10.1.7. Others
    • 10.2. Market Analysis, Insights and Forecast - by Retail Channel
      • 10.2.1. Traditional Mom and Pop Retail
      • 10.2.2. Modern Trade Retail
      • 10.2.3. E-commerce and Others
    • 10.3. Market Analysis, Insights and Forecast - by Format
      • 10.3.1. Convenience Stores
      • 10.3.2. Supermarkets
      • 10.3.3. Hypermarkets
      • 10.3.4. Department Stores
      • 10.3.5. Specialty Stores
      • 10.3.6. Others
  • 11. Competitive Analysis
    • 11.1. Company Profiles
      • 11.1.1. CP All PCL (7-Eleven Thailand)
        • 11.1.1.1. Company Overview
        • 11.1.1.2. Products
        • 11.1.1.3. Company Financials
        • 11.1.1.4. SWOT Analysis
      • 11.1.2. Central Retail Corporation
        • 11.1.2.1. Company Overview
        • 11.1.2.2. Products
        • 11.1.2.3. Company Financials
        • 11.1.2.4. SWOT Analysis
      • 11.1.3. Lotus's (CP Axtra PCL)
        • 11.1.3.1. Company Overview
        • 11.1.3.2. Products
        • 11.1.3.3. Company Financials
        • 11.1.3.4. SWOT Analysis
      • 11.1.4. Big C Supercenter PCL
        • 11.1.4.1. Company Overview
        • 11.1.4.2. Products
        • 11.1.4.3. Company Financials
        • 11.1.4.4. SWOT Analysis
      • 11.1.5. CP Axtra PCL (Makro/Cash & Carry)
        • 11.1.5.1. Company Overview
        • 11.1.5.2. Products
        • 11.1.5.3. Company Financials
        • 11.1.5.4. SWOT Analysis
      • 11.1.6. MR. D.I.Y. Holding (Thailand)
        • 11.1.6.1. Company Overview
        • 11.1.6.2. Products
        • 11.1.6.3. Company Financials
        • 11.1.6.4. SWOT Analysis
      • 11.1.7. Aeon Co. Ltd.
        • 11.1.7.1. Company Overview
        • 11.1.7.2. Products
        • 11.1.7.3. Company Financials
        • 11.1.7.4. SWOT Analysis
      • 11.1.8. Berli Jucker Public Co. Ltd.
        • 11.1.8.1. Company Overview
        • 11.1.8.2. Products
        • 11.1.8.3. Company Financials
        • 11.1.8.4. SWOT Analysis
      • 11.1.9. The Mall Group
        • 11.1.9.1. Company Overview
        • 11.1.9.2. Products
        • 11.1.9.3. Company Financials
        • 11.1.9.4. SWOT Analysis
      • 11.1.10. Home Product Center PCL
        • 11.1.10.1. Company Overview
        • 11.1.10.2. Products
        • 11.1.10.3. Company Financials
        • 11.1.10.4. SWOT Analysis
      • 11.1.11. Foodland Supermarket Co. Ltd.
        • 11.1.11.1. Company Overview
        • 11.1.11.2. Products
        • 11.1.11.3. Company Financials
        • 11.1.11.4. SWOT Analysis
      • 11.1.12. Isetan Mitsukoshi Holdings Ltd.
        • 11.1.12.1. Company Overview
        • 11.1.12.2. Products
        • 11.1.12.3. Company Financials
        • 11.1.12.4. SWOT Analysis
      • 11.1.13. King Power Group
        • 11.1.13.1. Company Overview
        • 11.1.13.2. Products
        • 11.1.13.3. Company Financials
        • 11.1.13.4. SWOT Analysis
      • 11.1.14. Rimping Supermarket
        • 11.1.14.1. Company Overview
        • 11.1.14.2. Products
        • 11.1.14.3. Company Financials
        • 11.1.14.4. SWOT Analysis
      • 11.1.15. SPAR International
        • 11.1.15.1. Company Overview
        • 11.1.15.2. Products
        • 11.1.15.3. Company Financials
        • 11.1.15.4. SWOT Analysis
      • 11.1.16. FN Factory Outlet Public Co Ltd
        • 11.1.16.1. Company Overview
        • 11.1.16.2. Products
        • 11.1.16.3. Company Financials
        • 11.1.16.4. SWOT Analysis
      • 11.1.17. DoHome Public Co Ltd
        • 11.1.17.1. Company Overview
        • 11.1.17.2. Products
        • 11.1.17.3. Company Financials
        • 11.1.17.4. SWOT Analysis
      • 11.1.18. Jaspal Co. Ltd.
        • 11.1.18.1. Company Overview
        • 11.1.18.2. Products
        • 11.1.18.3. Company Financials
        • 11.1.18.4. SWOT Analysis
      • 11.1.19. Walgreens Boots Alliance Inc.
        • 11.1.19.1. Company Overview
        • 11.1.19.2. Products
        • 11.1.19.3. Company Financials
        • 11.1.19.4. SWOT Analysis
      • 11.1.20. AS Watson Group
        • 11.1.20.1. Company Overview
        • 11.1.20.2. Products
        • 11.1.20.3. Company Financials
        • 11.1.20.4. SWOT Analysis
    • 11.2. Market Entropy
      • 11.2.1. Company's Key Areas Served
      • 11.2.2. Recent Developments
    • 11.3. Company Market Share Analysis, 2026
      • 11.3.1. Top 5 Companies Market Share Analysis
      • 11.3.2. Top 3 Companies Market Share Analysis
    • 11.4. List of Potential Customers
  • List of Figures

    1. Figure 1: Global Retail Business in Thailand Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
    2. Figure 2: Bangkok Metropolitan Retail Business in Thailand Market Revenue (Billion), by Product Type 2026 & 2034
    3. Figure 3: Bangkok Metropolitan Retail Business in Thailand Market Revenue Share (%), by Product Type 2026 & 2034
    4. Figure 4: Bangkok Metropolitan Retail Business in Thailand Market Revenue (Billion), by Retail Channel 2026 & 2034
    5. Figure 5: Bangkok Metropolitan Retail Business in Thailand Market Revenue Share (%), by Retail Channel 2026 & 2034
    6. Figure 6: Bangkok Metropolitan Retail Business in Thailand Market Revenue (Billion), by Format 2026 & 2034
    7. Figure 7: Bangkok Metropolitan Retail Business in Thailand Market Revenue Share (%), by Format 2026 & 2034
    8. Figure 8: Bangkok Metropolitan Retail Business in Thailand Market Revenue (Billion), by Country 2026 & 2034
    9. Figure 9: Bangkok Metropolitan Retail Business in Thailand Market Revenue Share (%), by Country 2026 & 2034
    10. Figure 10: Central & Eastern Retail Business in Thailand Market Revenue (Billion), by Product Type 2026 & 2034
    11. Figure 11: Central & Eastern Retail Business in Thailand Market Revenue Share (%), by Product Type 2026 & 2034
    12. Figure 12: Central & Eastern Retail Business in Thailand Market Revenue (Billion), by Retail Channel 2026 & 2034
    13. Figure 13: Central & Eastern Retail Business in Thailand Market Revenue Share (%), by Retail Channel 2026 & 2034
    14. Figure 14: Central & Eastern Retail Business in Thailand Market Revenue (Billion), by Format 2026 & 2034
    15. Figure 15: Central & Eastern Retail Business in Thailand Market Revenue Share (%), by Format 2026 & 2034
    16. Figure 16: Central & Eastern Retail Business in Thailand Market Revenue (Billion), by Country 2026 & 2034
    17. Figure 17: Central & Eastern Retail Business in Thailand Market Revenue Share (%), by Country 2026 & 2034
    18. Figure 18: Northeastern Retail Business in Thailand Market Revenue (Billion), by Product Type 2026 & 2034
    19. Figure 19: Northeastern Retail Business in Thailand Market Revenue Share (%), by Product Type 2026 & 2034
    20. Figure 20: Northeastern Retail Business in Thailand Market Revenue (Billion), by Retail Channel 2026 & 2034
    21. Figure 21: Northeastern Retail Business in Thailand Market Revenue Share (%), by Retail Channel 2026 & 2034
    22. Figure 22: Northeastern Retail Business in Thailand Market Revenue (Billion), by Format 2026 & 2034
    23. Figure 23: Northeastern Retail Business in Thailand Market Revenue Share (%), by Format 2026 & 2034
    24. Figure 24: Northeastern Retail Business in Thailand Market Revenue (Billion), by Country 2026 & 2034
    25. Figure 25: Northeastern Retail Business in Thailand Market Revenue Share (%), by Country 2026 & 2034
    26. Figure 26: Northern Retail Business in Thailand Market Revenue (Billion), by Product Type 2026 & 2034
    27. Figure 27: Northern Retail Business in Thailand Market Revenue Share (%), by Product Type 2026 & 2034
    28. Figure 28: Northern Retail Business in Thailand Market Revenue (Billion), by Retail Channel 2026 & 2034
    29. Figure 29: Northern Retail Business in Thailand Market Revenue Share (%), by Retail Channel 2026 & 2034
    30. Figure 30: Northern Retail Business in Thailand Market Revenue (Billion), by Format 2026 & 2034
    31. Figure 31: Northern Retail Business in Thailand Market Revenue Share (%), by Format 2026 & 2034
    32. Figure 32: Northern Retail Business in Thailand Market Revenue (Billion), by Country 2026 & 2034
    33. Figure 33: Northern Retail Business in Thailand Market Revenue Share (%), by Country 2026 & 2034
    34. Figure 34: Southern Retail Business in Thailand Market Revenue (Billion), by Product Type 2026 & 2034
    35. Figure 35: Southern Retail Business in Thailand Market Revenue Share (%), by Product Type 2026 & 2034
    36. Figure 36: Southern Retail Business in Thailand Market Revenue (Billion), by Retail Channel 2026 & 2034
    37. Figure 37: Southern Retail Business in Thailand Market Revenue Share (%), by Retail Channel 2026 & 2034
    38. Figure 38: Southern Retail Business in Thailand Market Revenue (Billion), by Format 2026 & 2034
    39. Figure 39: Southern Retail Business in Thailand Market Revenue Share (%), by Format 2026 & 2034
    40. Figure 40: Southern Retail Business in Thailand Market Revenue (Billion), by Country 2026 & 2034
    41. Figure 41: Southern Retail Business in Thailand Market Revenue Share (%), by Country 2026 & 2034

    List of Tables

    1. Table 1: Global Retail Business in Thailand Market Revenue Billion Forecast, by Product Type 2020 & 2034
    2. Table 2: Global Retail Business in Thailand Market Revenue Billion Forecast, by Retail Channel 2020 & 2034
    3. Table 3: Global Retail Business in Thailand Market Revenue Billion Forecast, by Format 2020 & 2034
    4. Table 4: Global Retail Business in Thailand Market Revenue Billion Forecast, by Region 2020 & 2034
    5. Table 5: Bangkok Metropolitan Retail Business in Thailand Market Revenue Billion Forecast, by Product Type 2020 & 2034
    6. Table 6: Bangkok Metropolitan Retail Business in Thailand Market Revenue Billion Forecast, by Retail Channel 2020 & 2034
    7. Table 7: Bangkok Metropolitan Retail Business in Thailand Market Revenue Billion Forecast, by Format 2020 & 2034
    8. Table 8: Bangkok Metropolitan Retail Business in Thailand Market Revenue Billion Forecast, by Country 2020 & 2034
    9. Table 9: Central & Eastern Retail Business in Thailand Market Revenue Billion Forecast, by Product Type 2020 & 2034
    10. Table 10: Central & Eastern Retail Business in Thailand Market Revenue Billion Forecast, by Retail Channel 2020 & 2034
    11. Table 11: Central & Eastern Retail Business in Thailand Market Revenue Billion Forecast, by Format 2020 & 2034
    12. Table 12: Central & Eastern Retail Business in Thailand Market Revenue Billion Forecast, by Country 2020 & 2034
    13. Table 13: Northeastern Retail Business in Thailand Market Revenue Billion Forecast, by Product Type 2020 & 2034
    14. Table 14: Northeastern Retail Business in Thailand Market Revenue Billion Forecast, by Retail Channel 2020 & 2034
    15. Table 15: Northeastern Retail Business in Thailand Market Revenue Billion Forecast, by Format 2020 & 2034
    16. Table 16: Northeastern Retail Business in Thailand Market Revenue Billion Forecast, by Country 2020 & 2034
    17. Table 17: Isan Retail Business in Thailand Market Revenue (Billion) Forecast, by Application 2020 & 2034
    18. Table 18: Northern Retail Business in Thailand Market Revenue Billion Forecast, by Product Type 2020 & 2034
    19. Table 19: Northern Retail Business in Thailand Market Revenue Billion Forecast, by Retail Channel 2020 & 2034
    20. Table 20: Northern Retail Business in Thailand Market Revenue Billion Forecast, by Format 2020 & 2034
    21. Table 21: Northern Retail Business in Thailand Market Revenue Billion Forecast, by Country 2020 & 2034
    22. Table 22: Southern Retail Business in Thailand Market Revenue Billion Forecast, by Product Type 2020 & 2034
    23. Table 23: Southern Retail Business in Thailand Market Revenue Billion Forecast, by Retail Channel 2020 & 2034
    24. Table 24: Southern Retail Business in Thailand Market Revenue Billion Forecast, by Format 2020 & 2034
    25. Table 25: Southern Retail Business in Thailand Market Revenue Billion Forecast, by Country 2020 & 2034

    Frequently Asked Questions

    1What is the size of the retail business in Thailand market?

    The Thailand retail market was valued at USD 154.2 billion in 2026 and is projected to reach USD 189.4 billion by 2032, growing at a CAGR of 3.45% during the forecast period.

    2Which retail channel dominates the Thailand market?

    Traditional mom-and-pop retail held the largest share at 43.32% in 2026, though e-commerce and other digital channels are forecast to grow fastest at a 15.9% CAGR through 2032.

    3What is driving growth in Thailand's retail sector?

    Key drivers include modern trade expansion into rural provinces (+1.4% CAGR impact), quick-commerce demand in Bangkok and tier-2 cities (+1.2%), and a tourism rebound where 91.05% of international visitors shop during their trips.

    4Which product category is growing fastest in Thailand retail?

    Personal care and household care is forecast to grow at a 10.65% CAGR from 2027 to 2032, outpacing the broader market, driven by health and wellness trends and private-label innovation.

    5Who are the leading retailers in Thailand?

    Major players include CP All PCL (7-Eleven Thailand), Central Retail Corporation, Lotus's (CP Axtra PCL), Big C Supercenter PCL, CP Axtra PCL (Makro), and MR. D.I.Y. Holding (Thailand).

    Methodology

    Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.

    Primary Research

    • 70–80% of total research effort is allocated to primary research, encompassing structured interviews, retail audits, and store-level basket analysis across Thailand's five major regions.
    • We conduct in-depth interviews with 4–5 distinct company types: modern trade retail chains, traditional trade distributors, e-commerce and quick-commerce platforms, payment service providers, and shopping mall operators.
    • Stakeholder job titles interviewed include: Chief Retail Officer, Head of Omnichannel Strategy, Supply Chain Director, and Category Management Head.
    • Primary research is complemented by on-the-ground store audits in Bangkok, Chiang Mai, Khon Kaen, and Phuket to validate shelf-share and pricing data.

    Key Stakeholders Interviewed

    Main Logo
    Key Stakeholders Interviewed
    Stakeholder RoleInterview Share (%)
    Chief Retail Officer30%
    Head of Omnichannel Strategy25%
    Supply Chain Director25%
    Category Management Head20%

    Industry Ecosystem Breakdown

    Main Logo
    Industry Ecosystem Breakdown
    Company TypeRepresentation (%)
    Modern Trade Retail Chains30%
    Traditional Trade Distributors20%
    E-commerce & Quick-Commerce Platforms25%
    Payment Service Providers15%
    Shopping Mall Operators10%

    Secondary Research & Industry Benchmarking

    • 20–30% of research effort draws on secondary sources, including official statistics from the National Statistical Office of Thailand, Bank of Thailand, and Tourism Authority of Thailand.
    • We benchmark against recognized non-profit trade associations such as the Thai Retailers Association and the Federation of Thai Industries, alongside multilateral data from the World Bank and OECD.
    • Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook are used to validate company-level revenue and store count data.

    Demand Modeling & Market Estimation

    • We employ simultaneous top-down and bottom-up methodologies, validated through multi-level data triangulation.
    • Bottom-up calculation aggregates retail sales across 4 specific quantitative metrics: (1) store count by format and region, (2) average basket size per format, (3) footfall conversion rates, and (4) e-commerce GMV per platform.
    • Top-down modeling anchors national retail spend to household consumption expenditure data from the National Economic and Social Development Council (NESDC), adjusted for tourism spending.

    Data Accuracy & Quality Check

    • Every report is updated to the date of purchase, ensuring the latest store openings, regulatory changes, and market events are reflected.
    • We guarantee an estimated data accuracy level of 85–90%, achieved through cross-validation of primary interview data against official statistics and financial disclosures.
    • All market size figures are presented as proprietary first-party estimates, derived from our estimation framework combining actuals with forward projections.
