About Insight Market Data

Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.

Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

report thumbnailPolyethylene Terephthalate (PET) Resin Report
Chemicals & Materials / MARKET REPORT

Polyethylene Terephthalate (PET) Resin Report | Insight Market Data

Polyethylene Terephthalate (PET) Resin Report by PET Type (Transparent & Non-Transparent PET, Recycled PET), by Application (Packaging, Films & Sheets, Consumer Goods, Others), by Packaging Application (Bottled Water, Carbonated Soft Beverages, Juices, Alcoholic Beverages, Thermoforming Trays, Food Packaging, Non-Food Packaging, Others), by End User (Food & Beverages, Automotive, Electronics & Electrical, Construction, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, South Korea, India, Australia), by Latin America (Brazil, Argentina), by Middle East & Africa (South Africa, GCC) Forecast 2026-2034

© Nov 4, 2026|Base Year: 2025|196 Pages
Khageshwar Rongkali

Khageshwar Rongkali

Senior Analyst

Main Logo

PET Resin Market Size, Share & Forecast to 2033


/
/
Home
Industries
Chemicals & Materials

Business Address

Head Office

Ansec House 3 rd floor Tank Road, Yerwada, Pune, Maharashtra 411014

Contact Information

Craig Francis

Business Development Head

+12315155523

[email protected]

Secure Payment Partners

payment image
RetailLogisticsPackagingAutomotiveHealthcareAgricultureEnergy & PowerFood & BeverageAerospace & DefenseChemicals & MaterialsHospitality and TourismConsumer Goods and ServicesAnimal Nutrition & WellnessReal Estate and ConstructionHome and Property ImprovementTechnology, Media and TelecomManufacturing Products and ServicesFinancial Services and Investment Intelligence

© 2026 PRDUA Research & Media Private Limited, All rights reserved

Privacy Policy•Terms and Conditions•FAQ
Independent Intelligence for decisions that move markets
+12315155523[email protected]
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Main Logo
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Talk to an analyst
Polyethylene Terephthalate (PET) Resin Report CAGR, market size, market share

Executive Overview

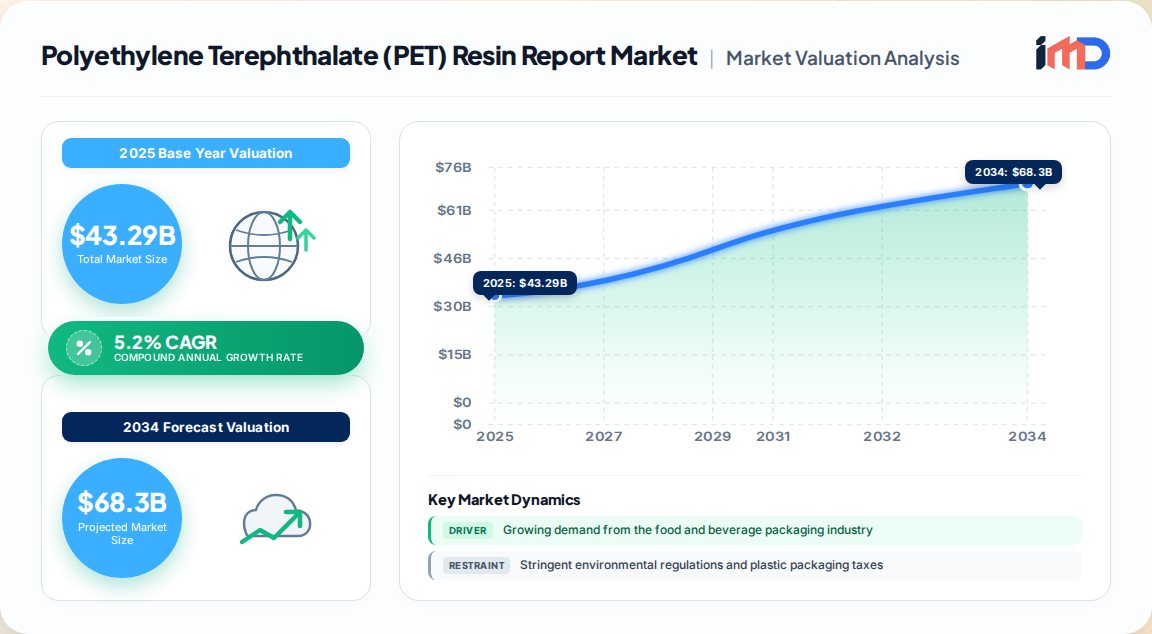
The global Polyethylene Terephthalate (PET) Resin market represents a cornerstone of the modern packaging and synthetic fiber economy. Our proprietary primary research estimates the market at USD 43.29 Billion in 2025, with a projected trajectory to USD 64.94 Billion by 2033, advancing at a 5.2% CAGR during the forecast period. This growth is underpinned by sustained demand from the food and beverage sector, the accelerating shift toward lightweight and recyclable packaging formats, and the rapid industrialization of emerging economies across Asia-Pacific.

Polyethylene Terephthalate (PET) Resin Report Market Size (In Billion)

75.0B
60.0B
45.0B
30.0B
15.0B
0
43.29 B
2025
45.54 B
2026
47.91 B
2027
50.40 B
2028
53.02 B
2029
55.78 B
2030
58.68 B
2031
Main Logo

North America currently leads in per-capita consumption and technological integration for specialty grades, while Asia-Pacific commands the largest volume share, projected at 38% of global sales by 2025, driven by China and India. The market is undergoing a structural transformation defined by sustainability mandates, with recycled PET (rPET) demand expanding faster than virgin resin. This dichotomy between regulatory pressure and capacity constraints is the single most important dynamic shaping the competitive landscape through 2033.

Key Market Drivers & Restraints

The PET resin market is propelled by several structural demand drivers and simultaneously constrained by regulatory and supply-side challenges.

Drivers:

  • Packaging Industry Expansion: PET's superior barrier properties, low weight, and cost-efficiency compared to glass, paper, and aluminum make it the material of choice for beverages, personal care, and food products. The global transition from glass to PET bottles in the beverage industry is a primary volume driver.
  • Recyclability and Circular Economy Push: PET is the most recycled plastic globally, with established collection and processing infrastructure. Brand owners and regulators are increasingly aligned on closed-loop systems, driving demand for food-grade rPET.
  • Emerging Market Urbanization: Rising disposable incomes and the growth of organized retail in Asia-Pacific, Latin America, and the Middle East are expanding the packaged consumer goods market, directly fueling PET demand.
  • Automotive Lightweighting: PET resins are increasingly used in automotive components and films, aiding weight reduction and improving fuel efficiency, which is particularly relevant in the electric vehicle supply chain.

Restraints:

  • Stringent Environmental Regulations: Governments worldwide are implementing extended producer responsibility (EPR) schemes, recycled content mandates, and taxes on virgin plastic. The UK's plastic packaging tax, for example, charges GBP 228.82 per tonne on packaging with less than 30% recycled content, adding a cost layer to virgin resin adoption.
  • Feedstock Price Volatility: The price of PET resin is closely tied to paraxylene and monoethylene glycol (MEG) markets, which are subject to crude oil price fluctuations and geopolitical supply disruptions.
  • Recycling Capacity Constraints: While demand for rPET is surging, the supply of high-quality recycled flake is limited by collection infrastructure gaps and contamination issues. Plant closures, such as the Alpek facility in Reading, Pennsylvania, in 2026, highlight the fragility of rPET supply chains in developed markets.

Segmentation Analysis

The PET resin market is segmented by type, application, packaging application, and end-user industry, each exhibiting distinct growth dynamics.

By PET Type:

  • Transparent & Non-Transparent PET: The dominant segment, accounting for the majority of virgin resin demand. Transparent PET is preferred for beverage bottles and food containers where product visibility is crucial. Non-transparent variants are used in industrial and textile applications.
  • Recycled PET (rPET): The fastest-growing segment, driven by regulatory mandates and corporate sustainability targets. Major brand owners, including Otsuka Pharmaceutical in Japan, are rolling out 100% rPET bottles, signaling a definitive shift in procurement strategies.

By Application:

  • Packaging: The largest application segment, holding approximately 64% of sales in 2026. This encompasses bottles, containers, and rigid packaging for food and beverages, pharmaceuticals, and consumer goods.
  • Films & Sheets: Accounting for roughly 17% of application sales, used in thermoforming, flexible packaging, and industrial films.
  • Consumer Goods: About 12% of sales, including household products, personal care, and electronics casings.
  • Others: The remaining share includes automotive decoration, building and construction, and electrical/electronic components.

By Packaging Application:

  • Bottled Water: A high-volume, low-margin segment that is increasingly shifting toward rPET.
  • Carbonated Soft Beverages (CSDs): Require high-strength PET grades; a mature but stable segment.
  • Juices, Alcoholic Beverages: Growing segments, particularly in emerging markets.
  • Thermoforming Trays, Food Packaging: Driven by convenience food trends.
  • Non-Food Packaging: Industrial and chemical packaging.

By End User:

  • Food & Beverages: The dominant end-use sector, representing 57% of sales in 2026. The segment's growth is tied to global population growth, urbanization, and the demand for packaged and processed foods.
  • Automotive: The second-largest end user at 17%, driven by lightweighting trends and the use of PET in interior components and films.
  • Electronics & Electrical: Accounting for 15%, PET is used in connectors, housings, and films for displays.
  • Others: Construction, healthcare, and textiles.

Regional Outlook

The PET resin market exhibits distinct regional dynamics, with Asia-Pacific as the growth engine and North America and Europe as mature, regulation-driven markets.

Polyethylene Terephthalate (PET) Resin Report Regional Market Share

Loading chart...
Main Logo
Region Market Position Key Characteristics
Asia-Pacific Largest volume share (38% by 2025); fastest CAGR (3.5% in South Korea, 3.2% in China) Driven by packaged food consumption, urbanization, and expanding manufacturing. China and India are key growth markets.
North America Mature market with high per-capita consumption Focus on rPET integration, advanced recycling technologies. The US market is projected to grow steadily, supported by automotive and healthcare demand.
Europe Regulation-heavy market Stringent EPR and recycled content mandates are driving rPET demand. The EU is a leader in circular economy legislation.
Latin America Emerging market Growing demand from the food and beverage sector; Brazil and Mexico are key markets.
Middle East & Africa Emerging market Increasing investment in packaging infrastructure; South Africa and the GCC are prominent.

Competitive Landscape

The PET resin market is moderately consolidated, with the top five players holding approximately 33% of global share. Competition is intensifying as producers invest in integrated feedstock, recycling capacity, and bio-based technologies.

Key Players:

  • Indorama Ventures: A global leader in PET and recycling, operating more than 20 recycling facilities across 11 countries. The company has recycled over 150 billion post-consumer PET bottles since 2011.
  • Alpek: A major North American producer, with a PET reference margin of USD 145 per ton in its 2026 base case. Despite closing its Reading recycling plant, Alpek continues to invest in integrated sites.
  • Tongkun Group, Xin Feng Ming Group, Zhejiang Hengyi: Leading Chinese producers with significant capacity and vertical integration.
  • Reliance Industries: A dominant player in India with integrated polyester and PET operations.
  • FENC, SABIC, Lotte Chemical, Toray, KoKsan, Sibur (Polief): Regional leaders with diversified portfolios.
  • Alpla: A major recycler with 300,000 tonnes of installed rPET capacity and a 2030 target of 700,000 tonnes.

Strategic Developments:

  • Recycled Content Mandates: South Korea requires at least 10% recycled PET in bottles from January 2026 for large beverage bottlers, with a 30% target by 2030. This is driving investments in recycling infrastructure.
  • Bio-based PET: Companies are investing in bio-MEG from sugarcane and corn waste, with the bio-based PET market projected to grow at a 12.8% CAGR to reach USD 8.8 Billion by 2033. This represents a significant white-space opportunity for early movers.
  • Capacity Rationalization: High-cost, non-integrated producers are under pressure, leading to plant closures and consolidation. Alpek's Reading closure is a case in point, with capacity being shifted to its integrated Richmond, Indiana site.

Value Chain and Supply Chain Dynamics

The PET resin value chain is characterized by tight integration between feedstock producers and resin manufacturers. Key inputs include purified terephthalic acid (PTA) and monoethylene glycol (MEG), both of which are derived from petrochemicals.

  • Feedstock Supply: The availability and pricing of PTA and MEG are critical. Integrated producers with captive feedstock have a significant cost advantage. For instance, Indorama Ventures' shale-to-PET integration in the Americas has widened its cost advantage.
  • Recycling Infrastructure: The supply of recycled flake is a bottleneck. Collection rates vary widely by region, and contamination remains a challenge. Investment in advanced sorting and chemical recycling is essential to meet recycled content targets.
  • Logistics: PET resin is typically transported as pellets or flakes. The shift toward regional production and local recycling aims to reduce transportation costs and carbon footprints.

Import/Export & Supplier Dynamics

The global PET resin trade is shaped by regional imbalances between production and consumption. Asia-Pacific is a net exporter of virgin PET, while North America and Europe are net importers of certain grades.

  • China: The largest producer and exporter of PET resin, with a growing focus on high-value specialty grades.
  • Europe: Imports significant volumes to meet packaging demand, but is increasingly looking to domestic rPET production to comply with regulations.
  • North America: The US is a major producer, with exports to Latin America and Asia. The closure of recycling facilities may lead to increased imports of rPET.
  • Emerging Trade Flows: The bio-based PET segment is creating new trade patterns, with Brazil and Thailand emerging as key exporters of bio-based feedstock.

Strategic White-Space Analysis

The highest-growth opportunities in the PET resin market lie in the intersection of sustainability, performance, and cost.

  • Food-Grade rPET: The supply gap for food-grade rPET is the most significant white space. Producers who invest early in advanced recycling technologies (e.g., chemical recycling) are well-positioned to capture premiums.
  • Bio-based PET: The bio-based PET market, valued at USD 3.4 Billion in 2025, offers an alternative to fossil-fuel-based PET. Bottles represent 50% of the application share, indicating a clear target for sustainable packaging.
  • Lightweighting and Performance Grades: Innovations in resin formulation to reduce bottle weight while maintaining strength can provide cost savings and sustainability benefits.

Polyethylene Terephthalate (PET) Resin Report Regional Market Share

Higher Coverage
Lower Coverage
No Coverage

Polyethylene Terephthalate (PET) Resin Report REPORT HIGHLIGHTS

AspectsDetails
Study Period2020-2034
Base Year2025
Estimated Year2026
Forecast Period2026-2034
Historical Period2020-2025
Growth RateCAGR of 5.2% from 2020-2034
Segmentation
  • By PET Type

    • Transparent & Non-Transparent PET
    • Recycled PET
  • By Application

    • Packaging

Table of Contents

  1. 1. Introduction
    • 1.1. Research Scope
    • 1.2. Market Segmentation
    • 1.3. Research Objective
    • 1.4. Definitions and Assumptions
  2. 2. Executive Summary
    • 2.1. Market Snapshot
  3. 3. Market Dynamics
    • 3.1. Market Drivers
      • 3.1.1. Growing demand from the food and beverage packaging industry
      • 3.1.2. Superior properties of PET for lightweight, recyclable packaging
      • 3.1.3. Urbanization and rising disposable incomes in emerging markets
      • 3.1.4. Technological advancements in resin manufacturing and recycling
    • 3.2. Market Trends
      • 3.2.1. Shift toward recycled PET (rPET) driven by regulatory mandates and brand sustainability targets
      • 3.2.2. Growth in bio-based PET as a sustainable alternative to fossil-fuel-based resin
      • 3.2.3. Expansion of PET applications in automotive lightweighting and electronics
      • 3.2.4. Consolidation in the recycling sector to secure feedstock supply
    • 3.3. Market Restrains
      • 3.3.1. Stringent environmental regulations and plastic packaging taxes
      • 3.3.2. Volatility in feedstock prices (PTA and MEG)
      • 3.3.3. Limited recycling capacity and high contamination rates
    • 3.4. Market Restraints
      • 3.4.1. Stringent environmental regulations and plastic packaging taxes
Films & Sheets
  • Consumer Goods
  • Others
  • By Packaging Application

    • Bottled Water
    • Carbonated Soft Beverages
    • Juices
    • Alcoholic Beverages
    • Thermoforming Trays
    • Food Packaging
    • Non-Food Packaging
    • Others
  • By End User

    • Food & Beverages
    • Automotive
    • Electronics & Electrical
    • Construction
    • Others
  • By Geography
    • North America

      • USA
      • Canada
      • Mexico
    • Europe

      • Germany
      • UK
      • France
      • Italy
      • Spain
    • Asia Pacific

      • China
      • Japan
      • South Korea
      • India
      • Australia
    • Latin America

      • Brazil
      • Argentina
    • Middle East & Africa

      • South Africa
      • GCC
  • 3.4.2. Volatility in feedstock prices (PTA and MEG)
  • 3.4.3. Limited recycling capacity and high contamination rates
  • 3.5. Market Challenges
    • 3.5.1. Meeting recycled content targets due to supply constraints
    • 3.5.2. High capital costs for advanced recycling infrastructure
    • 3.5.3. Competition from alternative materials like glass and aluminum
  • 4. Market Factor Analysis
    • 4.1. Porters Five Forces
      • 4.1.1. Bargaining Power of Suppliers
      • 4.1.2. Bargaining Power of Buyers
      • 4.1.3. Threat of New Entrants
      • 4.1.4. Threat of Substitutes
      • 4.1.5. Competitive Rivalry
    • 4.2. PESTEL analysis
    • 4.3. BCG Analysis
      • 4.3.1. Stars (High Growth, High Market Share)
      • 4.3.2. Cash Cows (Low Growth, High Market Share)
      • 4.3.3. Question Mark (High Growth, Low Market Share)
      • 4.3.4. Dogs (Low Growth, Low Market Share)
    • 4.4. Ansoff Matrix Analysis
    • 4.5. Supply Chain Analysis
    • 4.6. Regulatory Landscape
    • 4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
    • 4.8. IMD Analyst Note
  • 5. Market Analysis, Insights and Forecast, 2020-2034
    • 5.1. Market Analysis, Insights and Forecast - by PET Type
      • 5.1.1. Transparent & Non-Transparent PET
      • 5.1.2. Recycled PET
    • 5.2. Market Analysis, Insights and Forecast - by Application
      • 5.2.1. Packaging
      • 5.2.2. Films & Sheets
      • 5.2.3. Consumer Goods
      • 5.2.4. Others
    • 5.3. Market Analysis, Insights and Forecast - by Packaging Application
      • 5.3.1. Bottled Water
      • 5.3.2. Carbonated Soft Beverages
      • 5.3.3. Juices
      • 5.3.4. Alcoholic Beverages
      • 5.3.5. Thermoforming Trays
      • 5.3.6. Food Packaging
      • 5.3.7. Non-Food Packaging
      • 5.3.8. Others
    • 5.4. Market Analysis, Insights and Forecast - by End User
      • 5.4.1. Food & Beverages
      • 5.4.2. Automotive
      • 5.4.3. Electronics & Electrical
      • 5.4.4. Construction
      • 5.4.5. Others
    • 5.5. Market Analysis, Insights and Forecast - by Region
      • 5.5.1. North America
      • 5.5.2. Europe
      • 5.5.3. Asia Pacific
      • 5.5.4. Latin America
      • 5.5.5. Middle East & Africa
  • 6. North America Market Analysis, Insights and Forecast, 2020-2034
    • 6.1. Market Analysis, Insights and Forecast - by PET Type
      • 6.1.1. Transparent & Non-Transparent PET
      • 6.1.2. Recycled PET
    • 6.2. Market Analysis, Insights and Forecast - by Application
      • 6.2.1. Packaging
      • 6.2.2. Films & Sheets
      • 6.2.3. Consumer Goods
      • 6.2.4. Others
    • 6.3. Market Analysis, Insights and Forecast - by Packaging Application
      • 6.3.1. Bottled Water
      • 6.3.2. Carbonated Soft Beverages
      • 6.3.3. Juices
      • 6.3.4. Alcoholic Beverages
      • 6.3.5. Thermoforming Trays
      • 6.3.6. Food Packaging
      • 6.3.7. Non-Food Packaging
      • 6.3.8. Others
    • 6.4. Market Analysis, Insights and Forecast - by End User
      • 6.4.1. Food & Beverages
      • 6.4.2. Automotive
      • 6.4.3. Electronics & Electrical
      • 6.4.4. Construction
      • 6.4.5. Others
  • 7. Europe Market Analysis, Insights and Forecast, 2020-2034
    • 7.1. Market Analysis, Insights and Forecast - by PET Type
      • 7.1.1. Transparent & Non-Transparent PET
      • 7.1.2. Recycled PET
    • 7.2. Market Analysis, Insights and Forecast - by Application
      • 7.2.1. Packaging
      • 7.2.2. Films & Sheets
      • 7.2.3. Consumer Goods
      • 7.2.4. Others
    • 7.3. Market Analysis, Insights and Forecast - by Packaging Application
      • 7.3.1. Bottled Water
      • 7.3.2. Carbonated Soft Beverages
      • 7.3.3. Juices
      • 7.3.4. Alcoholic Beverages
      • 7.3.5. Thermoforming Trays
      • 7.3.6. Food Packaging
      • 7.3.7. Non-Food Packaging
      • 7.3.8. Others
    • 7.4. Market Analysis, Insights and Forecast - by End User
      • 7.4.1. Food & Beverages
      • 7.4.2. Automotive
      • 7.4.3. Electronics & Electrical
      • 7.4.4. Construction
      • 7.4.5. Others
  • 8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
    • 8.1. Market Analysis, Insights and Forecast - by PET Type
      • 8.1.1. Transparent & Non-Transparent PET
      • 8.1.2. Recycled PET
    • 8.2. Market Analysis, Insights and Forecast - by Application
      • 8.2.1. Packaging
      • 8.2.2. Films & Sheets
      • 8.2.3. Consumer Goods
      • 8.2.4. Others
    • 8.3. Market Analysis, Insights and Forecast - by Packaging Application
      • 8.3.1. Bottled Water
      • 8.3.2. Carbonated Soft Beverages
      • 8.3.3. Juices
      • 8.3.4. Alcoholic Beverages
      • 8.3.5. Thermoforming Trays
      • 8.3.6. Food Packaging
      • 8.3.7. Non-Food Packaging
      • 8.3.8. Others
    • 8.4. Market Analysis, Insights and Forecast - by End User
      • 8.4.1. Food & Beverages
      • 8.4.2. Automotive
      • 8.4.3. Electronics & Electrical
      • 8.4.4. Construction
      • 8.4.5. Others
  • 9. Latin America Market Analysis, Insights and Forecast, 2020-2034
    • 9.1. Market Analysis, Insights and Forecast - by PET Type
      • 9.1.1. Transparent & Non-Transparent PET
      • 9.1.2. Recycled PET
    • 9.2. Market Analysis, Insights and Forecast - by Application
      • 9.2.1. Packaging
      • 9.2.2. Films & Sheets
      • 9.2.3. Consumer Goods
      • 9.2.4. Others
    • 9.3. Market Analysis, Insights and Forecast - by Packaging Application
      • 9.3.1. Bottled Water
      • 9.3.2. Carbonated Soft Beverages
      • 9.3.3. Juices
      • 9.3.4. Alcoholic Beverages
      • 9.3.5. Thermoforming Trays
      • 9.3.6. Food Packaging
      • 9.3.7. Non-Food Packaging
      • 9.3.8. Others
    • 9.4. Market Analysis, Insights and Forecast - by End User
      • 9.4.1. Food & Beverages
      • 9.4.2. Automotive
      • 9.4.3. Electronics & Electrical
      • 9.4.4. Construction
      • 9.4.5. Others
  • 10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
    • 10.1. Market Analysis, Insights and Forecast - by PET Type
      • 10.1.1. Transparent & Non-Transparent PET
      • 10.1.2. Recycled PET
    • 10.2. Market Analysis, Insights and Forecast - by Application
      • 10.2.1. Packaging
      • 10.2.2. Films & Sheets
      • 10.2.3. Consumer Goods
      • 10.2.4. Others
    • 10.3. Market Analysis, Insights and Forecast - by Packaging Application
      • 10.3.1. Bottled Water
      • 10.3.2. Carbonated Soft Beverages
      • 10.3.3. Juices
      • 10.3.4. Alcoholic Beverages
      • 10.3.5. Thermoforming Trays
      • 10.3.6. Food Packaging
      • 10.3.7. Non-Food Packaging
      • 10.3.8. Others
    • 10.4. Market Analysis, Insights and Forecast - by End User
      • 10.4.1. Food & Beverages
      • 10.4.2. Automotive
      • 10.4.3. Electronics & Electrical
      • 10.4.4. Construction
      • 10.4.5. Others
  • 11. Competitive Analysis
    • 11.1. Company Profiles
      • 11.1.1. Indorama Ventures
        • 11.1.1.1. Company Overview
        • 11.1.1.2. Products
        • 11.1.1.3. Company Financials
        • 11.1.1.4. SWOT Analysis
      • 11.1.2. Alpek
        • 11.1.2.1. Company Overview
        • 11.1.2.2. Products
        • 11.1.2.3. Company Financials
        • 11.1.2.4. SWOT Analysis
      • 11.1.3. Tongkun Group
        • 11.1.3.1. Company Overview
        • 11.1.3.2. Products
        • 11.1.3.3. Company Financials
        • 11.1.3.4. SWOT Analysis
      • 11.1.4. Xin Feng Ming Group
        • 11.1.4.1. Company Overview
        • 11.1.4.2. Products
        • 11.1.4.3. Company Financials
        • 11.1.4.4. SWOT Analysis
      • 11.1.5. Zhejiang Hengyi
        • 11.1.5.1. Company Overview
        • 11.1.5.2. Products
        • 11.1.5.3. Company Financials
        • 11.1.5.4. SWOT Analysis
      • 11.1.6. Reliance Industries
        • 11.1.6.1. Company Overview
        • 11.1.6.2. Products
        • 11.1.6.3. Company Financials
        • 11.1.6.4. SWOT Analysis
      • 11.1.7. FENC
        • 11.1.7.1. Company Overview
        • 11.1.7.2. Products
        • 11.1.7.3. Company Financials
        • 11.1.7.4. SWOT Analysis
      • 11.1.8. Sheng Hong Group
        • 11.1.8.1. Company Overview
        • 11.1.8.2. Products
        • 11.1.8.3. Company Financials
        • 11.1.8.4. SWOT Analysis
      • 11.1.9. Hengli Group
        • 11.1.9.1. Company Overview
        • 11.1.9.2. Products
        • 11.1.9.3. Company Financials
        • 11.1.9.4. SWOT Analysis
      • 11.1.10. Billion Industrial
        • 11.1.10.1. Company Overview
        • 11.1.10.2. Products
        • 11.1.10.3. Company Financials
        • 11.1.10.4. SWOT Analysis
      • 11.1.11. Rongsheng Petrochemical
        • 11.1.11.1. Company Overview
        • 11.1.11.2. Products
        • 11.1.11.3. Company Financials
        • 11.1.11.4. SWOT Analysis
      • 11.1.12. Sanfangxiang Group
        • 11.1.12.1. Company Overview
        • 11.1.12.2. Products
        • 11.1.12.3. Company Financials
        • 11.1.12.4. SWOT Analysis
      • 11.1.13. Sinopec Yizheng
        • 11.1.13.1. Company Overview
        • 11.1.13.2. Products
        • 11.1.13.3. Company Financials
        • 11.1.13.4. SWOT Analysis
      • 11.1.14. CR Chemical Materials
        • 11.1.14.1. Company Overview
        • 11.1.14.2. Products
        • 11.1.14.3. Company Financials
        • 11.1.14.4. SWOT Analysis
      • 11.1.15. JBF Industries
        • 11.1.15.1. Company Overview
        • 11.1.15.2. Products
        • 11.1.15.3. Company Financials
        • 11.1.15.4. SWOT Analysis
      • 11.1.16. NanYa
        • 11.1.16.1. Company Overview
        • 11.1.16.2. Products
        • 11.1.16.3. Company Financials
        • 11.1.16.4. SWOT Analysis
      • 11.1.17. Wankai New Materials
        • 11.1.17.1. Company Overview
        • 11.1.17.2. Products
        • 11.1.17.3. Company Financials
        • 11.1.17.4. SWOT Analysis
      • 11.1.18. Dhunseri Ventures Limited
        • 11.1.18.1. Company Overview
        • 11.1.18.2. Products
        • 11.1.18.3. Company Financials
        • 11.1.18.4. SWOT Analysis
      • 11.1.19. SABIC
        • 11.1.19.1. Company Overview
        • 11.1.19.2. Products
        • 11.1.19.3. Company Financials
        • 11.1.19.4. SWOT Analysis
      • 11.1.20. NEO GROUP
        • 11.1.20.1. Company Overview
        • 11.1.20.2. Products
        • 11.1.20.3. Company Financials
        • 11.1.20.4. SWOT Analysis
      • 11.1.21. Lotte Chemical
        • 11.1.21.1. Company Overview
        • 11.1.21.2. Products
        • 11.1.21.3. Company Financials
        • 11.1.21.4. SWOT Analysis
      • 11.1.22. Toray
        • 11.1.22.1. Company Overview
        • 11.1.22.2. Products
        • 11.1.22.3. Company Financials
        • 11.1.22.4. SWOT Analysis
      • 11.1.23. KoKsan
        • 11.1.23.1. Company Overview
        • 11.1.23.2. Products
        • 11.1.23.3. Company Financials
        • 11.1.23.4. SWOT Analysis
      • 11.1.24. Sibur (Polief)
        • 11.1.24.1. Company Overview
        • 11.1.24.2. Products
        • 11.1.24.3. Company Financials
        • 11.1.24.4. SWOT Analysis
      • 11.1.25. Asia Pacific Fibers (APF)
        • 11.1.25.1. Company Overview
        • 11.1.25.2. Products
        • 11.1.25.3. Company Financials
        • 11.1.25.4. SWOT Analysis
      • 11.1.26. Alpla
        • 11.1.26.1. Company Overview
        • 11.1.26.2. Products
        • 11.1.26.3. Company Financials
        • 11.1.26.4. SWOT Analysis
    • 11.2. Market Entropy
      • 11.2.1. Company's Key Areas Served
      • 11.2.2. Recent Developments
    • 11.3. Company Market Share Analysis, 2026
      • 11.3.1. Top 5 Companies Market Share Analysis
      • 11.3.2. Top 3 Companies Market Share Analysis
    • 11.4. List of Potential Customers
  • List of Figures

    1. Figure 1: Global Polyethylene Terephthalate (PET) Resin Report Revenue Breakdown (Billion, %) by Region 2026 & 2034
    2. Figure 2: North America Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by PET Type 2026 & 2034
    3. Figure 3: North America Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by PET Type 2026 & 2034
    4. Figure 4: North America Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by Application 2026 & 2034
    5. Figure 5: North America Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by Application 2026 & 2034
    6. Figure 6: North America Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by Packaging Application 2026 & 2034
    7. Figure 7: North America Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by Packaging Application 2026 & 2034
    8. Figure 8: North America Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by End User 2026 & 2034
    9. Figure 9: North America Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by End User 2026 & 2034
    10. Figure 10: North America Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by Country 2026 & 2034
    11. Figure 11: North America Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by Country 2026 & 2034
    12. Figure 12: Europe Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by PET Type 2026 & 2034
    13. Figure 13: Europe Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by PET Type 2026 & 2034
    14. Figure 14: Europe Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by Application 2026 & 2034
    15. Figure 15: Europe Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by Application 2026 & 2034
    16. Figure 16: Europe Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by Packaging Application 2026 & 2034
    17. Figure 17: Europe Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by Packaging Application 2026 & 2034
    18. Figure 18: Europe Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by End User 2026 & 2034
    19. Figure 19: Europe Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by End User 2026 & 2034
    20. Figure 20: Europe Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by Country 2026 & 2034
    21. Figure 21: Europe Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by Country 2026 & 2034
    22. Figure 22: Asia Pacific Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by PET Type 2026 & 2034
    23. Figure 23: Asia Pacific Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by PET Type 2026 & 2034
    24. Figure 24: Asia Pacific Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by Application 2026 & 2034
    25. Figure 25: Asia Pacific Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by Application 2026 & 2034
    26. Figure 26: Asia Pacific Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by Packaging Application 2026 & 2034
    27. Figure 27: Asia Pacific Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by Packaging Application 2026 & 2034
    28. Figure 28: Asia Pacific Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by End User 2026 & 2034
    29. Figure 29: Asia Pacific Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by End User 2026 & 2034
    30. Figure 30: Asia Pacific Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by Country 2026 & 2034
    31. Figure 31: Asia Pacific Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by Country 2026 & 2034
    32. Figure 32: Latin America Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by PET Type 2026 & 2034
    33. Figure 33: Latin America Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by PET Type 2026 & 2034
    34. Figure 34: Latin America Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by Application 2026 & 2034
    35. Figure 35: Latin America Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by Application 2026 & 2034
    36. Figure 36: Latin America Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by Packaging Application 2026 & 2034
    37. Figure 37: Latin America Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by Packaging Application 2026 & 2034
    38. Figure 38: Latin America Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by End User 2026 & 2034
    39. Figure 39: Latin America Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by End User 2026 & 2034
    40. Figure 40: Latin America Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by Country 2026 & 2034
    41. Figure 41: Latin America Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by Country 2026 & 2034
    42. Figure 42: Middle East & Africa Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by PET Type 2026 & 2034
    43. Figure 43: Middle East & Africa Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by PET Type 2026 & 2034
    44. Figure 44: Middle East & Africa Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by Application 2026 & 2034
    45. Figure 45: Middle East & Africa Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by Application 2026 & 2034
    46. Figure 46: Middle East & Africa Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by Packaging Application 2026 & 2034
    47. Figure 47: Middle East & Africa Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by Packaging Application 2026 & 2034
    48. Figure 48: Middle East & Africa Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by End User 2026 & 2034
    49. Figure 49: Middle East & Africa Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by End User 2026 & 2034
    50. Figure 50: Middle East & Africa Polyethylene Terephthalate (PET) Resin Report Revenue (Billion), by Country 2026 & 2034
    51. Figure 51: Middle East & Africa Polyethylene Terephthalate (PET) Resin Report Revenue Share (%), by Country 2026 & 2034

    List of Tables

    1. Table 1: Global Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by PET Type 2020 & 2034
    2. Table 2: Global Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Application 2020 & 2034
    3. Table 3: Global Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Packaging Application 2020 & 2034
    4. Table 4: Global Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by End User 2020 & 2034
    5. Table 5: Global Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Region 2020 & 2034
    6. Table 6: North America Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by PET Type 2020 & 2034
    7. Table 7: North America Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Application 2020 & 2034
    8. Table 8: North America Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Packaging Application 2020 & 2034
    9. Table 9: North America Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by End User 2020 & 2034
    10. Table 10: North America Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Country 2020 & 2034
    11. Table 11: USA Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034
    12. Table 12: Canada Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034
    13. Table 13: Mexico Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034
    14. Table 14: Europe Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by PET Type 2020 & 2034
    15. Table 15: Europe Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Application 2020 & 2034
    16. Table 16: Europe Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Packaging Application 2020 & 2034
    17. Table 17: Europe Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by End User 2020 & 2034
    18. Table 18: Europe Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Country 2020 & 2034
    19. Table 19: Germany Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034
    20. Table 20: UK Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034
    21. Table 21: France Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034
    22. Table 22: Italy Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034
    23. Table 23: Spain Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034
    24. Table 24: Asia Pacific Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by PET Type 2020 & 2034
    25. Table 25: Asia Pacific Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Application 2020 & 2034
    26. Table 26: Asia Pacific Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Packaging Application 2020 & 2034
    27. Table 27: Asia Pacific Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by End User 2020 & 2034
    28. Table 28: Asia Pacific Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Country 2020 & 2034
    29. Table 29: China Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034
    30. Table 30: Japan Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034
    31. Table 31: South Korea Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034
    32. Table 32: India Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034
    33. Table 33: Australia Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034
    34. Table 34: Latin America Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by PET Type 2020 & 2034
    35. Table 35: Latin America Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Application 2020 & 2034
    36. Table 36: Latin America Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Packaging Application 2020 & 2034
    37. Table 37: Latin America Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by End User 2020 & 2034
    38. Table 38: Latin America Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Country 2020 & 2034
    39. Table 39: Brazil Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034
    40. Table 40: Argentina Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034
    41. Table 41: Middle East & Africa Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by PET Type 2020 & 2034
    42. Table 42: Middle East & Africa Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Application 2020 & 2034
    43. Table 43: Middle East & Africa Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Packaging Application 2020 & 2034
    44. Table 44: Middle East & Africa Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by End User 2020 & 2034
    45. Table 45: Middle East & Africa Polyethylene Terephthalate (PET) Resin Report Revenue Billion Forecast, by Country 2020 & 2034
    46. Table 46: South Africa Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034
    47. Table 47: GCC Polyethylene Terephthalate (PET) Resin Report Revenue (Billion) Forecast, by Application 2020 & 2034

    Frequently Asked Questions

    1What is the current market size of the PET resin market?

    The global PET resin market is valued at **USD 43.29 Billion** in 2025 and is projected to reach **USD 64.94 Billion by 2033**, growing at a **5.2% CAGR**.

    2Who are the key players in the PET resin market?

    Key players include Indorama Ventures, Alpek, Tongkun Group, Reliance Industries, FENC, SABIC, and Alpla, with the top five holding approximately **33%** of global market share.

    3What is driving the growth of the PET resin market?

    Growth is driven by the expansion of the food and beverage packaging industry, increasing demand for recyclable materials, and urbanization in emerging markets like China and India.

    4What are the regulatory challenges facing the PET resin market?

    Stringent regulations, such as the UK's plastic packaging tax of **GBP 228.82 per tonne** on packaging with less than 30% recycled content, and South Korea's recycled content mandate, are adding cost and complexity for producers.

    5Which region is expected to grow fastest in the PET resin market?

    Asia-Pacific is the fastest-growing region, with a projected CAGR of **3.5% in South Korea** and **3.2% in China** from 2026 to 2036, driven by rising packaged food consumption and manufacturing growth.

    Methodology

    Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.

    Primary Research

    • Conducted 70–80% of research through direct interviews with key stakeholders across the PET resin value chain, including resin producers, recyclers, packaging converters, and brand owners.
    • Surveyed a diverse mix of company types: PET resin manufacturers (35%), recycled PET processors (25%), packaging converters (20%), brand owners and FMCG companies (12%), and feedstock suppliers (8%).
    • Interviewed stakeholders in roles such as Procurement Director, Sustainability Manager, Operations Vice President, and R&D Director to capture strategic and operational insights.
    • Engaged with industry associations including the American Chemistry Council (ACC), Plastics Europe, PET Core Europe, and National Association for PET Container Resources (NAPCOR) to validate regulatory and technical trends.

    Key Stakeholders Interviewed

    Main Logo
    Key Stakeholders Interviewed
    Stakeholder RoleInterview Share (%)
    Procurement Director30%
    Sustainability Manager25%
    Operations Vice President25%
    R&D Director20%

    Industry Ecosystem Breakdown

    Main Logo
    Industry Ecosystem Breakdown
    Company TypeRepresentation (%)
    PET Resin Manufacturers35%
    Recycled PET Processors25%
    Packaging Converters20%
    Brand Owners and FMCG Companies12%
    Feedstock Suppliers8%

    Secondary Research & Industry Benchmarking

    • Utilized 20–30% secondary research from standard financial databases (Bloomberg, Factiva, Hoovers, PitchBook) and official government sources (UN Comtrade, World Bank, US ITC, Eurostat).
    • Referenced technical standards and trade statistics from recognized non-profit organizations such as ISO and ASTM International for material properties and testing protocols.
    • Benchmarked market data against published reports from multilateral institutions and trade associations, ensuring data triangulation and consistency.
    • All secondary data was cross-validated with primary interview findings to ensure accuracy and relevance.

    Demand Modeling & Market Estimation

    • Employed a simultaneous top-down and bottom-up approach. Top-down analysis utilized global production capacities and trade flows, while bottom-up analysis aggregated demand from end-use sectors.
    • Key quantitative metrics used in bottom-up modeling included: PET bottle production volumes (in kilotons), per-capita packaging consumption by region, recycled content percentages mandated by regulations, and average resin prices by grade.
    • Demand models incorporated macroeconomic variables such as GDP growth, population growth, and urbanization rates to forecast consumption across 15+ countries.
    • Segmented demand by application (packaging, films, consumer goods) and end-user (food & beverage, automotive, electronics) to capture granular market dynamics.

    Data Accuracy & Quality Check

    • Guaranteed estimated data accuracy level of 85–90% through rigorous multi-level data triangulation and validation.
    • Conducted sanity checks on all market size and forecast figures against historical trends and industry benchmarks.
    • All reports are updated to the date of purchase to reflect the latest market developments and regulatory changes.
    • Final data sets were reviewed by a panel of internal experts and external advisors to ensure analytical rigor and reliability.
    Author
    Khageshwar Rongkali

    Khageshwar Rongkali

    Senior Analyst

    As a Senior Analyst operating across Chemicals & Materials (including Bulk, Specialty & Fine Chemicals), Industrials, and Industrial Automation & Equipment, I deliver robust commercial due diligence and market-sizing projects. My expertise also spans Professional and Commercial Services, executing strategic research initiatives that break down intricate supply chain dynamics and competitive landscapes. Leveraging my experience in managing focused research teams, I ensure data-driven analysis that strengthens market positioning for global enterprises across industrial and consumer sectors.

    Get In Touch
    WHY IMD

    Verified research

    Analyst-reviewed data

    Updated Nov 04, 2026

    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    sponsor image
    CUSTOM INTELLIGENCE

    Tailored for you

    • In-depth Analysis Tailored to Specified Regions or Segments
    • Company Profiles Customized to User Preferences
    • Customized Evaluation of Competitive Landscape to Meet Your Needs
    Ask for customization
    avatar

    Analyst at Providence Strategic Partners at Petaling Jaya

    Jared Wan

    I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

    avatar

    Internationalization Director

    Santiago Mejia Molina

    Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

    avatar

    Head of Product Management and Marketing

    Olaf Gleibe

    We are using your report, and it gave us valuable information."

    avatar

    Regional Director, Marketing and Business Development

    Lina Lim

    We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

    avatar

    VP of Sales

    DIGGLE Representative

    Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.

    artwork spiralartwork spiralRelated Reports
    artwork underline

    Raw Materials for Personal Care Future Market Report 2026-2035

    The raw materials for personal care market is set to grow at a 6.1% CAGR, reaching $27.1B by 2033, driven by natural and sustainable ingredient demand.

    Nov 2026|250 pages
    $2900.00View report

    High Speed Digital CCL market valued at $1.26B in 2025, growing at 5.1% CAGR to reach $2.07B by 2035. Rising demand from 5G, data centers, and automotive electronics.

    Nov 2026|206 pages
    $2900.00

    SSAW steel pipe market valued at USD 6.5 Billion in 2025, projected to reach USD 10.71 Billion by 2034 at a 5.71% CAGR driven by oil, gas and water infrastructure.

    Nov 2026|180 pages
    $2900.00

    Composite resin tooth filling material market to reach $2.1B by 2035 at 5.2% CAGR, driven by aesthetic dentistry and nanohybrid innovations.

    Nov 2026|223 pages
    $2900.00

    The catalytic reforming catalyst market was valued at USD 1.24 billion in 2025 and is projected to reach USD 1.78 billion by 2034, growing at a 4.1% CAGR.

    Nov 2026|242 pages
    $2900.00
    High Speed Digital Copper Clad Laminate (CCL) Market 2025-2035
    View report
    SSAW Steel Pipe Market Size, Growth & Forecast to 2034
    View report
    Composite Resin Tooth Filling Material Market Report 2025-2035
    View report
    Catalytic Reforming Catalyst Market Size & Forecast 2026-2034
    View report