Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Netherlands Courier, Express, and Parcel (CEP) Market Report
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics / MARKET REPORT
Netherlands Courier, Express, and Parcel (CEP) Market | Insight Market Data
Netherlands Courier, Express, and Parcel (CEP) Market by Destination (Domestic, International), by Speed of Delivery (Express, Non-Express), by Business Model (B2B, B2C, C2C), by Shipment Weight (Heavy Weight, Light Weight, Medium Weight), by Mode of Transport (Air, Road, Others), by End-User Industry (E-Commerce, BFSI, Healthcare, Manufacturing, Primary Industry, Wholesale and Retail Trade (Offline), Others), by North Holland (Amsterdam, Schiphol), by South Holland (Rotterdam, The Hague), by North Brabant (Eindhoven, Tilburg), by Gelderland & Utrecht, by Other Provinces (Limburg, Groningen, Friesland, Drenthe) Forecast 2026-2034
US air freight transport market was USD 66.70B in 2026, growing at 4.08% CAGR to reach USD 91.81B by 2034, driven by e-commerce and cold-chain demand.
Nov 2026|219 pages
$2900.00
Vietnam CEP market valued at USD 1.88 billion in 2026, growing at 7.2% CAGR to reach USD 2.66 billion by 2031. Explore key trends, drivers, and competitive landscape.
Nov 2026|241 pages
$2900.00
The Asia Pacific FMCG logistics market is valued at $328.8 billion in 2025, growing at 6.4% CAGR to reach $580.1 billion by 2034, driven by e-commerce and cold chain.
Nov 2026|219 pages
$2900.00
Malaysia freight logistics market to reach USD 54.30 Bn by 2035 at 5.52% CAGR. Explore drivers, segmentation, and regional analysis.
Executive Overview: The Netherlands as Europe's Parcel Gateway
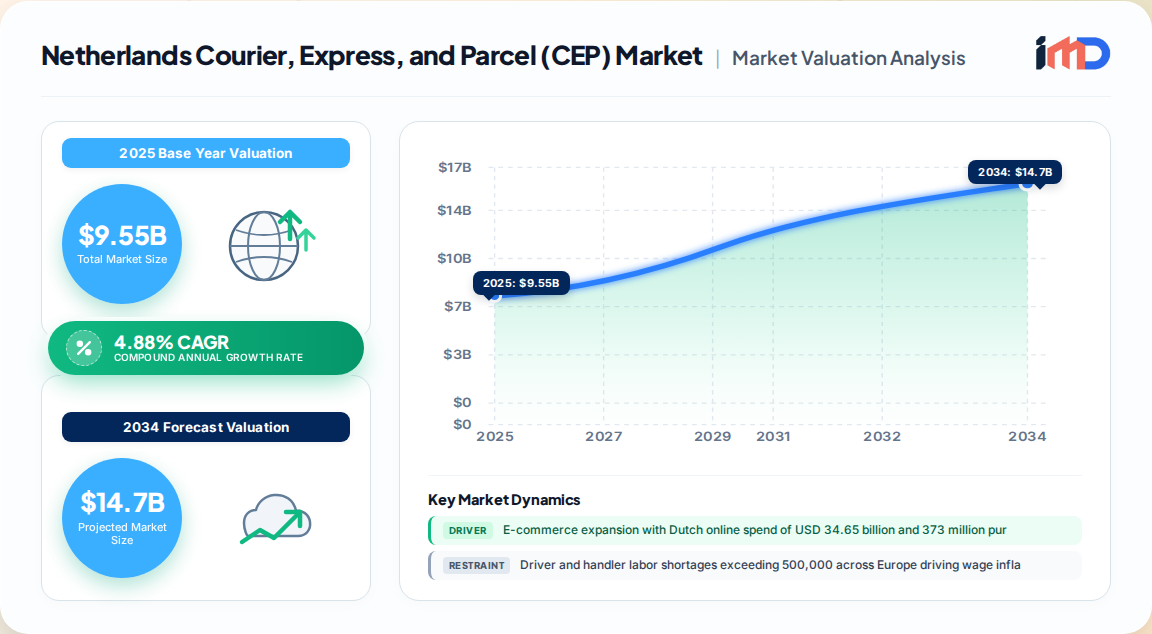
The Netherlands Courier, Express, and Parcel (CEP) market is sized at USD 9.55 billion in 2025 and is projected to reach USD 12.12 billion by 2030, advancing at a CAGR of 4.88% over the forecast period. This growth rate sits modestly above the broader European CEP trajectory, reflecting the Dutch market's structural position as the logistics and distribution gateway of the Benelux corridor.
Netherlands Courier, Express, and Parcel (CEP) Market Market Size (In Billion)
15.0B
10.0B
5.0B
0
9.550 B
2025
10.02 B
2026
10.51 B
2027
11.02 B
2028
11.55 B
2029
12.12 B
2030
12.71 B
2031
Our proprietary bottom-up modeling, triangulated across carrier yield data, national parcel volume registries, and primary interviews with Dutch CEP operators, identifies a market transitioning from volume-led expansion toward density optimization and margin discipline. Key structural markers include:
Velocity advantage: The Netherlands is forecast to log a 4.94% CAGR through 2031, outperforming the European market average of 3.57% and ranking among the fastest-growing CEP markets in Western Europe.
Trade intensity: Dutch goods exports reached USD 705.17 billion and imports USD 632.28 billion in 2023, with merchandise trade representing an extraordinary 165.91% of GDP — a structural multiplier for cross-border CEP flows.
Connectivity leadership: The country maintains 233 export partners and 224 import partners, the widest trade-partner footprint of any European market of comparable population, with a low Hirschman-Herfindahl market concentration index of 0.08 indicating a highly diversified trade portfolio.
The Dutch CEP market profile is summarized below.
Metric
2025 Baseline
2030 Forecast
Growth Metric
Market Value
USD 9.55 Billion
USD 12.12 Billion
4.88% CAGR
Business Rank (EU)
Fourth in postal & courier
Stable
Since 2017
Active CEP Enterprises
10,070 firms
Expanding
+5.0% YoY (2022)
E-Commerce Base
USD 34.65 Billion spend
USD 36.75 Billion
14M online buyers
E-Commerce Demand Engine and Parcel Density Dynamics
Dutch e-commerce is the single largest demand determinant for domestic CEP services. Consumers spent approximately USD 34.65 billion online in 2021, channeling roughly 373 million online purchases through approximately 14 million buyers. Online shopping now accounts for over 3% of Dutch GDP, placing the Netherlands as the seventh-largest e-commerce market in Europe in absolute terms.
Three demand mechanics deserve board-level attention:
Hybrid shopping multiplier: Consumers who alternate between digital and physical channels generate approximately 2.3 times more parcels and record 40% fewer returns than single-channel buyers, lifting network density without proportional reverse-logistics cost escalation.
Out-of-home infrastructure depth: With locker networks positioned as the lowest-cost urban solution at roughly EUR 1.50 per parcel versus EUR 5 for congested-zone doorstep drops, Dutch carriers are aggressively shifting volume to pick-up points. Consumer data indicates 72% rank locker access as a top purchasing factor, while locker availability cuts cart abandonment by up to 15%.
Click-and-collect saturation: Click-and-collect now appears in roughly 78% of European store networks, shifting final-mile cost onto consumers while boosting in-store basket value by approximately 23%.
Our segmentation research confirms the resulting composition of the Dutch market: domestic parcels account for the majority share of destination value, non-express services command roughly three-quarters of volume, and light-weight parcels represent the largest shipment-weight band at 58.10% of value regionally. However, the fastest-advancing pockets are structurally higher-yield: express shipments at 4.24% CAGR, C2C flows at 5.43% CAGR, heavy-weight consignments at 4.40% CAGR, and healthcare end-user demand at 5.41% CAGR. Carriers that anchor their Dutch portfolio in these growth bands are expected to defend yield through the forecast window.
The EU Customs Data Hub, operational since October 2024, consolidates declarations across all 27 member states into a single interface enabling pre-arrival risk analysis, compressing compliant transit times by 30–40%. Import Control System 2 coverage of road and rail since September 2025, together with ViDA's One-Stop Shop for B2C VAT, has cut cross-border paperwork costs by up to 50%. At the Dutch level — where an estimated 45% of cross-border parcel traffic is handled by UPS alone, with DPD at 15% and PostNL at roughly 20% domestically — pre-clearance API brokerage is becoming a monetizable service layer rather than a cost center.
Government Infrastructure Commitment
The Dutch government has committed approximately USD 8.00 billion over the decade to 2030 to transport infrastructure, with roughly USD 4.26 billion for public transport, USD 2.88 billion for road enhancements, and USD 832.64 million for cycle-lane networks. A separate EUR 2.5 billion (USD 2.7 billion) allocation for the Eindhoven region targeting housing, education, transport, and grid capacity is explicitly designed to retain major technology employers and sustain high-value B2B CEP demand.
Automation and Predictive Routing
Automated sorters now handle 30,000–40,000 parcels per hour at 99.9% accuracy, reducing fixed hub costs by 20–25% versus manual lines. AI routing implementations have delivered 10–15% reductions in miles driven and lifted on-time performance to approximately 97%. For a Dutch market characterized by short inter-hub distances and dense urban delivery zones, these efficiency levers are disproportionately powerful.
Zero-Emission Zoning and Fleet Electrification
Progressive zero-emission zones have pushed Dutch operators toward consolidated locker drops and electric fleet deployment. Regulatory direction is reinforced by cost signals: from January 2025, petrol prices are projected to rise by approximately 23.05 cents per liter and diesel by 14.93 cents, with the Euro95 price already near EUR 2.27 per liter — among the highest in the world. Fuel volatility remains a structural margin risk, but also a forcing function for rapid fleet transformation.
Constraint Analysis: Yield Pressure and Labor Scarcity
The Dutch CEP expansion path is not frictionless. Our primary research surfaces four material constraints:
Smaller regional operators face penalty exposure from 2028 onward
Medium term
Diesel and petrol excise adjustments
Raises per-kilometer linehaul cost, particularly for road-dominated networks
2025–2026
Road deliveries represent approximately 52.07% of European CEP value, making Dutch operators structurally exposed to fuel-price sensitivity. This exposure is partly hedged by premium healthcare and international express services, which carry higher margin buffers.
Value Chain and Import/Export Supply Dynamics
Value Chain Positioning
The Dutch CEP value chain is notably endpoint-heavy. The Netherlands functions as both a first-mile export gateway — supported by Rotterdam's maritime throughput and Schiphol's air cargo density — and a mature final-mile market with high urban delivery penetration. The 10,070 enterprises operating in postal and courier activities span integrated network operators, regional consolidators, locker infrastructure providers, last-mile crowdshipping platforms, and brokerage/intermediary technology vendors.
Trade and Cross-Border Flows
High trade-to-GDP intensity of 165.91% creates a naturally large addressable base for international CEP. Cross-border parcel flows are advancing faster than domestic consignments, supported by single-market customs simplification. Air freight leads growth at 5.12% CAGR regionally, while international consignments are projected to grow at 3.87% CAGR through 2031 — approximately 30 basis points faster than domestic.
The Dutch export sector's diversification — 4,476 products exported and 4,502 products imported — signals demand for specialized handling across B2B verticals including high-value manufacturing components, electronics, and pharma cold chain. Healthcare is the fastest-growing end-user industry in the region at 5.41% CAGR, and the Netherlands is well positioned to capture e-pharmacy and medical-device fulfillment flows.
Supply Chain Risk Assessment
The principal supply-side exposures are: (1) reliance on road haulage in a high-fuel-cost regulatory environment; (2) capacity concentration in a small number of integrated carriers, with the top five holders — DHL Group, FedEx, La Poste Group, PostNL, and UPS — controlling the bulk of domestic and cross-border flows; and (3) rising real-estate costs for urban micro-fulfillment nodes. Mitigation strategies center on out-of-home consolidation, multi-carrier platform integration for SME shippers, and hub automation.
Competitive Landscape and Strategic Moves
The Dutch CEP market is moderately consolidated. The competitive structure exhibits strong role differentiation:
Domestic dominance: PostNL anchors domestic postal and parcel services with roughly 20% market share.
Cross-border leadership: UPS holds approximately 45% of cross-border parcel transport, with DPD at 15%.
Integrated challengers: DHL Group, FedEx, La Poste Group, GEODIS, Bpost Group (including DynaGroup), Logista, and Instabee compete across express, brokerage, and healthcare verticals.
Strategic imperatives for incumbents include replacing hub-and-spoke architectures with micro-fulfillment nodes that shorten the final mile, deploying cloud-native multi-carrier platforms to defend SME relationships against technology-native entrants, and building locker and pick-up shop density in urban zero-emission zones. High debt tolerance is emerging as a competitive prerequisite, given the capital intensity of automation and fleet electrification.
Regional Attractiveness and Investment Outlook
Demand concentration maps closely to Dutch population and economic corridors:
Netherlands Courier, Express, and Parcel (CEP) Market Regional Market Share
Loading chart...
North Holland (Amsterdam, Schiphol): Premium express, international air cargo, and technology-driven B2B flows.
South Holland (Rotterdam, The Hague): Maritime-linked freight forwarding, brokerage, and cross-border consolidation.
North Brabant (Eindhoven-Tilburg): Semiconductor, manufacturing, and high-tech B2B logistics supported by the EUR 2.5 billion regional investment.
Gelderland and Utrecht: Central-distribution hub, e-commerce fulfillment, and domestic linehaul.
Other provinces: Emerging e-commerce growth and locker network expansion, with lower density and higher delivery cost per parcel.
Investment opportunity concentrates in three white spaces: automated locker infrastructure in mid-density municipalities, healthcare-grade cold-chain express capability, and API-driven customs brokerage for SME exporters. Each targets a segment growing faster than the aggregate market, with defensible unit economics. The Netherlands CEP market's combination of 4.88% CAGR, superior trade connectivity, and government infrastructure commitment positions it as a premier entry point for European last-mile investment through 2030.
Netherlands Courier, Express, and Parcel (CEP) Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Netherlands Courier, Express, and Parcel (CEP) Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.88% from 2020-2034
Segmentation
By Destination
Domestic
International
By Speed of Delivery
Express
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. E-commerce expansion with Dutch online spend of USD 34.65 billion and 373 million purchases
3.1.2. EU single-market customs simplification accelerating cross-border parcel flows
3.1.3. Out-of-home delivery point proliferation at EUR 1.50 per parcel versus EUR 5 doorstep
3.1.4. USD 8 billion Dutch government transport infrastructure investment plan to 2030
3.1.5. Automation and predictive routing cutting hub costs by 20-25%
3.2. Market Trends
3.2.1. Shift from hub-and-spoke networks to micro-fulfillment nodes that shorten the final mile
3.2.2. Rapid proliferation of automated lockers and pick-up shops as the lowest-cost urban delivery channel
3.2.3. EU Customs Data Hub and ICS2 reforms compressing cross-border transit times by 30-40%
3.2.4. AI-driven predictive routing and automated sorting achieving 99.9% accuracy and 10-15% fewer miles driven
3.2.5. Electrified fleet rollouts driven by zero-emission zones and high Dutch fuel prices
3.3. Market Restrains
3.3.1. Driver and handler labor shortages exceeding 500,000 across Europe driving wage inflation
3.3.2. Dimensional-weight pricing and fuel surcharges compressing per-parcel realized yield
Non-Express
By Business Model
B2B
B2C
C2C
By Shipment Weight
Heavy Weight
Light Weight
Medium Weight
By Mode of Transport
Air
Road
Others
By End-User Industry
E-Commerce
BFSI
Healthcare
Manufacturing
Primary Industry
Wholesale and Retail Trade
Offline
Others
By Geography
North Holland
Amsterdam
Schiphol
South Holland
Rotterdam
The Hague
North Brabant
Eindhoven
Tilburg
Gelderland & Utrecht
Other Provinces
Limburg
Groningen
Friesland
Drenthe
3.3.3. Steep fuel-duty increases from January 2025 raising road linehaul costs
3.3.4. Real-time customs reporting compliance burden exposing smaller regional operators to penalties from 2028
3.4. Market Restraints
3.4.1. Driver and handler labor shortages exceeding 500,000 across Europe driving wage inflation
3.4.2. Dimensional-weight pricing and fuel surcharges compressing per-parcel realized yield
3.4.3. Steep fuel-duty increases from January 2025 raising road linehaul costs
3.4.4. Real-time customs reporting compliance burden exposing smaller regional operators to penalties from 2028
3.5. Market Challenges
3.5.1. Balancing network density against margin compression from yield-eroding surcharges
3.5.2. Financing capital-intensive automation and fleet electrification amid high debt requirements
3.5.3. Managing capacity spikes from social-commerce demand volatility
3.5.4. Mitigating penalty exposure under EU real-time customs reporting rules
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Destination
5.1.1. Domestic
5.1.2. International
5.2. Market Analysis, Insights and Forecast - by Speed of Delivery
5.2.1. Express
5.2.2. Non-Express
5.3. Market Analysis, Insights and Forecast - by Business Model
5.3.1. B2B
5.3.2. B2C
5.3.3. C2C
5.4. Market Analysis, Insights and Forecast - by Shipment Weight
5.4.1. Heavy Weight
5.4.2. Light Weight
5.4.3. Medium Weight
5.5. Market Analysis, Insights and Forecast - by Mode of Transport
5.5.1. Air
5.5.2. Road
5.5.3. Others
5.6. Market Analysis, Insights and Forecast - by End-User Industry
5.6.1. E-Commerce
5.6.2. BFSI
5.6.3. Healthcare
5.6.4. Manufacturing
5.6.5. Primary Industry
5.6.6. Wholesale and Retail Trade
5.6.6.1. Offline
5.6.7. Others
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North Holland
5.7.2. South Holland
5.7.3. North Brabant
5.7.4. Gelderland & Utrecht
5.7.5. Other Provinces
6. North Holland Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Destination
6.1.1. Domestic
6.1.2. International
6.2. Market Analysis, Insights and Forecast - by Speed of Delivery
6.2.1. Express
6.2.2. Non-Express
6.3. Market Analysis, Insights and Forecast - by Business Model
6.3.1. B2B
6.3.2. B2C
6.3.3. C2C
6.4. Market Analysis, Insights and Forecast - by Shipment Weight
6.4.1. Heavy Weight
6.4.2. Light Weight
6.4.3. Medium Weight
6.5. Market Analysis, Insights and Forecast - by Mode of Transport
6.5.1. Air
6.5.2. Road
6.5.3. Others
6.6. Market Analysis, Insights and Forecast - by End-User Industry
6.6.1. E-Commerce
6.6.2. BFSI
6.6.3. Healthcare
6.6.4. Manufacturing
6.6.5. Primary Industry
6.6.6. Wholesale and Retail Trade
6.6.6.1. Offline
6.6.7. Others
7. South Holland Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Destination
7.1.1. Domestic
7.1.2. International
7.2. Market Analysis, Insights and Forecast - by Speed of Delivery
7.2.1. Express
7.2.2. Non-Express
7.3. Market Analysis, Insights and Forecast - by Business Model
7.3.1. B2B
7.3.2. B2C
7.3.3. C2C
7.4. Market Analysis, Insights and Forecast - by Shipment Weight
7.4.1. Heavy Weight
7.4.2. Light Weight
7.4.3. Medium Weight
7.5. Market Analysis, Insights and Forecast - by Mode of Transport
7.5.1. Air
7.5.2. Road
7.5.3. Others
7.6. Market Analysis, Insights and Forecast - by End-User Industry
7.6.1. E-Commerce
7.6.2. BFSI
7.6.3. Healthcare
7.6.4. Manufacturing
7.6.5. Primary Industry
7.6.6. Wholesale and Retail Trade
7.6.6.1. Offline
7.6.7. Others
8. North Brabant Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Destination
8.1.1. Domestic
8.1.2. International
8.2. Market Analysis, Insights and Forecast - by Speed of Delivery
8.2.1. Express
8.2.2. Non-Express
8.3. Market Analysis, Insights and Forecast - by Business Model
8.3.1. B2B
8.3.2. B2C
8.3.3. C2C
8.4. Market Analysis, Insights and Forecast - by Shipment Weight
8.4.1. Heavy Weight
8.4.2. Light Weight
8.4.3. Medium Weight
8.5. Market Analysis, Insights and Forecast - by Mode of Transport
8.5.1. Air
8.5.2. Road
8.5.3. Others
8.6. Market Analysis, Insights and Forecast - by End-User Industry
8.6.1. E-Commerce
8.6.2. BFSI
8.6.3. Healthcare
8.6.4. Manufacturing
8.6.5. Primary Industry
8.6.6. Wholesale and Retail Trade
8.6.6.1. Offline
8.6.7. Others
9. Gelderland & Utrecht Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Destination
9.1.1. Domestic
9.1.2. International
9.2. Market Analysis, Insights and Forecast - by Speed of Delivery
9.2.1. Express
9.2.2. Non-Express
9.3. Market Analysis, Insights and Forecast - by Business Model
9.3.1. B2B
9.3.2. B2C
9.3.3. C2C
9.4. Market Analysis, Insights and Forecast - by Shipment Weight
9.4.1. Heavy Weight
9.4.2. Light Weight
9.4.3. Medium Weight
9.5. Market Analysis, Insights and Forecast - by Mode of Transport
9.5.1. Air
9.5.2. Road
9.5.3. Others
9.6. Market Analysis, Insights and Forecast - by End-User Industry
9.6.1. E-Commerce
9.6.2. BFSI
9.6.3. Healthcare
9.6.4. Manufacturing
9.6.5. Primary Industry
9.6.6. Wholesale and Retail Trade
9.6.6.1. Offline
9.6.7. Others
10. Other Provinces Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Destination
10.1.1. Domestic
10.1.2. International
10.2. Market Analysis, Insights and Forecast - by Speed of Delivery
10.2.1. Express
10.2.2. Non-Express
10.3. Market Analysis, Insights and Forecast - by Business Model
10.3.1. B2B
10.3.2. B2C
10.3.3. C2C
10.4. Market Analysis, Insights and Forecast - by Shipment Weight
10.4.1. Heavy Weight
10.4.2. Light Weight
10.4.3. Medium Weight
10.5. Market Analysis, Insights and Forecast - by Mode of Transport
10.5.1. Air
10.5.2. Road
10.5.3. Others
10.6. Market Analysis, Insights and Forecast - by End-User Industry
10.6.1. E-Commerce
10.6.2. BFSI
10.6.3. Healthcare
10.6.4. Manufacturing
10.6.5. Primary Industry
10.6.6. Wholesale and Retail Trade
10.6.6.1. Offline
10.6.7. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Bpost Group (including DynaGroup)
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. DHL Group
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. FedEx
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. GEODIS
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Instabee
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. La Poste Group
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Logista
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Post NL
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. United Parcel Service of America Inc. (UPS)
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Netherlands Courier, Express, and Parcel (CEP) Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Destination 2026 & 2034
Figure 3: North Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Destination 2026 & 2034
Figure 4: North Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Speed of Delivery 2026 & 2034
Figure 5: North Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Speed of Delivery 2026 & 2034
Figure 6: North Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Business Model 2026 & 2034
Figure 7: North Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Business Model 2026 & 2034
Figure 8: North Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Shipment Weight 2026 & 2034
Figure 9: North Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Shipment Weight 2026 & 2034
Figure 10: North Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Mode of Transport 2026 & 2034
Figure 11: North Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Mode of Transport 2026 & 2034
Figure 12: North Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 13: North Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 14: North Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Country 2026 & 2034
Figure 16: South Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Destination 2026 & 2034
Figure 17: South Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Destination 2026 & 2034
Figure 18: South Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Speed of Delivery 2026 & 2034
Figure 19: South Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Speed of Delivery 2026 & 2034
Figure 20: South Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Business Model 2026 & 2034
Figure 21: South Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Business Model 2026 & 2034
Figure 22: South Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Shipment Weight 2026 & 2034
Figure 23: South Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Shipment Weight 2026 & 2034
Figure 24: South Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Mode of Transport 2026 & 2034
Figure 25: South Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Mode of Transport 2026 & 2034
Figure 26: South Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 27: South Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 28: South Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Country 2026 & 2034
Figure 29: South Holland Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Country 2026 & 2034
Figure 30: North Brabant Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Destination 2026 & 2034
Figure 31: North Brabant Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Destination 2026 & 2034
Figure 32: North Brabant Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Speed of Delivery 2026 & 2034
Figure 33: North Brabant Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Speed of Delivery 2026 & 2034
Figure 34: North Brabant Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Business Model 2026 & 2034
Figure 35: North Brabant Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Business Model 2026 & 2034
Figure 36: North Brabant Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Shipment Weight 2026 & 2034
Figure 37: North Brabant Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Shipment Weight 2026 & 2034
Figure 38: North Brabant Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Mode of Transport 2026 & 2034
Figure 39: North Brabant Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Mode of Transport 2026 & 2034
Figure 40: North Brabant Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 41: North Brabant Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 42: North Brabant Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Country 2026 & 2034
Figure 43: North Brabant Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Country 2026 & 2034
Figure 44: Gelderland & Utrecht Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Destination 2026 & 2034
Figure 45: Gelderland & Utrecht Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Destination 2026 & 2034
Figure 46: Gelderland & Utrecht Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Speed of Delivery 2026 & 2034
Figure 47: Gelderland & Utrecht Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Speed of Delivery 2026 & 2034
Figure 48: Gelderland & Utrecht Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Business Model 2026 & 2034
Figure 49: Gelderland & Utrecht Netherlands Courier, Express, and Parcel (CEP) Market Revenue Share (%), by Business Model 2026 & 2034
Figure 50: Gelderland & Utrecht Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion), by Shipment Weight 2026 & 2034
Table 39: Gelderland & Utrecht Netherlands Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Mode of Transport 2020 & 2034
Table 40: Gelderland & Utrecht Netherlands Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 41: Gelderland & Utrecht Netherlands Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Country 2020 & 2034
Table 42: Other Provinces Netherlands Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Destination 2020 & 2034
Table 43: Other Provinces Netherlands Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Speed of Delivery 2020 & 2034
Table 44: Other Provinces Netherlands Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Business Model 2020 & 2034
Table 45: Other Provinces Netherlands Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Shipment Weight 2020 & 2034
Table 46: Other Provinces Netherlands Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Mode of Transport 2020 & 2034
Table 47: Other Provinces Netherlands Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 48: Other Provinces Netherlands Courier, Express, and Parcel (CEP) Market Revenue Billion Forecast, by Country 2020 & 2034
Table 49: Limburg Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 50: Groningen Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 51: Friesland Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 52: Drenthe Netherlands Courier, Express, and Parcel (CEP) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the size of the Netherlands Courier, Express, and Parcel (CEP) market?
The Netherlands CEP market is estimated at USD 9.55 billion in 2025 and is projected to reach USD 12.12 billion by 2030, expanding at a CAGR of 4.88%. This growth outpaces the broader European CEP market, which is forecast at a 3.57% CAGR over a comparable horizon.
2Which companies dominate the Dutch CEP market?
The market is moderately consolidated, with DHL Group, FedEx, La Poste Group, PostNL, and UPS as the leading players. PostNL holds roughly 20% of domestic postal and parcel services, while UPS commands approximately 45% of cross-border parcel transport in the Netherlands, followed by DPD at 15%.
3What is driving growth in the Netherlands courier and parcel market?
Primary growth drivers include e-commerce expansion — Dutch consumers spent about USD 34.65 billion online, generating roughly 373 million purchases — plus EU customs simplification that cuts compliant transit times by 30–40%, out-of-home locker proliferation at EUR 1.50 per parcel, and an USD 8 billion national transport infrastructure investment plan to 2030.
4Which segment is expected to grow fastest in the Dutch CEP market?
Healthcare is the quickest-growing end-user vertical at a 5.41% CAGR, while C2C volumes expand fastest by business model at 5.43% CAGR. Express shipments and heavy-weight consignments also outpace the market at 4.24% and 4.40% CAGRs respectively, and international air freight grows at 5.12%.
5Why is the Netherlands considered a logistics gateway for European CEP flows?
Merchandise trade equals 165.91% of Dutch GDP, with exports of USD 705.17 billion and imports of USD 632.28 billion recorded in 2023. The country maintains 233 export partners and 224 import partners with a highly diversified market concentration index of 0.08, supported by Rotterdam's maritime throughput and Schiphol's air cargo capacity.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Approximately 70–80% of the total research effort for this report was derived from primary research, including structured interviews, C-level briefings, and operational data exchanges.
Interviewed company types across the Dutch CEP value chain include: integrated express network operators and national postal carriers, regional parcel consolidators and last-mile delivery firms, automated locker and out-of-home delivery infrastructure providers, e-commerce fulfillment and micro-fulfillment center operators, and customs brokerage and multi-carrier shipping software vendors.
Stakeholder job titles interviewed: Chief Operating Officer / Head of Network Operations, Procurement and Carrier Sourcing Director, Head of Last-Mile and Out-of-Home Strategy, and Customs and Trade Compliance Manager.
Consulted regulatory and industry bodies: Autoriteit Consument & Markt (ACM) for postal regulation, Douane Nederland (Dutch Customs Administration) for cross-border clearance frameworks, European Commission Directorate-General for Taxation and Customs Union (DG TAXUD) for ICS2 and EU Customs Data Hub rules, and Ecommerce Europe for parcel-volume benchmarking.
Primary fieldwork covered shipper-side interviews with e-commerce merchants, healthcare distributors, and manufacturing exporters to validate demand-side parcel volumes and service-level requirements.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Operating Officer / Head of Network Operations
Approximately 20–30% of the effort relied on secondary validation using official multilateral and governmental sources, including UN Comtrade for Dutch bilateral trade flows, World Bank WITS for trade indicators and market concentration metrics, Eurostat for postal and courier activity statistics, and CBS (Statistics Netherlands) for enterprise counts and e-commerce expenditure data.
Financial and corporate disclosures were sourced from standardized databases including Bloomberg, Factiva, Hoovers, and PitchBook, alongside annual reports and investor presentations of publicly listed carriers.
Official regulatory publications from ACM, Douane Nederland, and DG TAXUD were used to validate compliance timelines and customs reform impacts.
Trade association and non-profit technical benchmarks from Ecommerce Europe and IPC (International Post Corporation) informed cross-border parcel volume and delivery-quality baselines.
Demand Modeling & Market Estimation
A simultaneous top-down and bottom-up methodology was applied. The top-down approach anchored Dutch market value to European CEP aggregates and the Netherlands' observed share, while the bottom-up approach constructed market size from granular operating metrics.
Quantitative bottom-up metrics included: annual Dutch parcel volume (domestic plus cross-border), average realized revenue per parcel by service tier, out-of-home delivery point density per 100,000 urban residents, and e-commerce expenditure converted to parcel-equivalent shipments.
Carrier-level revenue was decomposed by destination, speed of delivery, business model, shipment weight, mode of transport, and end-user industry, then cross-validated against reported enterprise counts of approximately 10,070 firms in postal and courier activities.
Multi-level data triangulation reconciled variances between primary interview estimates, official trade statistics, and carrier financial disclosures, with residual gaps resolved through analyst judgment documented in the model audit log.
Data Accuracy & Quality Check
The report carries a guaranteed estimated data accuracy level of 85–90%, benchmarked against post-publication actuals and reappraised quarterly.
All figures undergo multi-level data triangulation across at least three independent source classes before inclusion.
Every report is updated to the date of purchase, incorporating the latest available customs reform timelines, fuel-duty adjustments, carrier capacity announcements, and infrastructure investment decisions.
Sensitivity testing was performed on fuel-price, wage-inflation, and parcel-volume assumptions to establish confidence intervals around headline CAGR and valuation figures.