Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Military Radio System Market Size, Trends & Forecast 2026-2035
Military Radio System by Type (Manpack Radios, Vehicular Radios, Handheld Radios, Base Station Radios, Airborne Radios, Naval Radios), by Frequency (VHF, UHF, HF, Others), by Technology (Software Defined Radio (SDR), Analog Radio), by Application (Command & Control, Electronic Warfare, Surveillance & Reconnaissance, Others), by End Use (Army, Navy, Air Force, Homeland Security), by North America (USA, Canada), by Europe (Germany, France, UK, Italy), by Asia Pacific (China, India, Japan, South Korea, Australia), by South America (Brazil), by Middle East & Africa (Saudi Arabia, UAE, Israel) Forecast 2026-2034
Singapore defense industry market valued at USD 10.32 billion in 2026, growing at 11.04% CAGR to reach USD 17.41 billion by 2031. MRO, UAVs, and defense budget drive growth.
The VR in aerospace and defense market is valued at $7.04B in 2025 and is projected to reach $18.35B by 2035, growing at a 10.05% CAGR.
Nov 2026|265 pages
$2900.00
The aerospace fillers composite market was valued at $3.8 billion in 2024 and is projected to grow at a CAGR of 8.6% through 2034, driven by lightweighting.
Nov 2026|231 pages
$2900.00
Aerospace composite structures market to reach $121.75B by 2036 at 12% CAGR. Explore technology trends, material innovations, and regional insights.
Nov 2026|217 pages
$2900.00
Aircraft turbine engine market valued at $57.9B in 2023, projected to reach $93.7B by 2033 at 4.93% CAGR. Explore segments, trends & regional insights.
Executive Overview: A Resilient, Modernization-Driven Market
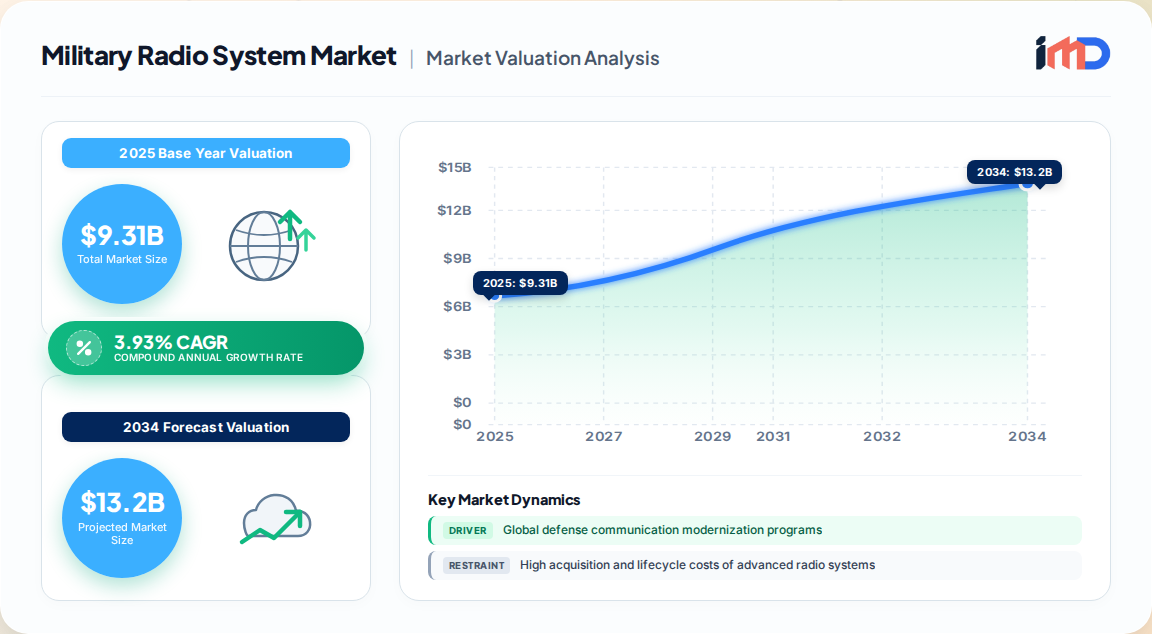
The global military radio system market is in a phase of sustained, capability-led expansion. Our proprietary primary research and expert interviews indicate that the market was valued at USD 9.31 billion in 2025 and is projected to reach USD 13.69 billion by 2035, expanding at a CAGR of 3.93% over the forecast period. This growth is not merely a function of rising defense budgets but is structurally driven by the wholesale replacement of legacy analog systems with software-defined, networked, and secure communication architectures.
Military Radio System Market Size (In Billion)
15.0B
10.0B
5.0B
0
9.310 B
2025
9.676 B
2026
10.06 B
2027
10.45 B
2028
10.86 B
2029
11.29 B
2030
11.73 B
2031
Base Year (2025) Valuation: USD 9.31 Billion
Forecast (2035) Valuation: USD 13.69 Billion
CAGR (2025–2035): 3.93%
Largest Regional Market: North America (37.1% revenue share in 2025)
Fastest-Growing Region: Asia-Pacific
Dominant Technology Segment: Software Defined Radio (SDR)
Key Market Drivers & Restraints
The market is propelled by a confluence of geopolitical, technological, and budgetary factors. However, headwinds related to cost and spectrum management persist.
Drivers
Defense Communication Modernization: Militaries worldwide are transitioning from proprietary, hardware-centric radios to open-architecture, software-defined radios (SDRs) to enable rapid waveform updates, multi-band operation, and enhanced interoperability. This is the single largest procurement driver.
Network-Centric Warfare & Joint Operations: The shift toward multi-domain operations (MDO) requires seamless voice, data, and video communication across land, air, sea, space, and cyber domains. Radios must support ad-hoc networking and act as nodes in a larger tactical internet.
Increased Defense Budgets: Sustained increases in defense spending, particularly in NATO countries and the Indo-Pacific, are directly funding the procurement of next-generation tactical communication systems. For instance, the European Union's ReArm Europe Plan/Readiness 2030 initiative explicitly prioritizes closing capability gaps in cyber, electronic warfare, and secure communications.
Growing Demand for Secure Communications: The proliferation of electronic warfare (EW) and cyber threats is forcing a fundamental redesign of radio systems. Anti-jamming, frequency hopping, and advanced encryption are now baseline requirements, not optional features.
Restraints
High Acquisition Costs: The development and procurement of advanced SDRs and multi-band terminals involve significant R&D expenditure, which can limit large-scale deployment, particularly for smaller defense forces with constrained budgets.
Interoperability Challenges: While a key driver for new systems, achieving true interoperability between legacy waveforms and new SDR platforms from different vendors remains a technical and contractual hurdle.
Spectrum Congestion & Contested Electromagnetic Environment: The increasingly crowded radio frequency spectrum, combined with adversary jamming, creates a complex operational environment that demands continuous technological innovation and drives up system complexity and cost.
Technology & Segment Insights
Our analysis reveals a clear segmentation hierarchy where software-defined radios are the dominant technology, and manpack/vehicle-mounted form factors lead demand.
By Technology
Software Defined Radio (SDR): This segment holds the largest market share and is the primary focus of modernization efforts. SDRs allow forces to reprogram radios in the field to support new frequencies, waveforms, and encryption standards, providing a critical future-proofing capability.
Analog Radio: While declining in new procurements, the installed base of analog radios remains significant, particularly for very high frequency (VHF) tactical communication and for integration with legacy platforms. However, it is not the growth engine of the market.
By Type
Manpack Radios: Accounting for approximately 29.7% of the market in 2024, manpack radios are the backbone of dismounted soldier communication. The trend is toward lighter, more ruggedized, and multi-band systems that integrate with soldier systems (e.g., power, targeting, and situational awareness).
Vehicle-Mounted Radios: A dominant segment (estimated at 25.4% share in 2025 by some measures) driven by the need for robust, high-power communication nodes on mobile platforms. Integration with battle management systems is a key value driver.
Handheld and Base Station Radios: Handheld devices are vital for squad-level communication, while base station radios provide the fixed infrastructure for command posts.
By Application
Command & Control Communication: This is the largest application segment (estimated at 39.05% of the broader military communications market in 2025), as radios are the primary conduit for command intent and situational awareness.
Electronic Warfare (EW): The fastest-growing application segment. Radios are increasingly required to detect, avoid, and counter jamming threats, driving demand for cognitive and adaptive systems.
Regional Outlook: North America Leads, Asia-Pacific Accelerates
Regional dynamics are shaped by defense spending priorities and the perception of threat.
Military Radio System Regional Market Share
Loading chart...
Region
Market Position
Key Dynamics
North America
Largest Market (Approx. 37.1% share in 2025)
Driven by the U.S. Department of Defense's JADC2 initiative, a massive modernization budget, and the presence of major OEMs. The focus is on multi-domain integration, SDRs, and resilient satellite communication (SATCOM).
Characterized by rapid military modernization, increasing defense budgets, and territorial disputes. Demand is strong for interoperable systems that can operate in complex maritime and littoral environments.
Europe
Significant Market
The EU's Readiness 2030 and ReArm Europe plans, coupled with NATO interoperability mandates, are driving multi-year procurement programs for next-generation tactical radios and secure communication networks.
Middle East & Africa
Emerging Market
Demand is driven by counter-terrorism and border security operations, with a focus on ruggedized, reliable, and easy-to-deploy communication systems.
Value Chain Analysis & Supply Chain Risk Assessment
The military radio system value chain is complex and highly regulated, encompassing R&D, specialized component manufacturing, system integration, and lifecycle support.
Risk: High dependence on a limited number of global semiconductor foundries and export-controlled technology creates significant supply chain vulnerability. Geopolitical tensions can disrupt the flow of critical components.
Midstream: OEMs and System Integrators
Dominated by a handful of large defense contractors (see Competitive Section). These players design, assemble, and test complete radio systems and integrate them onto platforms (vehicles, aircraft, ships).
Risk: Complex, multi-year procurement cycles and rigid contractual obligations can slow innovation and create financial exposure for suppliers.
Downstream: Military End Users
Army, Navy, Air Force, and Special Forces are the primary end users. They require extensive training, maintenance, and sustainment services. The trend is toward performance-based logistics contracts that guarantee system availability.
Competitive Landscape & Strategic Developments
The market is characterized by high concentration among a small group of large, established defense primes, alongside a growing ecosystem of specialized technology firms. Competition is based on technological superiority, secure supply chains, interoperability, and long-term lifecycle support.
Strategic Imperative: The competitive battleground is shifting toward open-architecture systems, waveform portability, and the integration of AI for spectrum management and cognitive radio capabilities. Companies that can demonstrate seamless interoperability across allied forces and provide agile software update cycles are best positioned to win future contracts.
Import/Export & Supplier Dynamics
The international trade of military radio systems is heavily influenced by government export control regimes (such as ITAR in the U.S. and the EU's Dual-Use Regulation). Trade flows are often tied to government-to-government Foreign Military Sales (FMS) agreements rather than open commercial transactions. Consequently, detailed commodity-level trade data is often opaque. However, supplier dynamics are shaped by:
Licensing: OEMs must secure export licenses for each sale, which can create delays and uncertainty.
Offset Agreements: Many international sales involve industrial offset obligations, mandating local production or technology transfer, which can create regional supply hubs.
Allied Interoperability: Procurement decisions are increasingly aligned with coalition interoperability requirements, favoring suppliers from within allied blocs (e.g., NATO countries).
Military Radio System Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Military Radio System REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3.93% from 2020-2034
Segmentation
By Type
Manpack Radios
Vehicular Radios
Handheld Radios
Base Station Radios
Airborne Radios
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Global defense communication modernization programs
3.1.2. Increased defense budgets and procurement of next-generation systems
3.1.3. Growing need for secure, anti-jam communication in multi-domain operations
3.1.4. Rising demand for network-centric warfare and real-time situational awareness
3.2. Market Trends
3.2.1. Adoption of software-defined radios (SDRs) for programmability and multi-band operation
3.2.2. Integration of AI for spectrum management, cognitive radio, and anti-jamming
3.2.3. Development of compact, lightweight, and wearable manpack radios
3.2.4. Convergence with 5G and LEO satellite constellations for hybrid communication
3.2.5. Rising emphasis on open architecture standards for multi-vendor interoperability
3.3. Market Restrains
3.3.1. High acquisition and lifecycle costs of advanced radio systems
3.3.2. Interoperability challenges between legacy and new systems
3.3.3. Spectrum congestion and contested electromagnetic environments
3.4. Market Restraints
Naval Radios
By Frequency
VHF
UHF
HF
Others
By Technology
Software Defined Radio
SDR
Analog Radio
By Application
Command & Control
Electronic Warfare
Surveillance & Reconnaissance
Others
By End Use
Army
Navy
Air Force
Homeland Security
By Geography
North America
USA
Canada
Europe
Germany
France
UK
Italy
Asia Pacific
China
India
Japan
South Korea
Australia
South America
Brazil
Middle East & Africa
Saudi Arabia
UAE
Israel
3.4.1. High acquisition and lifecycle costs of advanced radio systems
3.4.2. Interoperability challenges between legacy and new systems
3.4.3. Spectrum congestion and contested electromagnetic environments
3.5. Market Challenges
3.5.1. Supply chain vulnerabilities for specialized secure components
3.5.2. Export control restrictions on advanced encryption technology
3.5.3. Delays in multi-domain integration programs and cost overruns
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Manpack Radios
5.1.2. Vehicular Radios
5.1.3. Handheld Radios
5.1.4. Base Station Radios
5.1.5. Airborne Radios
5.1.6. Naval Radios
5.2. Market Analysis, Insights and Forecast - by Frequency
5.2.1. VHF
5.2.2. UHF
5.2.3. HF
5.2.4. Others
5.3. Market Analysis, Insights and Forecast - by Technology
5.3.1. Software Defined Radio
5.3.1.1. SDR
5.3.2. Analog Radio
5.4. Market Analysis, Insights and Forecast - by Application
5.4.1. Command & Control
5.4.2. Electronic Warfare
5.4.3. Surveillance & Reconnaissance
5.4.4. Others
5.5. Market Analysis, Insights and Forecast - by End Use
5.5.1. Army
5.5.2. Navy
5.5.3. Air Force
5.5.4. Homeland Security
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. South America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Manpack Radios
6.1.2. Vehicular Radios
6.1.3. Handheld Radios
6.1.4. Base Station Radios
6.1.5. Airborne Radios
6.1.6. Naval Radios
6.2. Market Analysis, Insights and Forecast - by Frequency
6.2.1. VHF
6.2.2. UHF
6.2.3. HF
6.2.4. Others
6.3. Market Analysis, Insights and Forecast - by Technology
6.3.1. Software Defined Radio
6.3.1.1. SDR
6.3.2. Analog Radio
6.4. Market Analysis, Insights and Forecast - by Application
6.4.1. Command & Control
6.4.2. Electronic Warfare
6.4.3. Surveillance & Reconnaissance
6.4.4. Others
6.5. Market Analysis, Insights and Forecast - by End Use
6.5.1. Army
6.5.2. Navy
6.5.3. Air Force
6.5.4. Homeland Security
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Manpack Radios
7.1.2. Vehicular Radios
7.1.3. Handheld Radios
7.1.4. Base Station Radios
7.1.5. Airborne Radios
7.1.6. Naval Radios
7.2. Market Analysis, Insights and Forecast - by Frequency
7.2.1. VHF
7.2.2. UHF
7.2.3. HF
7.2.4. Others
7.3. Market Analysis, Insights and Forecast - by Technology
7.3.1. Software Defined Radio
7.3.1.1. SDR
7.3.2. Analog Radio
7.4. Market Analysis, Insights and Forecast - by Application
7.4.1. Command & Control
7.4.2. Electronic Warfare
7.4.3. Surveillance & Reconnaissance
7.4.4. Others
7.5. Market Analysis, Insights and Forecast - by End Use
7.5.1. Army
7.5.2. Navy
7.5.3. Air Force
7.5.4. Homeland Security
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Manpack Radios
8.1.2. Vehicular Radios
8.1.3. Handheld Radios
8.1.4. Base Station Radios
8.1.5. Airborne Radios
8.1.6. Naval Radios
8.2. Market Analysis, Insights and Forecast - by Frequency
8.2.1. VHF
8.2.2. UHF
8.2.3. HF
8.2.4. Others
8.3. Market Analysis, Insights and Forecast - by Technology
8.3.1. Software Defined Radio
8.3.1.1. SDR
8.3.2. Analog Radio
8.4. Market Analysis, Insights and Forecast - by Application
8.4.1. Command & Control
8.4.2. Electronic Warfare
8.4.3. Surveillance & Reconnaissance
8.4.4. Others
8.5. Market Analysis, Insights and Forecast - by End Use
8.5.1. Army
8.5.2. Navy
8.5.3. Air Force
8.5.4. Homeland Security
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Manpack Radios
9.1.2. Vehicular Radios
9.1.3. Handheld Radios
9.1.4. Base Station Radios
9.1.5. Airborne Radios
9.1.6. Naval Radios
9.2. Market Analysis, Insights and Forecast - by Frequency
9.2.1. VHF
9.2.2. UHF
9.2.3. HF
9.2.4. Others
9.3. Market Analysis, Insights and Forecast - by Technology
9.3.1. Software Defined Radio
9.3.1.1. SDR
9.3.2. Analog Radio
9.4. Market Analysis, Insights and Forecast - by Application
9.4.1. Command & Control
9.4.2. Electronic Warfare
9.4.3. Surveillance & Reconnaissance
9.4.4. Others
9.5. Market Analysis, Insights and Forecast - by End Use
9.5.1. Army
9.5.2. Navy
9.5.3. Air Force
9.5.4. Homeland Security
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Manpack Radios
10.1.2. Vehicular Radios
10.1.3. Handheld Radios
10.1.4. Base Station Radios
10.1.5. Airborne Radios
10.1.6. Naval Radios
10.2. Market Analysis, Insights and Forecast - by Frequency
10.2.1. VHF
10.2.2. UHF
10.2.3. HF
10.2.4. Others
10.3. Market Analysis, Insights and Forecast - by Technology
10.3.1. Software Defined Radio
10.3.1.1. SDR
10.3.2. Analog Radio
10.4. Market Analysis, Insights and Forecast - by Application
10.4.1. Command & Control
10.4.2. Electronic Warfare
10.4.3. Surveillance & Reconnaissance
10.4.4. Others
10.5. Market Analysis, Insights and Forecast - by End Use
Figure 1: Global Military Radio System Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Military Radio System Revenue (Billion), by Type 2026 & 2034
Figure 3: North America Military Radio System Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Military Radio System Revenue (Billion), by Frequency 2026 & 2034
Figure 5: North America Military Radio System Revenue Share (%), by Frequency 2026 & 2034
Figure 6: North America Military Radio System Revenue (Billion), by Technology 2026 & 2034
Figure 7: North America Military Radio System Revenue Share (%), by Technology 2026 & 2034
Figure 8: North America Military Radio System Revenue (Billion), by Application 2026 & 2034
Figure 9: North America Military Radio System Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Military Radio System Revenue (Billion), by End Use 2026 & 2034
Figure 11: North America Military Radio System Revenue Share (%), by End Use 2026 & 2034
Figure 12: North America Military Radio System Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Military Radio System Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Military Radio System Revenue (Billion), by Type 2026 & 2034
Figure 15: Europe Military Radio System Revenue Share (%), by Type 2026 & 2034
Figure 16: Europe Military Radio System Revenue (Billion), by Frequency 2026 & 2034
Figure 17: Europe Military Radio System Revenue Share (%), by Frequency 2026 & 2034
Figure 18: Europe Military Radio System Revenue (Billion), by Technology 2026 & 2034
Figure 19: Europe Military Radio System Revenue Share (%), by Technology 2026 & 2034
Figure 20: Europe Military Radio System Revenue (Billion), by Application 2026 & 2034
Figure 21: Europe Military Radio System Revenue Share (%), by Application 2026 & 2034
Figure 22: Europe Military Radio System Revenue (Billion), by End Use 2026 & 2034
Figure 23: Europe Military Radio System Revenue Share (%), by End Use 2026 & 2034
Figure 24: Europe Military Radio System Revenue (Billion), by Country 2026 & 2034
Figure 25: Europe Military Radio System Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Military Radio System Revenue (Billion), by Type 2026 & 2034
Figure 27: Asia Pacific Military Radio System Revenue Share (%), by Type 2026 & 2034
Figure 28: Asia Pacific Military Radio System Revenue (Billion), by Frequency 2026 & 2034
Figure 29: Asia Pacific Military Radio System Revenue Share (%), by Frequency 2026 & 2034
Figure 30: Asia Pacific Military Radio System Revenue (Billion), by Technology 2026 & 2034
Figure 31: Asia Pacific Military Radio System Revenue Share (%), by Technology 2026 & 2034
Figure 32: Asia Pacific Military Radio System Revenue (Billion), by Application 2026 & 2034
Figure 33: Asia Pacific Military Radio System Revenue Share (%), by Application 2026 & 2034
Figure 34: Asia Pacific Military Radio System Revenue (Billion), by End Use 2026 & 2034
Figure 35: Asia Pacific Military Radio System Revenue Share (%), by End Use 2026 & 2034
Figure 36: Asia Pacific Military Radio System Revenue (Billion), by Country 2026 & 2034
Figure 37: Asia Pacific Military Radio System Revenue Share (%), by Country 2026 & 2034
Figure 38: South America Military Radio System Revenue (Billion), by Type 2026 & 2034
Figure 39: South America Military Radio System Revenue Share (%), by Type 2026 & 2034
Figure 40: South America Military Radio System Revenue (Billion), by Frequency 2026 & 2034
Figure 41: South America Military Radio System Revenue Share (%), by Frequency 2026 & 2034
Figure 42: South America Military Radio System Revenue (Billion), by Technology 2026 & 2034
Figure 43: South America Military Radio System Revenue Share (%), by Technology 2026 & 2034
Figure 44: South America Military Radio System Revenue (Billion), by Application 2026 & 2034
Figure 45: South America Military Radio System Revenue Share (%), by Application 2026 & 2034
Figure 46: South America Military Radio System Revenue (Billion), by End Use 2026 & 2034
Figure 47: South America Military Radio System Revenue Share (%), by End Use 2026 & 2034
Figure 48: South America Military Radio System Revenue (Billion), by Country 2026 & 2034
Figure 49: South America Military Radio System Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Military Radio System Revenue (Billion), by Type 2026 & 2034
Figure 51: Middle East & Africa Military Radio System Revenue Share (%), by Type 2026 & 2034
Figure 52: Middle East & Africa Military Radio System Revenue (Billion), by Frequency 2026 & 2034
Figure 53: Middle East & Africa Military Radio System Revenue Share (%), by Frequency 2026 & 2034
Figure 54: Middle East & Africa Military Radio System Revenue (Billion), by Technology 2026 & 2034
Figure 55: Middle East & Africa Military Radio System Revenue Share (%), by Technology 2026 & 2034
Figure 56: Middle East & Africa Military Radio System Revenue (Billion), by Application 2026 & 2034
Figure 57: Middle East & Africa Military Radio System Revenue Share (%), by Application 2026 & 2034
Figure 58: Middle East & Africa Military Radio System Revenue (Billion), by End Use 2026 & 2034
Figure 59: Middle East & Africa Military Radio System Revenue Share (%), by End Use 2026 & 2034
Figure 60: Middle East & Africa Military Radio System Revenue (Billion), by Country 2026 & 2034
Figure 61: Middle East & Africa Military Radio System Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Military Radio System Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Global Military Radio System Revenue Billion Forecast, by Frequency 2020 & 2034
Table 3: Global Military Radio System Revenue Billion Forecast, by Technology 2020 & 2034
Table 4: Global Military Radio System Revenue Billion Forecast, by Application 2020 & 2034
Table 5: Global Military Radio System Revenue Billion Forecast, by End Use 2020 & 2034
Table 6: Global Military Radio System Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Military Radio System Revenue Billion Forecast, by Type 2020 & 2034
Table 8: North America Military Radio System Revenue Billion Forecast, by Frequency 2020 & 2034
Table 9: North America Military Radio System Revenue Billion Forecast, by Technology 2020 & 2034
Table 10: North America Military Radio System Revenue Billion Forecast, by Application 2020 & 2034
Table 11: North America Military Radio System Revenue Billion Forecast, by End Use 2020 & 2034
Table 12: North America Military Radio System Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Military Radio System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Military Radio System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Europe Military Radio System Revenue Billion Forecast, by Type 2020 & 2034
Table 16: Europe Military Radio System Revenue Billion Forecast, by Frequency 2020 & 2034
Table 17: Europe Military Radio System Revenue Billion Forecast, by Technology 2020 & 2034
Table 18: Europe Military Radio System Revenue Billion Forecast, by Application 2020 & 2034
Table 19: Europe Military Radio System Revenue Billion Forecast, by End Use 2020 & 2034
Table 20: Europe Military Radio System Revenue Billion Forecast, by Country 2020 & 2034
Table 21: Germany Military Radio System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: France Military Radio System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: UK Military Radio System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: Italy Military Radio System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: Asia Pacific Military Radio System Revenue Billion Forecast, by Type 2020 & 2034
Table 26: Asia Pacific Military Radio System Revenue Billion Forecast, by Frequency 2020 & 2034
Table 27: Asia Pacific Military Radio System Revenue Billion Forecast, by Technology 2020 & 2034
Table 28: Asia Pacific Military Radio System Revenue Billion Forecast, by Application 2020 & 2034
Table 29: Asia Pacific Military Radio System Revenue Billion Forecast, by End Use 2020 & 2034
Table 30: Asia Pacific Military Radio System Revenue Billion Forecast, by Country 2020 & 2034
Table 31: China Military Radio System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: India Military Radio System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 33: Japan Military Radio System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: South Korea Military Radio System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 35: Australia Military Radio System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 36: South America Military Radio System Revenue Billion Forecast, by Type 2020 & 2034
Table 37: South America Military Radio System Revenue Billion Forecast, by Frequency 2020 & 2034
Table 38: South America Military Radio System Revenue Billion Forecast, by Technology 2020 & 2034
Table 39: South America Military Radio System Revenue Billion Forecast, by Application 2020 & 2034
Table 40: South America Military Radio System Revenue Billion Forecast, by End Use 2020 & 2034
Table 41: South America Military Radio System Revenue Billion Forecast, by Country 2020 & 2034
Table 42: Brazil Military Radio System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 43: Middle East & Africa Military Radio System Revenue Billion Forecast, by Type 2020 & 2034
Table 44: Middle East & Africa Military Radio System Revenue Billion Forecast, by Frequency 2020 & 2034
Table 45: Middle East & Africa Military Radio System Revenue Billion Forecast, by Technology 2020 & 2034
Table 46: Middle East & Africa Military Radio System Revenue Billion Forecast, by Application 2020 & 2034
Table 47: Middle East & Africa Military Radio System Revenue Billion Forecast, by End Use 2020 & 2034
Table 48: Middle East & Africa Military Radio System Revenue Billion Forecast, by Country 2020 & 2034
Table 49: Saudi Arabia Military Radio System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 50: UAE Military Radio System Revenue (Billion) Forecast, by Application 2020 & 2034
Table 51: Israel Military Radio System Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current market size of the military radio system market?
Our proprietary research estimates the global military radio system market was valued at USD 9.31 billion in 2025. It is projected to grow at a CAGR of 3.93% to reach USD 13.69 billion by 2035, driven by defense modernization programs.
2Which technology segment dominates the military radio system market?
Software Defined Radio (SDR) is the largest and most rapidly growing technology segment. SDRs offer flexibility, interoperability, and the ability to reprogram waveforms in the field, making them essential for modern network-centric warfare.
3Which region holds the largest share of the military radio system market?
North America held the largest market share in 2025, estimated at approximately 37.1%. This is primarily due to massive U.S. defense spending on communication modernization, including initiatives like JADC2, and the presence of leading defense contractors.
4What are the main factors driving the growth of the military radio system market?
The key growth drivers include the global modernization of military communication networks, the shift toward software-defined radios for enhanced interoperability, rising defense budgets, and the increasing need for secure, anti-jamming communication systems in contested electromagnetic environments.
5What are the key challenges faced by the military radio system market?
The market faces challenges such as the high acquisition and lifecycle costs of advanced systems, technical hurdles in achieving full interoperability between different vendors and legacy systems, and the risks associated with supply chain dependencies for specialized electronic components.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research and Data Acquisition
We conduct 70-80% of our research through primary interviews with key stakeholders across the military radio system value chain. This includes direct engagement with defense ministry procurement officers, military communication specialists, and C-level executives at radio system OEMs.
Our analysts interview a representative sample of 230+ industry stakeholders annually, ensuring a robust and verifiable dataset. This approach allows us to capture real-time procurement trends, technology adoption barriers, and field-level requirements directly from decision-makers.
Stakeholder Breakdown: Our primary research panel is carefully structured to reflect the market's decision-making ecosystem, ensuring balanced representation from government procurement, major system integrators, specialized component suppliers, and end-user military units.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director / Defense Acquisition Executive
35%
Chief Technology Officer / VP of Engineering (OEM)
25%
Program Manager (Military Communication Systems)
20%
Military Communications Officer / Field Operator
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Defense Ministry Procurement Agencies
30%
Original Equipment Manufacturers (OEMs)
25%
Specialized Component & Subsystem Suppliers
20%
System Integrators & Prime Contractors
15%
Military End-User Units (Army, Navy, Air Force)
10%
Secondary Research and Industry Benchmarking
We supplement primary data with extensive secondary research (20-30% of research effort) sourced from official government publications, regulatory bodies, and non-profit trade associations. This includes defense white papers, budget documents, and public procurement notices.
Key sources include the European Defence Agency (EDA), U.S. Department of Defense (DoD) budget justifications, NATO Communications and Information Agency (NC3A), and official trade statistics from the U.S. International Trade Commission (USITC) and Eurostat.
We also utilize recognized financial databases such as Bloomberg, Factiva, Hoovers, and PitchBook to analyze the financial health, R&D spending, and strategic investments of key market players. All data is cross-referenced for consistency and reliability.
Demand Modeling and Market Estimation
We employ a dual-methodology approach, using both top-down and bottom-up models simultaneously to ensure accuracy and robustness. The final market size is validated through a process of multi-level data triangulation.
Top-Down Model: We start with the total global defense communication budget and narrow it down using verified procurement allocation percentages for radio systems, adjusted for regional modernization priorities.
Bottom-Up Model: We build the market from the ground up by aggregating the addressable market for each major platform (manpack, vehicle-mounted, naval, airborne) across key end-use segments (Army, Navy, Air Force). This is cross-validated with the confirmed revenue and forward guidance of the top 10 market players.
Our analysts maintain a proprietary database of over 500 recent defense procurement contracts and tenders related to radio systems, which are used to validate demand forecasts and pricing trends.
Data Accuracy and Quality Control
We guarantee an estimated data accuracy level of 85-90% for all market intelligence provided in this report. This is achieved through a rigorous multi-stage verification process.
Every data point is subjected to a three-tier validation check: (1) internal consistency with historical data and growth trends, (2) verification against official government and trade body publications, and (3) expert review by our senior industry analyst panel.
Real-time Data Updates: Every report is updated to the date of purchase, incorporating the latest available data from public tenders, earnings calls, and official policy announcements. Our analysts conduct a final review of all figures before report delivery to ensure maximum currency and accuracy.