1What is the market size of VR in aerospace and defense in 2025?
The market is estimated at USD 7.04 billion in 2025, with projections to reach USD 18.35 billion by 2035.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Virtual Reality (VR) in Aerospace and Defense Market
 by Application (Pilot Training, Maintenance Training, Mission Simulation, Aircraft Design, Weaponry Training), by End Use (Civil Aviation, Military Aviation, Defense Operations, Space Exploration), by Technology (Software Simulation, 3D Visualization, Haptic Feedback, Cloud-Based VR), by Component (Hardware, Software, Services), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea, Australia), by South America (Brazil, Argentina), by Middle East & Africa (UAE, Saudi Arabia, Israel, South Africa) Forecast 2026-2034

Research Associate


 Related Reports

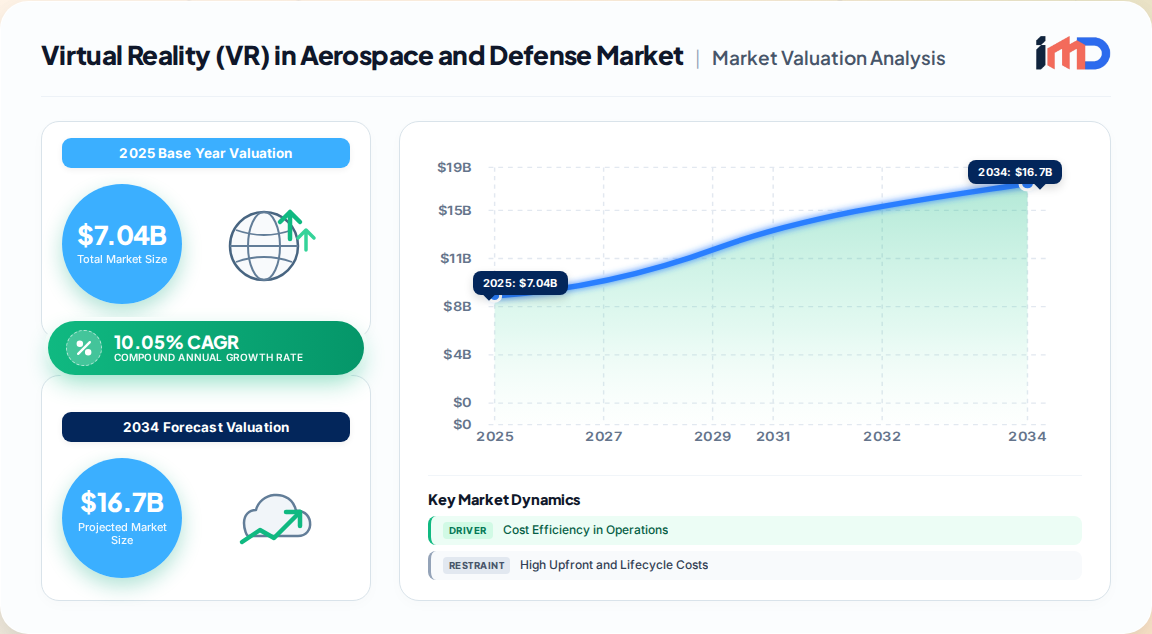
The Virtual Reality (VR) in Aerospace and Defense Market is undergoing a structural transformation, shifting from niche experimental applications to mission-critical infrastructure. Our proprietary primary research estimates the market at USD 7.04 Billion in 2025, projected to expand to USD 18.35 Billion by 2035, representing a robust CAGR of 10.05% . This growth is underpinned by a fundamental re-engineering of training, design, and operational paradigms across both civil and military aviation.
Contrary to broader VR market narratives that emphasize consumer gaming, the aerospace and defense vertical is defined by stringent certification requirements, high-fidelity simulation needs, and integration with secure command-and-control networks. The market is currently dominated by software simulation and services, which collectively account for the majority of spending, while hardware—specifically ruggedized head-mounted displays (HMDs) and haptic feedback systems—is witnessing accelerated adoption. North America remains the largest regional market, driven by multi-billion-dollar defense procurement programs and a mature aviation training ecosystem, while Asia-Pacific emerges as the fastest-growing theater due to rapid military modernization and fleet expansion.
The adoption of VR in this sector is propelled by three primary, interlinked drivers: cost efficiency, enhanced training capabilities, and integration with artificial intelligence (AI) .
Despite the compelling value proposition, the market faces significant headwinds that temper growth projections:
The VR value chain in aerospace and defense is complex and highly specialized. Hardware OEMs (e.g., Vuzix, Thales, Rheinmetall) supply HMDs, motion tracking systems, and haptic devices. Software and simulation platform providers (e.g., Lockheed Martin, CAE, BAE Systems) develop the core rendering engines, physics models, and integration middleware. System integrators and defense prime contractors (e.g., Boeing, Northrop Grumman) orchestrate these components into turnkey training and design solutions. Finally, service providers offer content creation, maintenance, and cloud hosting.
Supply chain risks are concentrated in the hardware segment, particularly for advanced optical components (waveguides, microdisplays) and semiconductors. Geopolitical tensions and export controls on high-end chips present potential bottlenecks. However, the trend toward software-defined architectures and cloud-based VR is mitigating hardware dependency, allowing for faster feature updates and reduced logistics footprint. The U.S. Department of Defense's Integrated Visual Augmentation System (IVAS) program, valued at USD 21.9 billion, exemplifies the scale of procurement and the multi-vendor strategy being adopted to ensure supply chain resilience.
Our analysis reveals that Pilot Training is the largest application segment, accounting for an estimated 45% of VR spending in 2025, due to the critical need for recurrent flight simulation. However, Maintenance Training is the fastest-growing application (CAGR >12%), driven by the increasing complexity of aircraft systems and the need for remote expert assistance.
By end-use, Civil Aviation currently holds the majority share, led by major airlines and flight training organizations investing in cost-effective simulator replacements. Military Aviation is the fastest-growing end-use segment, fueled by rising defense budgets and the integration of VR into mission rehearsal and battlefield management.
By technology, Software Simulation remains the largest segment, while Cloud-Based VR is the fastest-growing, enabling scalable, location-independent training and collaboration.
| Segment | Largest Share (2025) | Fastest Growing (CAGR 2025-2035) |
|---|---|---|
| By Application | Pilot Training (~45%) | Maintenance Training (~12%) |
| By End-Use | Civil Aviation (~55%) | Military Aviation (~11%) |
| By Technology | Software Simulation (~60%) | Cloud-Based VR (~15%) |
| By Component | Hardware (~50%) | Services (~12%) |
North America dominates the market, holding approximately 42-43% of global spending in 2025. This leadership is anchored by the U.S. defense budget, which allocates over USD 26 billion annually to simulation and training systems, and the presence of major prime contractors and technology innovators. The region also benefits from a mature aviation industry and supportive regulatory frameworks.
Europe is the second-largest market, with growth driven by NATO modernization efforts and collaborative defense projects like the Franco-German Main Ground Combat System (MGCS). The European Defence Fund is actively supporting next-generation crew training solutions, fostering regional R&D.
Asia-Pacific is the fastest-growing region, projected to grow at a CAGR of roughly 12-13% through 2035. This is fueled by double-digit increases in defense budgets (e.g., Japan's FY2025 defense budget up 10.5%), fleet expansion by airlines, and government initiatives to indigenize defense technology. The region's VR market, valued at USD 14.8 billion in 2026 for enterprise XR, highlights the broader digital transformation underway.
The market is characterized by a mix of established defense primes, specialized simulation firms, and emerging hardware innovators. Lockheed Martin, Northrop Grumman, Raytheon Technologies, Boeing, General Dynamics, and Thales Group are among the key players, leveraging their systems integration expertise and long-standing government relationships.
Recent strategic developments underscore the competitive dynamics:
| Company | Headquarters | Strategic Focus |
|---|---|---|
| Lockheed Martin | US | Integrated simulation and training systems; 5G testbeds |
| Northrop Grumman | US | Mission planning and C4ISR VR integration |
| Raytheon Technologies | US | Immersive training for missile defense and cyber |
| Boeing | US | Pilot training and aircraft design VR |
| General Dynamics | US | Ground vehicle and maintenance training |
| Thales Group | France | Avionics, HMDs, and networked simulation |
| BAE Systems | UK | Combat systems and immersive training |
| Airbus | France | Civil aviation training and design |
| Leonardo | Italy | Helicopter and defense electronics training |
Despite significant progress, several white spaces remain underpenetrated. Maintenance, Repair, and Overhaul (MRO) is a prime opportunity, as VR can provide remote expert guidance and just-in-time training, reducing platform downtime. Additionally, space exploration and unmanned aerial system (UAS) operations require specialized simulation environments that are not yet fully commoditized.
Another promising avenue is the certification of VR training by aviation authorities (FAA, EASA) for pilot licensing credits. As regulatory acceptance grows, the addressable market for VR-based pilot training will expand substantially. Finally, low-cost, lightweight VR solutions tailored for allied nations and emerging markets can unlock new demand, particularly in Asia-Pacific and Latin America, where cost sensitivity is high.
Defense and aerospace organizations are increasingly adopting software-as-a-service (SaaS) and VR-as-a-service models to shift from capital-intensive procurement to operational expenditure. This allows for continuous updates and scalability. When sourcing VR solutions, buyers prioritize security accreditation (e.g., Common Criteria, NIST), interoperability with existing simulation networks (e.g., DIS, HLA), and lifecycle support.
Multi-vendor strategies are becoming common to avoid lock-in and leverage best-of-breed components. For example, the U.S. Army's IVAS program is now open to multiple vendors, including Anduril and Palantir, reflecting a shift toward a more competitive and agile procurement ecosystem. This trend favors integrators who can demonstrate open architectures and rapid integration capabilities.
The VR in aerospace and defense market is poised for sustained, double-digit growth through 2035. Stakeholders should focus on the following strategic imperatives:
As the technology matures and costs decline, VR will become an indispensable tool for designing, training, and operating in the aerospace and defense domains, reshaping how missions are planned and executed.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.05% from 2020-2034 |
| Segmentation |
|
By End Use
By Technology
By Component
| By Geography |
|
The market is estimated at USD 7.04 billion in 2025, with projections to reach USD 18.35 billion by 2035.
The market is expected to grow at a compound annual growth rate (CAGR) of 10.05% from 2025 to 2035.
North America holds the largest market share, accounting for approximately 42-43% of global spending in 2025, driven by substantial U.S. defense budgets.
Key drivers include cost efficiency in operations, enhanced training capabilities, and integration with artificial intelligence and emerging technologies.
Major players include Lockheed Martin, Northrop Grumman, Raytheon Technologies, Boeing, General Dynamics, and Thales Group.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Program Manager | 30% |
| Chief Simulation Engineer | 30% |
| Procurement Officer | 20% |
| Defense Attaché | 20% |
| Company Type | Representation (%) |
|---|---|
| Military Training System Integrators | 35% |
| Ruggedized VR Hardware OEMs | 20% |
| Software Simulation Developers | 20% |
| Defense Prime Contractors | 15% |
| Civil Aviation Training Organizations | 10% |