1What is the market size of aerospace composite structures in 2026?
The global aerospace composite structures market is estimated at USD 39.2 billion in 2026 and is projected to reach USD 121.75 billion by 2036, growing at a CAGR of 12.0%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Aerospace Composite Structures: A Technology Perspective
 by Fiber Type (Carbon Fiber Composites, Glass Fiber Composites, Aramid Fiber Composites, Ceramic Fiber Composites), by Application (Exterior Components, Interior Components, Engine Components, Others), by Manufacturing Process (Automated Fiber Placement, Automated Tape Laying, Resin Transfer Molding, Out-of-Autoclave, Others), by Matrix Type (Polymer Matrix Composites, Metal Matrix Composites, Ceramic Matrix Composites), by Aircraft Type (Commercial Aircraft, Business & General Aviation, Military Aircraft, Helicopters, Unmanned Aerial Vehicles), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by South America (Brazil), by Middle East & Africa (UAE, Saudi Arabia) Forecast 2026-2034

Research Associate


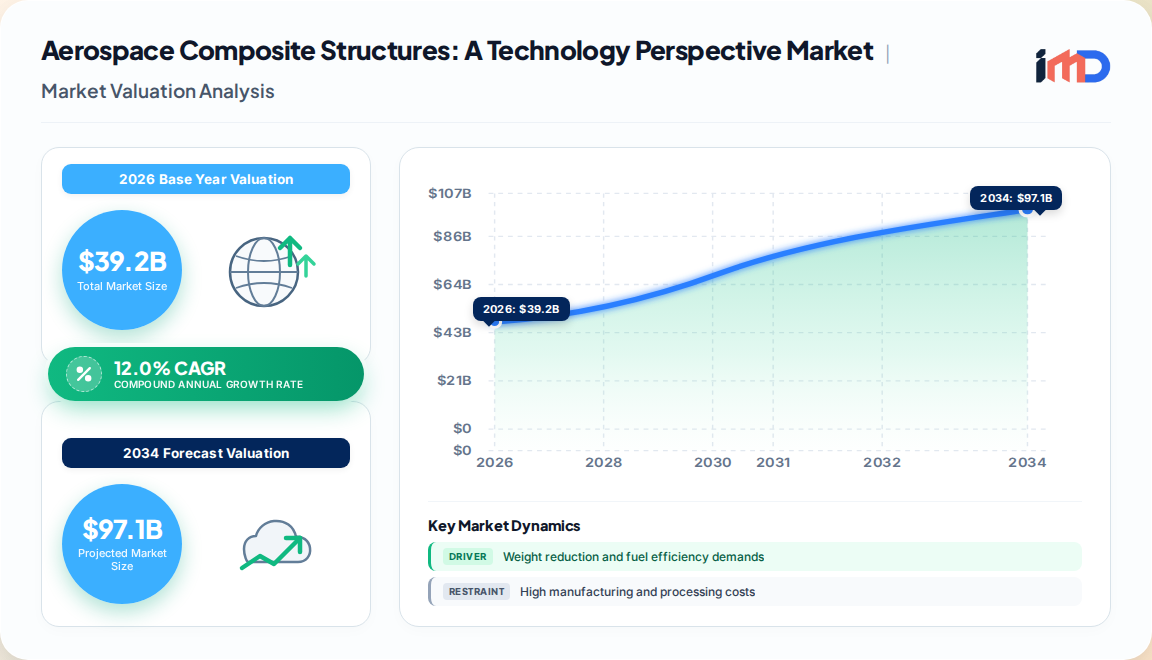
The global aerospace composite structures market is undergoing a profound transformation, driven by the relentless pursuit of weight reduction, fuel efficiency, and sustainability. Our proprietary primary research estimates the market at USD 39.2 billion in 2026, with projections indicating a surge to USD 121.75 billion by 2036, reflecting a robust 12.0% CAGR over the forecast period. This growth is not merely a function of volume; it is deeply rooted in a technology revolution that is reshaping material science, manufacturing processes, and structural design paradigms.
North America currently commands the largest share, at approximately 43%, underpinned by a mature aerospace ecosystem, substantial defense spending, and the presence of key OEMs and tier-one suppliers. However, Asia-Pacific is emerging as the fastest-growing region, propelled by expanding aviation fleets, increasing passenger traffic, and strategic investments in indigenous manufacturing capabilities.
The technology perspective is critical: composite structures are no longer just alternative materials; they are enabling technologies. From carbon fiber reinforced polymers (CFRP) with tailored fiber orientations to thermoplastic composites that offer recyclability, the market is witnessing a shift from conventional thermoset systems to advanced, automated, and sustainable solutions.
This report provides a deep dive into the technological advancements, supply chain dynamics, and strategic imperatives shaping the aerospace composite structures market. Our analysis is based on extensive primary interviews with industry stakeholders, proprietary demand models, and rigorous triangulation of trade and production data.
The aerospace composites market is propelled by a confluence of macroeconomic, regulatory, and technological forces. However, significant hurdles remain, particularly in manufacturing complexity and cost structures.
The technology landscape of aerospace composite structures is evolving rapidly, with several key trends shaping the future of the market.
| Technology Trend | Description | Impact on Market |
|---|---|---|
| Thermoplastic Composites | Offer recyclability, faster processing, and improved toughness compared to thermosets. | Expected to gain share in secondary structures and interior components; long-term potential for primary structures. |
| Automated Fiber Placement (AFP) | Robotic systems that place composite tape with high precision, reducing labor and waste. | Increasing adoption for large structures like fuselages and wings; improves production rates and consistency. |
| Out-of-Autoclave (OOA) Processing | Resin systems that cure without autoclave pressure, reducing capital costs. | Enables cost-effective production for smaller components and UAVs; expands supplier base. |
| Hybrid Composites | Combining carbon, glass, and aramid fibers to optimize cost-performance. | Emerging in specialized applications where tailored properties are required. |
| Additive Manufacturing | 3D printing of composite parts, enabling complex geometries and rapid prototyping. | Niche but growing; suitable for brackets, ducts, and replacement parts. |
The shift towards thermoplastic composites is particularly noteworthy. Their ability to be remelted and reformed offers a pathway to recycling aerospace composites, addressing a major sustainability challenge. However, the high melting temperatures and processing pressures required for high-performance thermoplastics like PEEK and PEKK necessitate significant investment in new manufacturing infrastructure.
North America remains the epicenter of aerospace composite technology and production, accounting for approximately 43% of the global market in 2026. The region benefits from a robust supply chain, major OEMs (Boeing, Lockheed Martin), and extensive R&D investments by government agencies like NASA and the Department of Defense.
The aerospace composite value chain is characterized by high barriers to entry, stringent certification requirements, and long-term supplier relationships.
The value chain is becoming more integrated, with OEMs and tier-one suppliers collaborating closely on technology development. For instance, NASA's Hi-Rate Composite Aircraft Manufacturing (HiCAM) project awarded USD 50 million to 14 organizations, including Boeing and Northrop Grumman, to accelerate the development of advanced composite manufacturing processes.
The aerospace composite supply chain is global, with significant trade flows of raw materials and finished components. According to UN Comtrade data, the global trade of carbon fiber and articles thereof exceeded USD 3 billion in 2025, with the United States, Japan, and Germany as key exporters.
Supply chain risks include fluctuations in raw material prices, geopolitical tensions affecting trade, and the COVID-19 pandemic's impact on logistics. Companies are increasingly adopting dual-sourcing strategies and regionalizing supply chains to mitigate these risks.
The aerospace composite structures market is moderately consolidated, with a few global players dominating high-performance material supply. Key players include Toray Industries, Hexcel Corporation, Solvay S.A., SGL Carbon SE, Teijin Limited, Mitsubishi Chemical Holdings Corporation, Owens Corning, Gurit Holding AG, and Huntsman Corporation.
While commercial aviation dominates demand, emerging applications present significant growth opportunities.
Our analysis identifies the following white spaces:
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 12.0% from 2020-2034 |
| Segmentation |
|
By Manufacturing Process
By Matrix Type
By Aircraft Type
| By Geography |
|
The global aerospace composite structures market is estimated at USD 39.2 billion in 2026 and is projected to reach USD 121.75 billion by 2036, growing at a CAGR of 12.0%.
North America holds the largest share, accounting for approximately 43% of the global market in 2026, driven by a strong OEM base and defense spending. Asia-Pacific is the fastest-growing region.
Key trends include the adoption of thermoplastic composites for recyclability, automated fiber placement (AFP) for manufacturing efficiency, and the development of out-of-autoclave processing to reduce costs.
Leading companies include Toray Industries, Hexcel Corporation, Solvay S.A., SGL Carbon SE, Teijin Limited, Mitsubishi Chemical Holdings, Owens Corning, Gurit Holding, and Huntsman Corporation.
High manufacturing costs, technical complexity in production, and sustainability concerns related to recycling thermoset composites are the primary challenges restraining market growth.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| C-Suite Executives (CEO, CTO) | 25% |
| R&D and Engineering Directors | 35% |
| Procurement and Supply Chain Managers | 25% |
| Manufacturing and Operations Heads | 15% |
| Company Type | Representation (%) |
|---|---|
| Composite Material Suppliers | 30% |
| Aerostructure Manufacturers (Tier 1 & 2) | 25% |
| Aircraft OEMs | 20% |
| MRO & Aftermarket Providers | 15% |
| Technology & Equipment Providers | 10% |
 Related Reports


Analyst at Providence Strategic Partners at Petaling Jaya
I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

Internationalization Director
Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

Head of Product Management and Marketing
We are using your report, and it gave us valuable information."

Regional Director, Marketing and Business Development
We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

VP of Sales
Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.