1What is the current size of the aircraft turbine engine market?
The global aircraft turbine engine market was valued at USD 57.9 billion in 2023 and is projected to reach USD 93.7 billion by 2033, growing at a CAGR of 4.93%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Aircraft Turbine Engine Market
 by By Engine Type (Turbofan, Turboprop, Turboshaft, Turbojet), by By Application (Commercial Aviation, Military Aviation, Cargo Transport, Business Aviation), by By Engine Configuration (High-bypass, Medium-bypass, Low-bypass), by By Fuel Type (Jet Fuel, Biofuel, Synthetic Fuel), by By End User (Civil and Commercial Aviation, Military Aviation), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia-Pacific (China, India, Japan, South Korea, Australia), by South America (Brazil, Argentina), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034

Research Associate


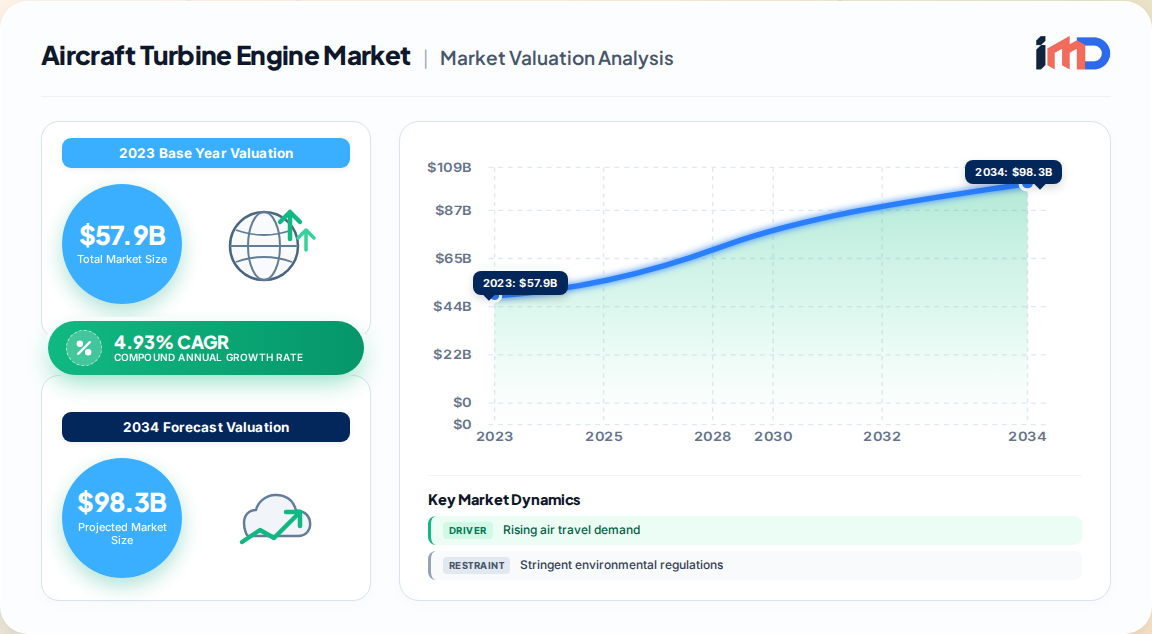
The global aircraft turbine engine market represents a cornerstone of modern aviation, underpinning commercial, military, and cargo transport operations worldwide. Our proprietary primary research estimates the market at USD 57.9 billion in 2023, with a projected expansion to USD 93.7 billion by 2033, reflecting a steady CAGR of 4.93% over the forecast period. This growth trajectory is anchored by sustained demand for fuel-efficient propulsion systems, technological advancements in engine architecture, and an expanding global aircraft fleet.
Turbine engines remain the dominant propulsion technology across all aviation segments, with turbofan engines commanding the largest share due to their superior efficiency in high-bypass configurations. The market is characterized by high barriers to entry, rigorous regulatory oversight, and a concentrated competitive landscape dominated by a handful of global OEMs. Recent supply chain disruptions and raw material price volatility have added complexity, yet long-term fundamentals remain robust.
The aircraft turbine engine market is undergoing a transformative phase, with sustainability and digitalization at the forefront.
| Segment | Sub-segment | Market Share / Growth | Key Insights |
|---|---|---|---|
| By Engine Type | Turbofan | ~71% share (2025) | Dominant due to high bypass ratios and fuel efficiency in commercial aviation. |
| Turboprop | Fastest-growing | Increasing demand for regional connectivity and efficiency on short-haul routes. | |
| Turboshaft | Steady growth | Critical for helicopters and military rotorcraft. | |
| By Application | Commercial Aviation | Largest share | Driven by fleet expansion and replacement cycles. |
| Military Aviation | Significant share | High-performance requirements and defense modernization. | |
| Cargo Transport | Fastest-growing | E-commerce boom and air freight demand. | |
| By Engine Configuration | High-bypass | Largest | Preferred for wide-body and narrow-body commercial aircraft. |
| Medium-bypass | Fastest-growing | Growing adoption in regional jets and military transports. | |
| By Fuel Type | Jet Fuel | Largest | Conventional fuel dominates current fleet. |
| Biofuel | Fastest-growing | Increasing adoption of SAF blends to meet emissions targets. | |
| By End User | Civil & Commercial | Largest | Highest volume of engine deliveries and aftermarket services. |
| Military | Stable growth | Driven by defense budgets and upgrade programs. |
North America retains the largest market share, underpinned by a robust defense sector, high air traffic, and a well-established MRO industry. The U.S. accounts for the majority of regional demand, with significant investments in next-generation propulsion technologies.
Asia-Pacific is the fastest-growing region, propelled by rapid fleet expansion, rising disposable incomes, and increasing air travel penetration. China and India are key growth engines, with substantial aircraft orders and military modernization programs.
Europe remains a mature market with a strong focus on sustainability and regulatory compliance, driving demand for fuel-efficient engines and SAF-compatible technologies. The Middle East and Africa show steady growth, supported by fleet upgrades and expanding aviation infrastructure.
The aircraft turbine engine market is highly concentrated, with a handful of global OEMs dominating design, manufacturing, and aftermarket services. Key players include General Electric (US), Rolls-Royce (UK), Pratt & Whitney (US), Safran (France), Honeywell (US), MTU Aero Engines (Germany), Engine Alliance (US), International Aero Engines (US), and Kawasaki Heavy Industries (Japan).
Competitive strategies focus on:
Recent developments include GE Aerospace's USD 11 million investment to upgrade its Singapore engine repair facility into a smart factory, and Pratt & Whitney's continued ramp-up of GTF engine production. Rolls-Royce is advancing its UltraFan technology demonstrator, targeting 25% fuel efficiency improvement over first-generation Trent engines.
The value chain spans raw material sourcing (titanium, nickel alloys, composites), engine design and manufacturing, aircraft integration, and aftermarket MRO services. High-performance materials are critical for withstanding extreme temperatures and stress, with supply concentrated among a few global suppliers.
Supply chain risks include raw material price volatility, geopolitical tensions affecting titanium and nickel supply, and capacity constraints in additive manufacturing for hot-section components. Manufacturers are increasingly localizing supply chains and investing in digital inventory management to mitigate disruptions.
Global trade in aircraft turbine engines is characterized by high-value, low-volume shipments, with major exporters including the United States, United Kingdom, France, and Germany. Key importers are China, India, and Middle Eastern nations expanding their fleets. Trade data from UN Comtrade and national customs agencies indicate steady growth in engine parts and components trade, reflecting the globalization of supply chains.
Supplier dynamics are shaped by long-term contracts, sole-sourcing for critical components, and increasing vertical integration among OEMs to secure supply and reduce risk.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2023 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.93% from 2020-2034 |
| Segmentation |
|
By Engine Configuration
By Fuel Type
By End User
| By Geography |
|
The global aircraft turbine engine market was valued at USD 57.9 billion in 2023 and is projected to reach USD 93.7 billion by 2033, growing at a CAGR of 4.93%.
Turbofan engines hold the largest market share, accounting for approximately 71% of the market in 2025, due to their fuel efficiency and widespread use in commercial aviation.
Major drivers include rising air travel demand, focus on fuel efficiency, technological innovations, military modernization, and growth in emerging markets.
Asia-Pacific is the fastest-growing region, driven by rapid fleet expansion, increasing air travel, and rising defense spending in countries like China and India.
Key players include General Electric, Rolls-Royce, Pratt & Whitney, Safran, Honeywell, MTU Aero Engines, Engine Alliance, International Aero Engines, and Kawasaki Heavy Industries.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Technology Officer | 25% |
| Engine Program Manager | 30% |
| Procurement Director | 25% |
| Airline Fleet Manager | 20% |
| Company Type | Representation (%) |
|---|---|
| Commercial Aircraft Engine OEMs | 35% |
| Military Engine Manufacturers | 20% |
| Tier-One Component Suppliers | 25% |
| MRO Service Providers | 15% |
| Aircraft Leasing Companies | 5% |
 Related Reports
