1What is the size of the Singapore defense industry market?
The Singapore defense industry market is valued at USD 10.32 billion in 2026, with a projected CAGR of 11.04% to reach USD 17.41 billion by 2031.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Singapore Defense Industry
 by Industry (MRO, Manufacturing, Design and Engineering), by Type (Aerospace, Defense), by End User (Commercial, Military), by Platform (Fixed-Wing Aircraft, Rotary-Wing Aircraft, Unmanned Aerial Vehicles (UAVs), Land Systems, Naval Systems), by Central Region, by East Region, by North Region, by West Region, by North-East Region Forecast 2026-2034

Research Associate


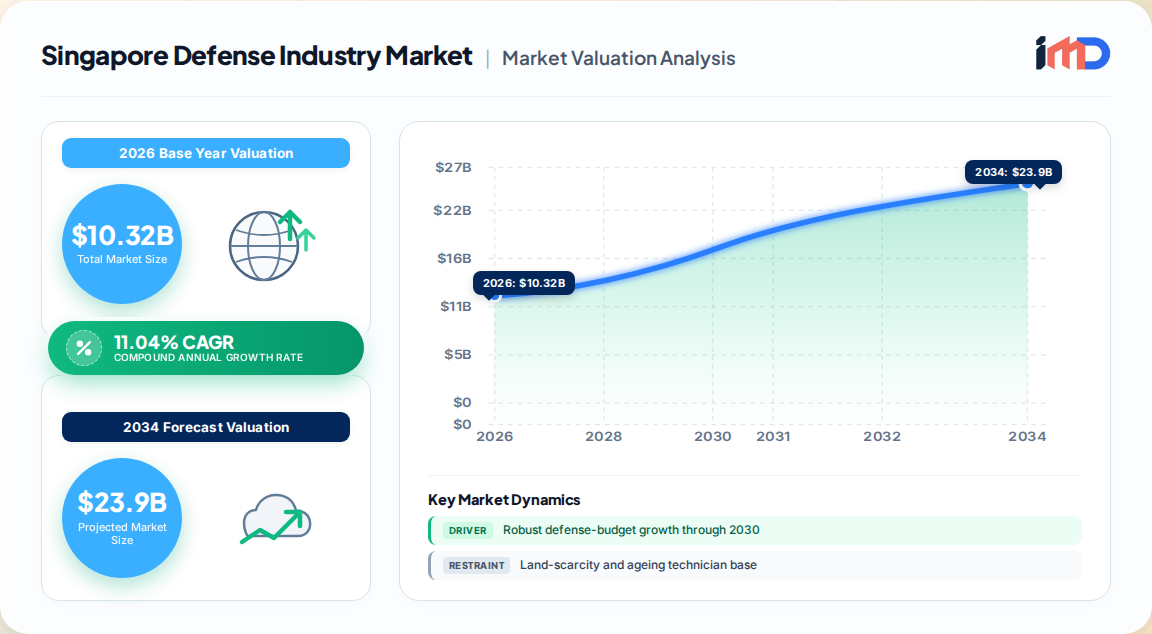
The Singapore defense industry market is a cornerstone of the nation's advanced manufacturing ecosystem, demonstrating remarkable resilience and growth. Our proprietary research estimates the market at USD 10.32 billion in 2026, expanding at a CAGR of 11.04% to reach USD 17.41 billion by 2031. This trajectory is anchored by sustained defense budget allocations, a robust maintenance, repair, and overhaul (MRO) sector, and strategic government investments in dual-use technologies.
Singapore's unique position as a global aviation and defense hub is underpinned by its world-class infrastructure, including Seletar Aerospace Park and Changi Airport. The city-state captures over 10% of the global MRO market and accounts for more than a quarter of Asia-Pacific's MRO output, supported by a cluster of over 130 aerospace companies. This ecosystem, combined with a defense budget consistently around 3% of GDP (SGD 23.4 billion in FY2025), provides long-term visibility for contractors and suppliers.
Singapore's defense trade is characterized by a substantial import surplus, reflecting its role as a major procuring and MRO hub. Official trade statistics from the World Bank's WITS database (UN Comtrade) reveal critical insights into the supplier landscape.
These dynamics position Singapore as a critical node in global defense supply chains, with strong dependencies on US and European suppliers for high-end platforms and components.
The Singapore defense industry value chain is highly integrated, spanning R&D, manufacturing, MRO, and support services.
Singapore's defense market offers a highly attractive investment landscape, albeit with distinct regional nuances.
| Region | Market Share (2025) | Key Characteristics | Investment Opportunities |
|---|---|---|---|
| Central Region | 38% | Hub for MRO, manufacturing, and corporate HQ | High-value MRO, R&D, advanced manufacturing |
| East Region | 27% | Changi Airport vicinity, logistics and MRO | Expansion of MRO facilities, supply chain integration |
| North Region | 15% | Seletar Aerospace Park, manufacturing | Aerospace component manufacturing, UAV development |
| West Region | 12% | Industrial areas, defense electronics | Defense electronics, precision engineering |
| North-East Region | 8% | Emerging aerospace clusters | Niche MRO, component supply |
The East Region, home to Changi Airport and future Terminal 5 (handling 50 million passengers annually by 2030-2035), is poised for significant growth in MRO and logistics. The North Region, centered on Seletar Aerospace Park, is a focal point for manufacturing and R&D, with government incentives driving investment in advanced technologies.
Despite the market's maturity, significant white-space opportunities exist in high-growth segments.
The competitive landscape is medium-concentrated, with leading players adopting distinct strategies.
Other notable players include RTX Corporation, Singapore Technologies Engineering Ltd., and various SMEs specializing in precision engineering and avionics. The Singapore Airshow 2026 serves as a key platform for forging strategic alliances and showcasing capabilities.
Singapore's defense procurement is characterized by a mix of domestic development and foreign acquisitions, driven by the Singapore Armed Forces' requirements.
The Singapore defense industry market is poised for robust growth, driven by strategic government investments, a thriving MRO sector, and a conducive innovation ecosystem. Despite constraints like land scarcity and cost pressures, the market's trajectory remains highly favorable, with opportunities in UAVs, space, and advanced manufacturing. Stakeholders should focus on leveraging government incentives, deepening supply chain integration, and investing in cutting-edge technologies to capitalize on this growth.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.04% from 2020-2034 |
| Segmentation |
|
By End User
By Platform
| By Geography |
|
The Singapore defense industry market is valued at USD 10.32 billion in 2026, with a projected CAGR of 11.04% to reach USD 17.41 billion by 2031.
By industry, MRO commanded 62.03% of the market share in 2025, while by type, the aerospace segment held 71.62% of revenue.
Key companies include ST Engineering, SIA Engineering, GE Aerospace, Rolls-Royce, Pratt & Whitney, and RTX Corporation, among others.
Drivers include robust defense budget growth (3% of GDP), rebound in MRO business, dual-use R&D incentives, and engine-OEM capacity expansions.
Challenges include land scarcity, ageing technician base, export-control pressures on avionics and chips, and high operating costs relative to regional peers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| MRO Operations Manager | 25% |
| Defense Program Manager | 25% |
| Supply Chain Head | 20% |
| Company Type | Representation (%) |
|---|---|
| MRO Service Providers | 30% |
| Aerospace Component Manufacturers | 25% |
| Defense Electronics Suppliers | 20% |
| Government Procurement Agencies | 15% |
| R&D and Testing Facilities | 10% |

Analyst at Providence Strategic Partners at Petaling Jaya
I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

Internationalization Director
Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

Head of Product Management and Marketing
We are using your report, and it gave us valuable information."

Regional Director, Marketing and Business Development
We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

VP of Sales
Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.
 Related Reports
