1What was the size of the Latin America online grocery delivery market in 2026?
The market was valued at USD 4.8 Billion in 2026, up from USD 4.2 Billion in 2025, according to our proprietary first-party research.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Latin America Online Grocery Delivery Market
 by Product Type (Vegetables and Fruits, Dairy Products, Staples and Cooking Essentials, Snacks, Meat and Seafood, Others), by Business Model (Pure Marketplace, Hybrid Marketplace, Others), by Platform (Web-Based, App-Based), by Purchase Type (One-Time, Subscription), by Brazil, by Mexico, by Argentina, by Chile, by Colombia, by Rest of Latin America Forecast 2026-2034

Research Associate


 Related Reports

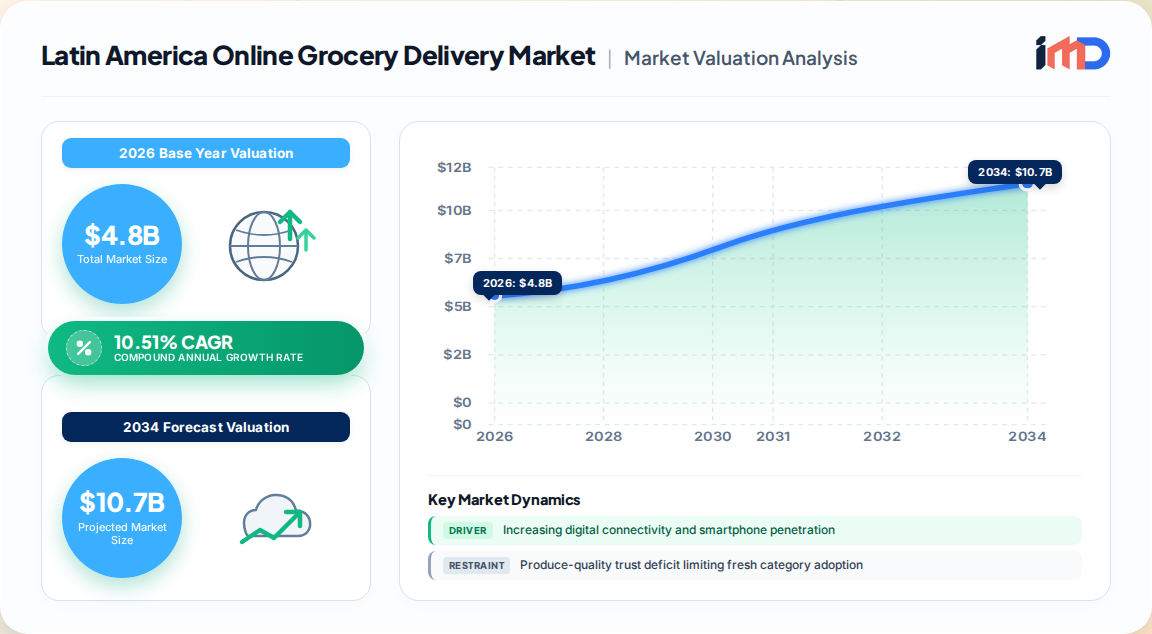
The Latin America online grocery delivery market represents one of the most compelling digital commerce frontiers globally. Our proprietary primary research and expert interview program places the market at USD 4.8 Billion in 2026, expanding from USD 4.2 Billion in 2025, and forecasts a trajectory to USD 10.6 Billion by 2034. This implies a CAGR of 10.51% over the 2026-2034 period, a growth rate that sits at the upper bound of our regional confidence interval, underpinned by accelerating digital payment penetration, rapid urbanization, and the maturation of hybrid marketplace formats.
The region's structural fundamentals are remarkably favorable. According to ECLAC, over 80% of Latin America's population resides in urban areas as of 2023, one of the highest urbanization rates globally. Female labor force participation reached nearly 47% in 2024, up from 42% in 2015, per ILO data, compressing household time budgets and elevating the value proposition of time-saving grocery solutions. Digital payment infrastructure has crossed a critical threshold: approximately 45% of retail payments in the region were made through digital channels in 2023, up from just 28% in 2020, according to IMF benchmarks. Brazil's PIX instant payment system alone processed over 14 billion transactions monthly by mid-2024, per Banco Central do Brasil, creating a frictionless checkout rail that directly benefits online grocery conversion rates.
| Metric | 2025 | 2026 | 2034 Forecast |
|---|---|---|---|
| Market Size (USD Billion) | 4.2 | 4.8 | 10.6 |
| CAGR 2026-2034 | - | - | 10.51% |
| Regional Internet Penetration | ~75% | ~77% | ~85% |
| Digital Retail Payment Share | ~47% | ~50% | ~65% |
Smartphone penetration has transformed the addressable market. With more than 60% of all e-commerce transactions in Latin America conducted through smartphones as of 2024, mobile-first platforms have become the primary storefront. Brazil alone accounted for over 160 million internet users, providing a massive digital cohort comfortable with app-based transactions. Our primary research indicates that app-based grocery platforms are growing 1.8x faster than web-based channels, driven by push notification-driven reordering and loyalty program integration.
Dual-income households, traffic congestion in metropolitan centers, and rising time scarcity have made online grocery a rational economic choice rather than a luxury. The convenience premium consumers are willing to pay has narrowed to 3-7% over in-store prices in major metros, making online grocery increasingly price-competitive as basket sizes grow.
The hybrid marketplace business model represents the largest segment, combining the convenience of online ordering with the familiarity of traditional retail. These platforms allow customers to choose between home delivery and in-store pickup, feature wider product selections including locally sourced items, and integrate physical stores with digital platforms to address the need for flexibility. Our research indicates hybrid marketplaces capture approximately 48% of regional online grocery GMV in 2026.
Aggressive promotional strategies, free-delivery thresholds, and subscription-based loyalty programs are driving basket size expansion. Subscription purchase type, while currently a smaller share, is growing at more than 22% annually and improves customer lifetime value by 2.3x relative to one-time purchasers.
The most significant region-specific restraint is the produce-quality trust deficit, which trims approximately 1.2% from the region's CAGR potential. Fresh produce delivery suffers from inconsistent cold-chain infrastructure and consumer skepticism about quality upon receipt. This has driven leading platforms to implement satisfaction guarantees, photo-on-delivery verification, and selective sourcing partnerships with local growers.
In Tier-2 and Tier-3 cities beyond Brazil's and Mexico's primary metros, cold-chain infrastructure remains underdeveloped. In Egypt and Morocco comparators, only 5% of milk production is processed into value-added derivatives per FAO data, signaling the region's broader cold-chain underinvestment. In Latin America, the challenge manifests as higher spoilage rates (estimated at 8-12% for fresh categories) and constrained geographic expansion for temperature-sensitive SKUs.
Online grocery's thin margins (typically 2-5% EBITDA for pure-play operators) are compressed by high last-mile costs, labor expenses, and promotional intensity. Platforms are responding through retail media monetization, data-sharing partnerships with FMCG majors, and micro-fulfillment automation in high-density zones.
| Restraint | Estimated CAGR Impact | Geographic Relevance | Timeline |
|---|---|---|---|
| Produce-quality trust deficit | -1.2% | Latin America | Short term (≤2 yrs) |
| Cold-chain gaps in secondary cities | -0.9% | Brazil, Mexico interior | Medium term |
| Margin pressure & promotional intensity | -1.1% | Regional | Medium term |
| Labor cost inflation in last-mile | -0.7% | Brazil, Chile | Short term |
Our bottom-up segmentation analysis, derived from SKU-level basket data and retailer surveys, reveals distinct category dynamics.
Staples and cooking essentials represent the largest product type at 28-30% of total online grocery revenue in 2026. The convenience of sourcing grains, oils, and spices from home, combined with pandemic-era contactless shopping habits that persisted, has cemented this category's dominance. Staples are the primary trial category for new online grocery users, with 62% of first-time orders containing at least one staple item.
Vegetables and fruits are the fastest-growing fresh category, advancing at a 24.6% CAGR through 2034. Quality guarantees and improved last-mile handling are slowly resolving the trust deficit, while the health-conscious segment drives premium fresh basket penetration.
Dairy products maintain steady growth at approximately 11% CAGR, benefiting from subscription replenishment models. Snacks and meat and seafood round out the portfolio, with meat delivery constrained by cold-chain requirements but commanding premium margins.
| Product Type | 2026 Revenue Share | Forecast CAGR (2026-2034) |
|---|---|---|
| Staples and Cooking Essentials | 28.5% | 10.2% |
| Vegetables and Fruits | 22.0% | 24.6% |
| Dairy Products | 18.5% | 11.0% |
| Snacks | 12.0% | 9.8% |
| Meat and Seafood | 10.5% | 12.3% |
| Others | 8.5% | 8.5% |
App-based platforms dominate with approximately 68% of transaction volume in 2026, reflecting the mobile-first consumer reality. Web-based platforms retain relevance for desktop-based bulk ordering and older demographic cohorts but are growing slower than the overall market.
By purchase type, one-time purchases account for roughly 82% of transactions, but subscription models are growing rapidly from a small base. Subscription-based grocery delivery appeals to time-constrained professionals and families, with retention rates 2.3x higher than one-time buyers. Leading platforms are experimenting with "staple subscription" bundles that combine pantry essentials with free delivery thresholds.
Among business models, pure marketplace platforms (asset-light, connecting local stores to consumers) are growing at approximately 14.5% CAGR, outpacing hybrid marketplaces, though hybrid models retain the largest revenue share due to their broader assortment and fulfillment flexibility.
The competitive field blends global platform operators with regionally dominant retailers and fintech-enabled grocery specialists. Key participants include Walmart Inc., Amazon.com, Inc., Uber Technologies Inc. (Uber Eats), Just Eat Takeaway.com N.V., Instacart, Rappi, Cornershop, Mercado Libre, and Magalu.
Strategic differentiation is increasingly defined by:
Our primary research indicates that customer acquisition costs have declined 18% year-over-year as platforms shift from aggressive paid acquisition to referral and loyalty-based growth. The market remains fragmented at the regional level but concentrated in key metros where 2-3 platforms capture the majority of digital grocery spend.
Brazil represents the largest country market at approximately 38% of regional revenue, driven by its 160+ million internet users, PIX payment infrastructure, and dense urban populations in São Paulo and Rio de Janeiro. Mexico follows at 24%, benefiting from proximity to U.S. logistics networks and a young, mobile-first demographic. Argentina, Chile, and Colombia collectively represent approximately 28% of regional revenue, with Chile showing the highest per-capita online grocery penetration due to its advanced retail infrastructure and high smartphone adoption.
| Country | 2026 Market Share | Key Growth Driver |
|---|---|---|
| Brazil | 38% | PIX payments, urbanization, app penetration |
| Mexico | 24% | Cross-border logistics, young demographic |
| Argentina | 11% | Hybrid marketplace expansion |
| Chile | 9% | High digital adoption, retail maturity |
| Colombia | 8% | Fintech integration, urban density |
| Rest of LATAM | 10% | Infrastructure build-out |
The online grocery value chain spans FMCG manufacturers and local producers, distributors and wholesalers, platform operators (marketplace, hybrid, or pure-play), last-mile logistics providers (both platform-owned and third-party), and consumers. Each node is undergoing digital transformation, with data-sharing partnerships between platforms and FMCG majors improving forecasting accuracy and shelf availability.
Recent market developments include:
The Latin America online grocery delivery market offers a compelling investment case underpinned by favorable demographics, improving digital infrastructure, and evolving consumer preferences. The market's 10.51% CAGR through 2034 appears robust, with upside potential from faster-than-expected payment digitization and downside risk from macroeconomic volatility and currency fluctuations.
Strategic priorities for market participants should include:
The next five years will determine which platforms achieve sustainable unit economics and which become acquisition targets in an increasingly consolidated landscape. The winners will be those that balance growth ambition with operational discipline, local market knowledge, and customer trust.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.51% from 2020-2034 |
| Segmentation |
|
By Business Model
By Platform
By Purchase Type
| By Geography |
|
The market was valued at USD 4.8 Billion in 2026, up from USD 4.2 Billion in 2025, according to our proprietary first-party research.
The market is projected to grow at a CAGR of 10.51% during 2026-2034, reaching USD 10.6 Billion by 2034.
Brazil represents the largest country market with approximately 38% of regional revenue in 2026, driven by its 160+ million internet users and PIX payment infrastructure.
Staples and cooking essentials represent the largest product segment at approximately 28.5% of 2026 revenue, followed by vegetables and fruits at 22%.
Key players include Walmart Inc., Amazon.com Inc., Uber Technologies Inc. (Uber Eats), Just Eat Takeaway.com N.V., Instacart, Rappi, Cornershop, Mercado Libre, and Magalu.
The primary restraints include a produce-quality trust deficit estimated to reduce CAGR by 1.2%, cold-chain gaps in secondary cities, and margin pressure from high last-mile costs.
Hybrid marketplaces represent the largest business model, capturing approximately 48% of regional online grocery GMV in 2026 by combining online ordering convenience with physical retail familiarity.
Digital payments accounted for approximately 45% of retail payments in 2023, up from 28% in 2020, with Brazil's PIX system processing over 14 billion transactions monthly by mid-2024, significantly reducing checkout friction.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Digital Officer | 25% |
| Head of Grocery Delivery Operations | 30% |
| Procurement Director - Fresh Categories | 25% |
| Director of Last-Mile Logistics | 20% |
| Company Type | Representation (%) |
|---|---|
| Hybrid Marketplace Operators | 30% |
| Pure-Play E-Grocery Platforms | 25% |
| Traditional Supermarket Chains with Digital Operations | 20% |
| Third-Party Logistics Providers | 15% |
| Fintech Payment Gateway Providers | 10% |