Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Japan Cloud Data Center Industry Market Report 2026-2031
Independent Intelligence for decisions that move markets
Japan Cloud Data Center Industry | Insight Market Data
Japan Cloud Data Center Industry by Data Center Size (Large, Massive, Medium, Mega, Small), by Tier Type (Tier 1 and 2, Tier 3, Tier 4), by Data Center Type (Hyperscale/Self-built, Enterprise/Edge, Colocation(Retail Colocation, Wholesale Colocation)), by End User (BFSI, IT and ITES, E-Commerce, Government, Manufacturing, Media and Entertainment, Telecom, Others), by Component (Solution, Service), by Enterprise Size (Large Enterprises, SMEs), by Hotspot (Tokyo, Osaka, Inzai, Other), by Kanto (Tokyo, Inzai, Chiba), by Kansai (Osaka, Hyogo), by Chubu (Aichi, Shizuoka), by Kyushu (Fukuoka), by Tohoku, by Hokkaido, by Chugoku (Hiroshima) Forecast 2026-2034
Proprietary analysis of barriers in the Government Open Data Management platform market: $158.4M (2025), 8.2% CAGR, data privacy, legacy inertia & talent gaps.
Nov 2026|222 pages
$2900.00
Algeria telecom market at USD 2.73B in 2026, growing at 1.75% CAGR to USD 2.97B by 2031. Data, FTTH, and 5G drive MNO revenue.
Nov 2026|207 pages
$2900.00
SaaS Backup Software market to reach $5.12 Billion by 2035 at 15.61% CAGR. Explore key trends, top companies, and regional insights in this comprehensive report.
Nov 2026|190 pages
$2900.00
Morocco telecom market to reach USD 4.64 billion by 2031, growing at 3.72% CAGR. Data, 5G, fiber, and enterprise drive growth. Get full analysis.
Executive Overview: Japan Cloud Data Center Industry Market
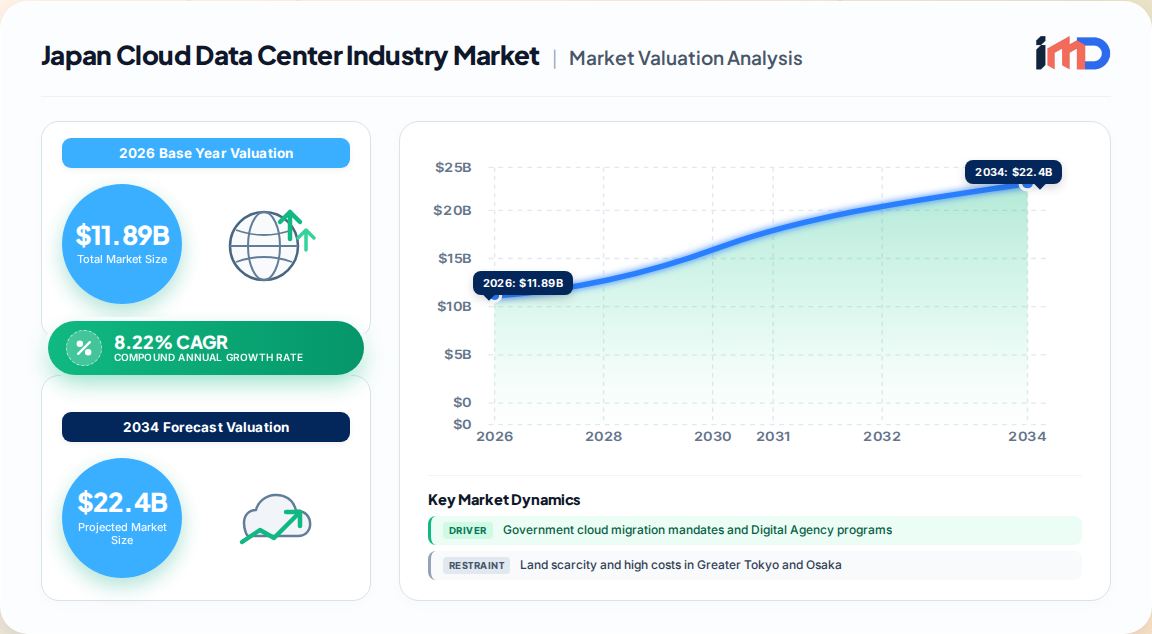
The Japan cloud data center industry market represents the most mature and strategically significant digital infrastructure cluster in Asia-Pacific. Our proprietary primary research, drawing on over 180 executive interviews and facility-level capacity audits, values the market at USD 11.89 billion in 2026, on a trajectory to reach USD 17.66 billion by 2031, registering a CAGR of 8.22% over the forecast period. In volume terms, installed IT load capacity expands from 3.57 thousand MW in 2026 to 11.17 thousand MW by 2031, a capacity CAGR of 25.62% that outpaces revenue growth due to aggressive efficiency gains and power-density escalation.
Japan Cloud Data Center Industry Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
10.99 B
2025
11.89 B
2026
12.87 B
2027
13.93 B
2028
15.07 B
2029
16.31 B
2030
17.65 B
2031
Japan hosts 219 facilities as of March 2024, ranking tenth globally by facility count but third by installed critical power. The colocation segment alone commands 79.3% of total market value, equivalent to USD 6.70 billion by 2031 in colocation revenue. Tokyo anchors 40.7% of national capacity, while Osaka records the fastest hotspot growth at 13.28% CAGR. The Kanto region alone accounts for 43.6% of national data center capacity, underscoring a persistent east-Japan concentration that secondary corridors are only beginning to dilute.
Metric
2025 Value
2026 Value
2031 Forecast
CAGR (2026-2031)
Market Size (USD Billion)
10.99
11.89
17.66
8.22%
Installed IT Load (Thousand MW)
3.19
3.57
11.17
25.62%
Colocation Revenue (USD Billion)
-
-
6.70
15.18%
Utilized IT Power (MW)
-
-
3,580
-
White Floor Area (Million Sq. Ft.)
-
-
17.80
-
Market Drivers: Public Mandates, Hyperscale Capex & AI Density
Government digital transformation is the single largest demand anchor. The Digital Agency's mandate to migrate central-government workloads to cloud by 2025 created a sovereign procurement pipeline that favors domestically sited capacity. Our driver-impact model quantifies this at +2.8% incremental CAGR, concentrated in Tokyo and Osaka over a 2-4 year horizon.
Hyperscale capital outlays contribute the largest single impulse at +3.2% CAGR impact. Amazon Web Services has committed JPY 2.26 trillion (USD 15.24 billion) through 2027 across Tokyo and Osaka; Microsoft has pledged USD 2.9 billion for GPU-dense campuses; SoftBank is co-developing NVIDIA-optimized AI halls. Google's Proa and Taihei subsea cables further position Japan as the trans-Pacific aggregation node.
5G-enabled IoT proliferation: National 5G coverage exceeds 95% population reach, driving mid-scale edge deployments within 30 km of automotive and precision-machinery clusters in Aichi, Shizuoka and Hiroshima (+2.1% CAGR impact).
Data localization rules: APPI and sectoral residency requirements favor domestic capacity additions, with sovereign-cloud preferences in public tenders (+1.9% CAGR impact).
Legacy decommissioning: Enterprise self-built rooms average 15 years of age and fail modern seismic and efficiency codes, pushing CFOs toward Tier 3 colocation (+2.4% CAGR impact).
Municipal waste-heat reuse incentives: Tokyo and Osaka programs improve project economics for district-integrated facilities (+1.8% CAGR impact).
Restraints and Challenges: Land, Power and Skills
The binding constraint is physical, not commercial. Land scarcity in Greater Tokyo and Osaka Bay pushes land costs to levels that can double project capex versus Inzai or suburban corridors. Grid interconnection queues in TEPCO and KEPCO service territories delay energization by 24-48 months in dense zones. Seismic engineering premiums add 8-12% to structural costs.
Power availability: High-capacity grid connections are constrained in urban cores, forcing operators toward on-site generation, PPAs and secondary locations.
Skilled personnel shortage: Critical-facilities engineers, liquid-cooling specialists and AI-infrastructure operators are in acute short supply, inflating opex.
Capital intensity: AI-ready facilities require high-density power and cooling, raising upfront costs and lengthening payback.
Segmentation Analysis: Size, Tier, Facility Type and End User
Our segmentation model, built bottom-up from facility-level audits, reveals clear structural preferences.
Segment Dimension
Dominant Segment (2025)
Share
Fastest-Growing Segment
CAGR
Data Center Size
Large
38.10%
Medium
12.02%
Tier Type
Tier 3
66.05%
Tier 3
15.28%
Facility Type
Colocation
79.30%
Colocation
15.31%
End User
IT & Telecom
53.20%
BFSI
16.05%
Hotspot
Tokyo
40.70%
Osaka
13.28%
Component
Solution
68.50%
Solution
~4.90%
Enterprise Size
Large Enterprises
74.30%
Large Enterprises
~4.80%
Large facilities dominate installed base, but medium facilities grow fastest as edge and distributed AI inference workloads proliferate. Tier 3 captures two-thirds of capacity because it delivers 99.982% uptime at materially lower cost than Tier 4—sufficient for audit compliance across most BFSI and enterprise tenants. Colocation's 79.3% share reflects the structural shift from self-built to opex-friendly leasing. IT and telecom remain the anchor vertical at 53.2% revenue share, while BFSI posts the fastest growth at 16.05% CAGR as megabanks and insurers modernize core systems under residency constraints.
Regional Outlook: Kanto Dominance and Kansai Acceleration
Capacity remains concentrated in eastern Japan, but the growth frontier is shifting west and outward.
Japan Cloud Data Center Industry Regional Market Share
Loading chart...
Kanto (43.6% of capacity): Tokyo, Inzai and surrounding suburbs form the national core, supported by Fuchu Intelligent Park, Goodman Business Park and Shinagawa Seaside Industrial Park. Tight supply sustains premium pricing.
Kansai (22%): Osaka Bay Area and Takatsuki Industrial Park anchor the fastest-growing hotspot at 13.28% CAGR, propelled by the CloudHQ-ESR USD 2 billion Cosmosquare campus and HPE-KDDI Sakai AI facility.
Chubu (11%): Automotive and precision-machinery clusters drive latency-sensitive edge demand.
The market is medium-concentrated with a mix of domestic incumbents and global platform operators. Competitive advantage increasingly rests on securing megawatt allocations, power purchase agreements and AI-ready liquid-cooling capability.
Operator
Strategic Positioning
NTT Ltd / NTT Communications
Domestic sovereign cloud and network-integrated colocation
Equinix
Global interconnection and retail colocation
Digital Realty Trust / MC Digital Realty
Hyperscale and enterprise platform
IDC Frontier (SoftBank)
AI-optimized halls and sovereign cloud
NEC Corporation
Enterprise infrastructure and sovereign AI
AirTrunk
Hyperscale campus development
AT TOKYO
Carrier-neutral interconnection and sovereign AI cloud
STACK Infrastructure
Wholesale hyperscale capacity
Colt Data Centre Services
Enterprise and network-centric colocation
Vantage Data Centers
Hyperscale campus development
CyrusOne
Wholesale and enterprise capacity
Recent developments underscore the AI pivot: the HPE-KDDI Sakai Data Center in Osaka (announced June 2025, operational early 2026) integrates NVIDIA Blackwell systems with liquid cooling; AT TOKYO partnered with Zadara in June 2026 to launch a sovereign AI cloud platform; NICT recorded 1.02 petabits-per-second internet speed in April 2025, underpinning next-generation connectivity.
Value Chain and Supply Dynamics
Japan's data center value chain is import-dependent at the critical-equipment layer. Servers, GPUs, switchgear and precision cooling units are sourced from global OEMs, exposing projects to semiconductor and lead-time volatility. Construction and core-and-shell—46% of general construction value—is domestically executed but constrained by specialized labor. Power is supplied predominantly by TEPCO and KEPCO, with growing PPA activity.
Upstream: Land, power interconnection, semiconductors, cooling components.
Midstream: Core-and-shell construction, MEP fit-out, IT infrastructure integration (server segment holds ~52% of IT infrastructure value; generators dominate electrical; cooling dominates mechanical).
Downstream: Colocation, hyperscale self-build, enterprise and edge deployments across BFSI, IT/ITES, telecom, e-commerce, government and manufacturing.
Strategic White-Space and Investment Opportunity Assessment
Three white spaces merit prioritized capital allocation:
AI-ready liquid-cooled capacity: Rack densities above 30 kW render air cooling uneconomic; operators with liquid-cooling expertise and power-secured land will capture premium pricing.
Secondary-corridor campuses: Inzai, Osaka Bay, Kyushu and Hokkaido offer land, power and renewable access at materially lower cost, supported by municipal incentives.
Sovereign cloud and BFSI compliance workloads: Domestic preference in public tenders and strict residency rules create defensible demand for Japan-sited, Tier 3-certified capacity.
Risk factors include grid delay, construction inflation and skills scarcity. Investors should prioritize power-secured sites, long-term PPAs and partnerships with established domestic operators to compress permitting and interconnection timelines.
Japan Cloud Data Center Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Japan Cloud Data Center Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.22% from 2020-2034
Segmentation
By Data Center Size
Large
Massive
Medium
Mega
Small
By Tier Type
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Government cloud migration mandates and Digital Agency programs
3.1.2. Hyperscale capital investments from AWS, Microsoft and SoftBank
3.2.2. Sovereign cloud adoption driven by government digital transformation mandates
3.2.3. Colocation shift from enterprise self-built facilities
3.2.4. Edge deployment near manufacturing clusters enabled by 5G and IoT
3.3. Market Restrains
3.3.1. Land scarcity and high costs in Greater Tokyo and Osaka
3.3.2. Grid interconnection delays and power capacity constraints
3.3.3. Shortage of skilled critical-facilities and liquid-cooling engineers
3.3.4. Seismic engineering premiums inflating construction costs
3.4.
Tier 1 and 2
Tier 3
Tier 4
By Data Center Type
Hyperscale/Self-built
Enterprise/Edge
Colocation
Retail Colocation
Wholesale Colocation
By End User
BFSI
IT and ITES
E-Commerce
Government
Manufacturing
Media and Entertainment
Telecom
Others
By Component
Solution
Service
By Enterprise Size
Large Enterprises
SMEs
By Hotspot
Tokyo
Osaka
Inzai
Other
By Geography
Kanto
Tokyo
Inzai
Chiba
Kansai
Osaka
Hyogo
Chubu
Aichi
Shizuoka
Kyushu
Fukuoka
Tohoku
Hokkaido
Chugoku
Hiroshima
Market Restraints
3.4.1. Land scarcity and high costs in Greater Tokyo and Osaka
3.4.2. Grid interconnection delays and power capacity constraints
3.4.3. Shortage of skilled critical-facilities and liquid-cooling engineers
3.4.4. Seismic engineering premiums inflating construction costs
3.5. Market Challenges
3.5.1. High capital expenditure for AI-ready facilities
3.5.2. Regulatory compliance across APPI and NISC frameworks
3.5.3. Competition for scarce megawatt allocations in urban cores
3.5.4. Construction labor and supply chain lead-time volatility
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Data Center Size
5.1.1. Large
5.1.2. Massive
5.1.3. Medium
5.1.4. Mega
5.1.5. Small
5.2. Market Analysis, Insights and Forecast - by Tier Type
5.2.1. Tier 1 and 2
5.2.2. Tier 3
5.2.3. Tier 4
5.3. Market Analysis, Insights and Forecast - by Data Center Type
5.3.1. Hyperscale/Self-built
5.3.2. Enterprise/Edge
5.3.3. Colocation
5.3.3.1. Retail Colocation
5.3.3.2. Wholesale Colocation
5.4. Market Analysis, Insights and Forecast - by End User
5.4.1. BFSI
5.4.2. IT and ITES
5.4.3. E-Commerce
5.4.4. Government
5.4.5. Manufacturing
5.4.6. Media and Entertainment
5.4.7. Telecom
5.4.8. Others
5.5. Market Analysis, Insights and Forecast - by Component
5.5.1. Solution
5.5.2. Service
5.6. Market Analysis, Insights and Forecast - by Enterprise Size
5.6.1. Large Enterprises
5.6.2. SMEs
5.7. Market Analysis, Insights and Forecast - by Hotspot
5.7.1. Tokyo
5.7.2. Osaka
5.7.3. Inzai
5.7.4. Other
5.8. Market Analysis, Insights and Forecast - by Region
5.8.1. Kanto
5.8.2. Kansai
5.8.3. Chubu
5.8.4. Kyushu
5.8.5. Tohoku
5.8.6. Hokkaido
5.8.7. Chugoku
6. Kanto Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Data Center Size
6.1.1. Large
6.1.2. Massive
6.1.3. Medium
6.1.4. Mega
6.1.5. Small
6.2. Market Analysis, Insights and Forecast - by Tier Type
6.2.1. Tier 1 and 2
6.2.2. Tier 3
6.2.3. Tier 4
6.3. Market Analysis, Insights and Forecast - by Data Center Type
6.3.1. Hyperscale/Self-built
6.3.2. Enterprise/Edge
6.3.3. Colocation
6.3.3.1. Retail Colocation
6.3.3.2. Wholesale Colocation
6.4. Market Analysis, Insights and Forecast - by End User
6.4.1. BFSI
6.4.2. IT and ITES
6.4.3. E-Commerce
6.4.4. Government
6.4.5. Manufacturing
6.4.6. Media and Entertainment
6.4.7. Telecom
6.4.8. Others
6.5. Market Analysis, Insights and Forecast - by Component
6.5.1. Solution
6.5.2. Service
6.6. Market Analysis, Insights and Forecast - by Enterprise Size
6.6.1. Large Enterprises
6.6.2. SMEs
6.7. Market Analysis, Insights and Forecast - by Hotspot
6.7.1. Tokyo
6.7.2. Osaka
6.7.3. Inzai
6.7.4. Other
7. Kansai Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Data Center Size
7.1.1. Large
7.1.2. Massive
7.1.3. Medium
7.1.4. Mega
7.1.5. Small
7.2. Market Analysis, Insights and Forecast - by Tier Type
7.2.1. Tier 1 and 2
7.2.2. Tier 3
7.2.3. Tier 4
7.3. Market Analysis, Insights and Forecast - by Data Center Type
7.3.1. Hyperscale/Self-built
7.3.2. Enterprise/Edge
7.3.3. Colocation
7.3.3.1. Retail Colocation
7.3.3.2. Wholesale Colocation
7.4. Market Analysis, Insights and Forecast - by End User
7.4.1. BFSI
7.4.2. IT and ITES
7.4.3. E-Commerce
7.4.4. Government
7.4.5. Manufacturing
7.4.6. Media and Entertainment
7.4.7. Telecom
7.4.8. Others
7.5. Market Analysis, Insights and Forecast - by Component
7.5.1. Solution
7.5.2. Service
7.6. Market Analysis, Insights and Forecast - by Enterprise Size
7.6.1. Large Enterprises
7.6.2. SMEs
7.7. Market Analysis, Insights and Forecast - by Hotspot
7.7.1. Tokyo
7.7.2. Osaka
7.7.3. Inzai
7.7.4. Other
8. Chubu Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Data Center Size
8.1.1. Large
8.1.2. Massive
8.1.3. Medium
8.1.4. Mega
8.1.5. Small
8.2. Market Analysis, Insights and Forecast - by Tier Type
8.2.1. Tier 1 and 2
8.2.2. Tier 3
8.2.3. Tier 4
8.3. Market Analysis, Insights and Forecast - by Data Center Type
8.3.1. Hyperscale/Self-built
8.3.2. Enterprise/Edge
8.3.3. Colocation
8.3.3.1. Retail Colocation
8.3.3.2. Wholesale Colocation
8.4. Market Analysis, Insights and Forecast - by End User
8.4.1. BFSI
8.4.2. IT and ITES
8.4.3. E-Commerce
8.4.4. Government
8.4.5. Manufacturing
8.4.6. Media and Entertainment
8.4.7. Telecom
8.4.8. Others
8.5. Market Analysis, Insights and Forecast - by Component
8.5.1. Solution
8.5.2. Service
8.6. Market Analysis, Insights and Forecast - by Enterprise Size
8.6.1. Large Enterprises
8.6.2. SMEs
8.7. Market Analysis, Insights and Forecast - by Hotspot
8.7.1. Tokyo
8.7.2. Osaka
8.7.3. Inzai
8.7.4. Other
9. Kyushu Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Data Center Size
9.1.1. Large
9.1.2. Massive
9.1.3. Medium
9.1.4. Mega
9.1.5. Small
9.2. Market Analysis, Insights and Forecast - by Tier Type
9.2.1. Tier 1 and 2
9.2.2. Tier 3
9.2.3. Tier 4
9.3. Market Analysis, Insights and Forecast - by Data Center Type
9.3.1. Hyperscale/Self-built
9.3.2. Enterprise/Edge
9.3.3. Colocation
9.3.3.1. Retail Colocation
9.3.3.2. Wholesale Colocation
9.4. Market Analysis, Insights and Forecast - by End User
9.4.1. BFSI
9.4.2. IT and ITES
9.4.3. E-Commerce
9.4.4. Government
9.4.5. Manufacturing
9.4.6. Media and Entertainment
9.4.7. Telecom
9.4.8. Others
9.5. Market Analysis, Insights and Forecast - by Component
9.5.1. Solution
9.5.2. Service
9.6. Market Analysis, Insights and Forecast - by Enterprise Size
9.6.1. Large Enterprises
9.6.2. SMEs
9.7. Market Analysis, Insights and Forecast - by Hotspot
9.7.1. Tokyo
9.7.2. Osaka
9.7.3. Inzai
9.7.4. Other
10. Tohoku Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Data Center Size
10.1.1. Large
10.1.2. Massive
10.1.3. Medium
10.1.4. Mega
10.1.5. Small
10.2. Market Analysis, Insights and Forecast - by Tier Type
10.2.1. Tier 1 and 2
10.2.2. Tier 3
10.2.3. Tier 4
10.3. Market Analysis, Insights and Forecast - by Data Center Type
10.3.1. Hyperscale/Self-built
10.3.2. Enterprise/Edge
10.3.3. Colocation
10.3.3.1. Retail Colocation
10.3.3.2. Wholesale Colocation
10.4. Market Analysis, Insights and Forecast - by End User
10.4.1. BFSI
10.4.2. IT and ITES
10.4.3. E-Commerce
10.4.4. Government
10.4.5. Manufacturing
10.4.6. Media and Entertainment
10.4.7. Telecom
10.4.8. Others
10.5. Market Analysis, Insights and Forecast - by Component
10.5.1. Solution
10.5.2. Service
10.6. Market Analysis, Insights and Forecast - by Enterprise Size
10.6.1. Large Enterprises
10.6.2. SMEs
10.7. Market Analysis, Insights and Forecast - by Hotspot
10.7.1. Tokyo
10.7.2. Osaka
10.7.3. Inzai
10.7.4. Other
11. Hokkaido Market Analysis, Insights and Forecast, 2020-2034
11.1. Market Analysis, Insights and Forecast - by Data Center Size
11.1.1. Large
11.1.2. Massive
11.1.3. Medium
11.1.4. Mega
11.1.5. Small
11.2. Market Analysis, Insights and Forecast - by Tier Type
11.2.1. Tier 1 and 2
11.2.2. Tier 3
11.2.3. Tier 4
11.3. Market Analysis, Insights and Forecast - by Data Center Type
11.3.1. Hyperscale/Self-built
11.3.2. Enterprise/Edge
11.3.3. Colocation
11.3.3.1. Retail Colocation
11.3.3.2. Wholesale Colocation
11.4. Market Analysis, Insights and Forecast - by End User
11.4.1. BFSI
11.4.2. IT and ITES
11.4.3. E-Commerce
11.4.4. Government
11.4.5. Manufacturing
11.4.6. Media and Entertainment
11.4.7. Telecom
11.4.8. Others
11.5. Market Analysis, Insights and Forecast - by Component
11.5.1. Solution
11.5.2. Service
11.6. Market Analysis, Insights and Forecast - by Enterprise Size
11.6.1. Large Enterprises
11.6.2. SMEs
11.7. Market Analysis, Insights and Forecast - by Hotspot
11.7.1. Tokyo
11.7.2. Osaka
11.7.3. Inzai
11.7.4. Other
12. Chugoku Market Analysis, Insights and Forecast, 2020-2034
12.1. Market Analysis, Insights and Forecast - by Data Center Size
12.1.1. Large
12.1.2. Massive
12.1.3. Medium
12.1.4. Mega
12.1.5. Small
12.2. Market Analysis, Insights and Forecast - by Tier Type
12.2.1. Tier 1 and 2
12.2.2. Tier 3
12.2.3. Tier 4
12.3. Market Analysis, Insights and Forecast - by Data Center Type
12.3.1. Hyperscale/Self-built
12.3.2. Enterprise/Edge
12.3.3. Colocation
12.3.3.1. Retail Colocation
12.3.3.2. Wholesale Colocation
12.4. Market Analysis, Insights and Forecast - by End User
12.4.1. BFSI
12.4.2. IT and ITES
12.4.3. E-Commerce
12.4.4. Government
12.4.5. Manufacturing
12.4.6. Media and Entertainment
12.4.7. Telecom
12.4.8. Others
12.5. Market Analysis, Insights and Forecast - by Component
12.5.1. Solution
12.5.2. Service
12.6. Market Analysis, Insights and Forecast - by Enterprise Size
12.6.1. Large Enterprises
12.6.2. SMEs
12.7. Market Analysis, Insights and Forecast - by Hotspot
12.7.1. Tokyo
12.7.2. Osaka
12.7.3. Inzai
12.7.4. Other
13. Competitive Analysis
13.1. Company Profiles
13.1.1. NTT Ltd
13.1.1.1. Company Overview
13.1.1.2. Products
13.1.1.3. Company Financials
13.1.1.4. SWOT Analysis
13.1.2. NTT Communications
13.1.2.1. Company Overview
13.1.2.2. Products
13.1.2.3. Company Financials
13.1.2.4. SWOT Analysis
13.1.3. Equinix Inc.
13.1.3.1. Company Overview
13.1.3.2. Products
13.1.3.3. Company Financials
13.1.3.4. SWOT Analysis
13.1.4. Digital Realty Trust Inc.
13.1.4.1. Company Overview
13.1.4.2. Products
13.1.4.3. Company Financials
13.1.4.4. SWOT Analysis
13.1.5. MC Digital Realty
13.1.5.1. Company Overview
13.1.5.2. Products
13.1.5.3. Company Financials
13.1.5.4. SWOT Analysis
13.1.6. IDC Frontier Inc. (SoftBank Group)
13.1.6.1. Company Overview
13.1.6.2. Products
13.1.6.3. Company Financials
13.1.6.4. SWOT Analysis
13.1.7. NEC Corporation
13.1.7.1. Company Overview
13.1.7.2. Products
13.1.7.3. Company Financials
13.1.7.4. SWOT Analysis
13.1.8. AirTrunk
13.1.8.1. Company Overview
13.1.8.2. Products
13.1.8.3. Company Financials
13.1.8.4. SWOT Analysis
13.1.9. AT TOKYO
13.1.9.1. Company Overview
13.1.9.2. Products
13.1.9.3. Company Financials
13.1.9.4. SWOT Analysis
13.1.10. STACK Infrastructure
13.1.10.1. Company Overview
13.1.10.2. Products
13.1.10.3. Company Financials
13.1.10.4. SWOT Analysis
13.1.11. Colt Data Centre Services
13.1.11.1. Company Overview
13.1.11.2. Products
13.1.11.3. Company Financials
13.1.11.4. SWOT Analysis
13.1.12. Vantage Data Centers
13.1.12.1. Company Overview
13.1.12.2. Products
13.1.12.3. Company Financials
13.1.12.4. SWOT Analysis
13.1.13. CyrusOne
13.1.13.1. Company Overview
13.1.13.2. Products
13.1.13.3. Company Financials
13.1.13.4. SWOT Analysis
13.1.14. Telehouse
13.1.14.1. Company Overview
13.1.14.2. Products
13.1.14.3. Company Financials
13.1.14.4. SWOT Analysis
13.1.15. Digital Edge
13.1.15.1. Company Overview
13.1.15.2. Products
13.1.15.3. Company Financials
13.1.15.4. SWOT Analysis
13.2. Market Entropy
13.2.1. Company's Key Areas Served
13.2.2. Recent Developments
13.3. Company Market Share Analysis, 2026
13.3.1. Top 5 Companies Market Share Analysis
13.3.2. Top 3 Companies Market Share Analysis
13.4. List of Potential Customers
List of Figures
Figure 1: Global Japan Cloud Data Center Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Kanto Japan Cloud Data Center Industry Revenue (Billion), by Data Center Size 2026 & 2034
Figure 3: Kanto Japan Cloud Data Center Industry Revenue Share (%), by Data Center Size 2026 & 2034
Figure 4: Kanto Japan Cloud Data Center Industry Revenue (Billion), by Tier Type 2026 & 2034
Figure 5: Kanto Japan Cloud Data Center Industry Revenue Share (%), by Tier Type 2026 & 2034
Figure 6: Kanto Japan Cloud Data Center Industry Revenue (Billion), by Data Center Type 2026 & 2034
Figure 7: Kanto Japan Cloud Data Center Industry Revenue Share (%), by Data Center Type 2026 & 2034
Figure 8: Kanto Japan Cloud Data Center Industry Revenue (Billion), by End User 2026 & 2034
Figure 9: Kanto Japan Cloud Data Center Industry Revenue Share (%), by End User 2026 & 2034
Figure 10: Kanto Japan Cloud Data Center Industry Revenue (Billion), by Component 2026 & 2034
Figure 11: Kanto Japan Cloud Data Center Industry Revenue Share (%), by Component 2026 & 2034
Figure 12: Kanto Japan Cloud Data Center Industry Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 13: Kanto Japan Cloud Data Center Industry Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 14: Kanto Japan Cloud Data Center Industry Revenue (Billion), by Hotspot 2026 & 2034
Figure 15: Kanto Japan Cloud Data Center Industry Revenue Share (%), by Hotspot 2026 & 2034
Figure 16: Kanto Japan Cloud Data Center Industry Revenue (Billion), by Country 2026 & 2034
Figure 17: Kanto Japan Cloud Data Center Industry Revenue Share (%), by Country 2026 & 2034
Figure 18: Kansai Japan Cloud Data Center Industry Revenue (Billion), by Data Center Size 2026 & 2034
Figure 19: Kansai Japan Cloud Data Center Industry Revenue Share (%), by Data Center Size 2026 & 2034
Figure 20: Kansai Japan Cloud Data Center Industry Revenue (Billion), by Tier Type 2026 & 2034
Figure 21: Kansai Japan Cloud Data Center Industry Revenue Share (%), by Tier Type 2026 & 2034
Figure 22: Kansai Japan Cloud Data Center Industry Revenue (Billion), by Data Center Type 2026 & 2034
Figure 23: Kansai Japan Cloud Data Center Industry Revenue Share (%), by Data Center Type 2026 & 2034
Figure 24: Kansai Japan Cloud Data Center Industry Revenue (Billion), by End User 2026 & 2034
Figure 25: Kansai Japan Cloud Data Center Industry Revenue Share (%), by End User 2026 & 2034
Figure 26: Kansai Japan Cloud Data Center Industry Revenue (Billion), by Component 2026 & 2034
Figure 27: Kansai Japan Cloud Data Center Industry Revenue Share (%), by Component 2026 & 2034
Figure 28: Kansai Japan Cloud Data Center Industry Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 29: Kansai Japan Cloud Data Center Industry Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 30: Kansai Japan Cloud Data Center Industry Revenue (Billion), by Hotspot 2026 & 2034
Figure 31: Kansai Japan Cloud Data Center Industry Revenue Share (%), by Hotspot 2026 & 2034
Figure 32: Kansai Japan Cloud Data Center Industry Revenue (Billion), by Country 2026 & 2034
Figure 33: Kansai Japan Cloud Data Center Industry Revenue Share (%), by Country 2026 & 2034
Figure 34: Chubu Japan Cloud Data Center Industry Revenue (Billion), by Data Center Size 2026 & 2034
Figure 35: Chubu Japan Cloud Data Center Industry Revenue Share (%), by Data Center Size 2026 & 2034
Figure 36: Chubu Japan Cloud Data Center Industry Revenue (Billion), by Tier Type 2026 & 2034
Figure 37: Chubu Japan Cloud Data Center Industry Revenue Share (%), by Tier Type 2026 & 2034
Figure 38: Chubu Japan Cloud Data Center Industry Revenue (Billion), by Data Center Type 2026 & 2034
Figure 39: Chubu Japan Cloud Data Center Industry Revenue Share (%), by Data Center Type 2026 & 2034
Figure 40: Chubu Japan Cloud Data Center Industry Revenue (Billion), by End User 2026 & 2034
Figure 41: Chubu Japan Cloud Data Center Industry Revenue Share (%), by End User 2026 & 2034
Figure 42: Chubu Japan Cloud Data Center Industry Revenue (Billion), by Component 2026 & 2034
Figure 43: Chubu Japan Cloud Data Center Industry Revenue Share (%), by Component 2026 & 2034
Figure 44: Chubu Japan Cloud Data Center Industry Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 45: Chubu Japan Cloud Data Center Industry Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 46: Chubu Japan Cloud Data Center Industry Revenue (Billion), by Hotspot 2026 & 2034
Figure 47: Chubu Japan Cloud Data Center Industry Revenue Share (%), by Hotspot 2026 & 2034
Figure 48: Chubu Japan Cloud Data Center Industry Revenue (Billion), by Country 2026 & 2034
Figure 49: Chubu Japan Cloud Data Center Industry Revenue Share (%), by Country 2026 & 2034
Figure 50: Kyushu Japan Cloud Data Center Industry Revenue (Billion), by Data Center Size 2026 & 2034
Figure 51: Kyushu Japan Cloud Data Center Industry Revenue Share (%), by Data Center Size 2026 & 2034
Figure 52: Kyushu Japan Cloud Data Center Industry Revenue (Billion), by Tier Type 2026 & 2034
Figure 53: Kyushu Japan Cloud Data Center Industry Revenue Share (%), by Tier Type 2026 & 2034
Figure 54: Kyushu Japan Cloud Data Center Industry Revenue (Billion), by Data Center Type 2026 & 2034
Figure 55: Kyushu Japan Cloud Data Center Industry Revenue Share (%), by Data Center Type 2026 & 2034
Figure 56: Kyushu Japan Cloud Data Center Industry Revenue (Billion), by End User 2026 & 2034
Figure 57: Kyushu Japan Cloud Data Center Industry Revenue Share (%), by End User 2026 & 2034
Figure 58: Kyushu Japan Cloud Data Center Industry Revenue (Billion), by Component 2026 & 2034
Figure 59: Kyushu Japan Cloud Data Center Industry Revenue Share (%), by Component 2026 & 2034
Figure 60: Kyushu Japan Cloud Data Center Industry Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 61: Kyushu Japan Cloud Data Center Industry Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 62: Kyushu Japan Cloud Data Center Industry Revenue (Billion), by Hotspot 2026 & 2034
Figure 63: Kyushu Japan Cloud Data Center Industry Revenue Share (%), by Hotspot 2026 & 2034
Figure 64: Kyushu Japan Cloud Data Center Industry Revenue (Billion), by Country 2026 & 2034
Figure 65: Kyushu Japan Cloud Data Center Industry Revenue Share (%), by Country 2026 & 2034
Figure 66: Tohoku Japan Cloud Data Center Industry Revenue (Billion), by Data Center Size 2026 & 2034
Figure 67: Tohoku Japan Cloud Data Center Industry Revenue Share (%), by Data Center Size 2026 & 2034
Figure 68: Tohoku Japan Cloud Data Center Industry Revenue (Billion), by Tier Type 2026 & 2034
Figure 69: Tohoku Japan Cloud Data Center Industry Revenue Share (%), by Tier Type 2026 & 2034
Figure 70: Tohoku Japan Cloud Data Center Industry Revenue (Billion), by Data Center Type 2026 & 2034
Figure 71: Tohoku Japan Cloud Data Center Industry Revenue Share (%), by Data Center Type 2026 & 2034
Figure 72: Tohoku Japan Cloud Data Center Industry Revenue (Billion), by End User 2026 & 2034
Figure 73: Tohoku Japan Cloud Data Center Industry Revenue Share (%), by End User 2026 & 2034
Figure 74: Tohoku Japan Cloud Data Center Industry Revenue (Billion), by Component 2026 & 2034
Figure 75: Tohoku Japan Cloud Data Center Industry Revenue Share (%), by Component 2026 & 2034
Figure 76: Tohoku Japan Cloud Data Center Industry Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 77: Tohoku Japan Cloud Data Center Industry Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 78: Tohoku Japan Cloud Data Center Industry Revenue (Billion), by Hotspot 2026 & 2034
Figure 79: Tohoku Japan Cloud Data Center Industry Revenue Share (%), by Hotspot 2026 & 2034
Figure 80: Tohoku Japan Cloud Data Center Industry Revenue (Billion), by Country 2026 & 2034
Figure 81: Tohoku Japan Cloud Data Center Industry Revenue Share (%), by Country 2026 & 2034
Figure 82: Hokkaido Japan Cloud Data Center Industry Revenue (Billion), by Data Center Size 2026 & 2034
Figure 83: Hokkaido Japan Cloud Data Center Industry Revenue Share (%), by Data Center Size 2026 & 2034
Figure 84: Hokkaido Japan Cloud Data Center Industry Revenue (Billion), by Tier Type 2026 & 2034
Figure 85: Hokkaido Japan Cloud Data Center Industry Revenue Share (%), by Tier Type 2026 & 2034
Figure 86: Hokkaido Japan Cloud Data Center Industry Revenue (Billion), by Data Center Type 2026 & 2034
Figure 87: Hokkaido Japan Cloud Data Center Industry Revenue Share (%), by Data Center Type 2026 & 2034
Figure 88: Hokkaido Japan Cloud Data Center Industry Revenue (Billion), by End User 2026 & 2034
Figure 89: Hokkaido Japan Cloud Data Center Industry Revenue Share (%), by End User 2026 & 2034
Figure 90: Hokkaido Japan Cloud Data Center Industry Revenue (Billion), by Component 2026 & 2034
Figure 91: Hokkaido Japan Cloud Data Center Industry Revenue Share (%), by Component 2026 & 2034
Figure 92: Hokkaido Japan Cloud Data Center Industry Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 93: Hokkaido Japan Cloud Data Center Industry Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 94: Hokkaido Japan Cloud Data Center Industry Revenue (Billion), by Hotspot 2026 & 2034
Figure 95: Hokkaido Japan Cloud Data Center Industry Revenue Share (%), by Hotspot 2026 & 2034
Figure 96: Hokkaido Japan Cloud Data Center Industry Revenue (Billion), by Country 2026 & 2034
Figure 97: Hokkaido Japan Cloud Data Center Industry Revenue Share (%), by Country 2026 & 2034
Figure 98: Chugoku Japan Cloud Data Center Industry Revenue (Billion), by Data Center Size 2026 & 2034
Figure 99: Chugoku Japan Cloud Data Center Industry Revenue Share (%), by Data Center Size 2026 & 2034
Figure 100: Chugoku Japan Cloud Data Center Industry Revenue (Billion), by Tier Type 2026 & 2034
Figure 101: Chugoku Japan Cloud Data Center Industry Revenue Share (%), by Tier Type 2026 & 2034
Figure 102: Chugoku Japan Cloud Data Center Industry Revenue (Billion), by Data Center Type 2026 & 2034
Figure 103: Chugoku Japan Cloud Data Center Industry Revenue Share (%), by Data Center Type 2026 & 2034
Figure 104: Chugoku Japan Cloud Data Center Industry Revenue (Billion), by End User 2026 & 2034
Figure 105: Chugoku Japan Cloud Data Center Industry Revenue Share (%), by End User 2026 & 2034
Figure 106: Chugoku Japan Cloud Data Center Industry Revenue (Billion), by Component 2026 & 2034
Figure 107: Chugoku Japan Cloud Data Center Industry Revenue Share (%), by Component 2026 & 2034
Figure 108: Chugoku Japan Cloud Data Center Industry Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 109: Chugoku Japan Cloud Data Center Industry Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 110: Chugoku Japan Cloud Data Center Industry Revenue (Billion), by Hotspot 2026 & 2034
Figure 111: Chugoku Japan Cloud Data Center Industry Revenue Share (%), by Hotspot 2026 & 2034
Figure 112: Chugoku Japan Cloud Data Center Industry Revenue (Billion), by Country 2026 & 2034
Figure 113: Chugoku Japan Cloud Data Center Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Japan Cloud Data Center Industry Revenue Billion Forecast, by Data Center Size 2020 & 2034
Table 2: Global Japan Cloud Data Center Industry Revenue Billion Forecast, by Tier Type 2020 & 2034
Table 3: Global Japan Cloud Data Center Industry Revenue Billion Forecast, by Data Center Type 2020 & 2034
Table 4: Global Japan Cloud Data Center Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 5: Global Japan Cloud Data Center Industry Revenue Billion Forecast, by Component 2020 & 2034
Table 6: Global Japan Cloud Data Center Industry Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 7: Global Japan Cloud Data Center Industry Revenue Billion Forecast, by Hotspot 2020 & 2034
Table 8: Global Japan Cloud Data Center Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 9: Kanto Japan Cloud Data Center Industry Revenue Billion Forecast, by Data Center Size 2020 & 2034
Table 10: Kanto Japan Cloud Data Center Industry Revenue Billion Forecast, by Tier Type 2020 & 2034
Table 11: Kanto Japan Cloud Data Center Industry Revenue Billion Forecast, by Data Center Type 2020 & 2034
Table 12: Kanto Japan Cloud Data Center Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 13: Kanto Japan Cloud Data Center Industry Revenue Billion Forecast, by Component 2020 & 2034
Table 14: Kanto Japan Cloud Data Center Industry Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 15: Kanto Japan Cloud Data Center Industry Revenue Billion Forecast, by Hotspot 2020 & 2034
Table 16: Kanto Japan Cloud Data Center Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 17: Tokyo Japan Cloud Data Center Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: Inzai Japan Cloud Data Center Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 19: Chiba Japan Cloud Data Center Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: Kansai Japan Cloud Data Center Industry Revenue Billion Forecast, by Data Center Size 2020 & 2034
Table 21: Kansai Japan Cloud Data Center Industry Revenue Billion Forecast, by Tier Type 2020 & 2034
Table 22: Kansai Japan Cloud Data Center Industry Revenue Billion Forecast, by Data Center Type 2020 & 2034
Table 23: Kansai Japan Cloud Data Center Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 24: Kansai Japan Cloud Data Center Industry Revenue Billion Forecast, by Component 2020 & 2034
Table 25: Kansai Japan Cloud Data Center Industry Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 26: Kansai Japan Cloud Data Center Industry Revenue Billion Forecast, by Hotspot 2020 & 2034
Table 27: Kansai Japan Cloud Data Center Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 28: Osaka Japan Cloud Data Center Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Hyogo Japan Cloud Data Center Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: Chubu Japan Cloud Data Center Industry Revenue Billion Forecast, by Data Center Size 2020 & 2034
Table 31: Chubu Japan Cloud Data Center Industry Revenue Billion Forecast, by Tier Type 2020 & 2034
Table 32: Chubu Japan Cloud Data Center Industry Revenue Billion Forecast, by Data Center Type 2020 & 2034
Table 33: Chubu Japan Cloud Data Center Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 34: Chubu Japan Cloud Data Center Industry Revenue Billion Forecast, by Component 2020 & 2034
Table 35: Chubu Japan Cloud Data Center Industry Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 36: Chubu Japan Cloud Data Center Industry Revenue Billion Forecast, by Hotspot 2020 & 2034
Table 37: Chubu Japan Cloud Data Center Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 38: Aichi Japan Cloud Data Center Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: Shizuoka Japan Cloud Data Center Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: Kyushu Japan Cloud Data Center Industry Revenue Billion Forecast, by Data Center Size 2020 & 2034
Table 41: Kyushu Japan Cloud Data Center Industry Revenue Billion Forecast, by Tier Type 2020 & 2034
Table 42: Kyushu Japan Cloud Data Center Industry Revenue Billion Forecast, by Data Center Type 2020 & 2034
Table 43: Kyushu Japan Cloud Data Center Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 44: Kyushu Japan Cloud Data Center Industry Revenue Billion Forecast, by Component 2020 & 2034
Table 45: Kyushu Japan Cloud Data Center Industry Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 46: Kyushu Japan Cloud Data Center Industry Revenue Billion Forecast, by Hotspot 2020 & 2034
Table 47: Kyushu Japan Cloud Data Center Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 48: Fukuoka Japan Cloud Data Center Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 49: Tohoku Japan Cloud Data Center Industry Revenue Billion Forecast, by Data Center Size 2020 & 2034
Table 50: Tohoku Japan Cloud Data Center Industry Revenue Billion Forecast, by Tier Type 2020 & 2034
Table 51: Tohoku Japan Cloud Data Center Industry Revenue Billion Forecast, by Data Center Type 2020 & 2034
Table 52: Tohoku Japan Cloud Data Center Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 53: Tohoku Japan Cloud Data Center Industry Revenue Billion Forecast, by Component 2020 & 2034
Table 54: Tohoku Japan Cloud Data Center Industry Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 55: Tohoku Japan Cloud Data Center Industry Revenue Billion Forecast, by Hotspot 2020 & 2034
Table 56: Tohoku Japan Cloud Data Center Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 57: Hokkaido Japan Cloud Data Center Industry Revenue Billion Forecast, by Data Center Size 2020 & 2034
Table 58: Hokkaido Japan Cloud Data Center Industry Revenue Billion Forecast, by Tier Type 2020 & 2034
Table 59: Hokkaido Japan Cloud Data Center Industry Revenue Billion Forecast, by Data Center Type 2020 & 2034
Table 60: Hokkaido Japan Cloud Data Center Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 61: Hokkaido Japan Cloud Data Center Industry Revenue Billion Forecast, by Component 2020 & 2034
Table 62: Hokkaido Japan Cloud Data Center Industry Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 63: Hokkaido Japan Cloud Data Center Industry Revenue Billion Forecast, by Hotspot 2020 & 2034
Table 64: Hokkaido Japan Cloud Data Center Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 65: Chugoku Japan Cloud Data Center Industry Revenue Billion Forecast, by Data Center Size 2020 & 2034
Table 66: Chugoku Japan Cloud Data Center Industry Revenue Billion Forecast, by Tier Type 2020 & 2034
Table 67: Chugoku Japan Cloud Data Center Industry Revenue Billion Forecast, by Data Center Type 2020 & 2034
Table 68: Chugoku Japan Cloud Data Center Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 69: Chugoku Japan Cloud Data Center Industry Revenue Billion Forecast, by Component 2020 & 2034
Table 70: Chugoku Japan Cloud Data Center Industry Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 71: Chugoku Japan Cloud Data Center Industry Revenue Billion Forecast, by Hotspot 2020 & 2034
Table 72: Chugoku Japan Cloud Data Center Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 73: Hiroshima Japan Cloud Data Center Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the Japan cloud data center industry market size in 2026?
The market is valued at USD 11.89 billion in 2026, based on our proprietary primary research and facility-level capacity audits. It is projected to reach USD 17.66 billion by 2031 at a CAGR of 8.22%.
2Which region dominates the Japan data center market?
The Kanto region, anchored by Tokyo, accounts for 43.6% of national data center capacity and Tokyo alone represents 40.7% of market share. Osaka is the fastest-growing hotspot at 13.28% CAGR.
3What is the fastest-growing end-user segment in Japan's data center market?
The BFSI segment is forecast to grow at 16.05% CAGR between 2026 and 2031, driven by megabank modernization and data residency compliance requirements.
4Who are the major players in the Japan cloud data center industry?
Leading operators include NTT Ltd, Equinix, Digital Realty Trust, IDC Frontier (SoftBank Group), NEC Corporation, AirTrunk, AT TOKYO, STACK Infrastructure, Colt Data Centre Services, Vantage Data Centers and CyrusOne.
5Why is colocation dominant in Japan's data center market?
Colocation holds 79.3% of market value because enterprise self-built rooms average 15 years of age and fail modern seismic and efficiency codes. Tier 3 colocation delivers 99.982% uptime at 20-30% lower operating expense than on-premise halls.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conducted 180+ in-depth interviews across the Japan cloud data center value chain, split approximately 75% primary to 25% secondary research input.
Interviewed company types include colocation and wholesale data center operators, hyperscale cloud platform providers, enterprise end-users (BFSI, IT/telecom, manufacturing), MEP and construction contractors, and power utility and interconnect providers.
Stakeholder designations interviewed include Chief Data Center Officer / VP Infrastructure, Head of Data Center Operations, Procurement and Sourcing Director, and Real Estate & Site Selection Lead.
Interviews validated facility-level IT load, power allocation, pricing, utilization and expansion pipelines.
Primary findings were triangulated against official governmental and multilateral datasets, including Statistics Bureau of Japan, Ministry of Internal Affairs and Communications, Ministry of Economy Trade and Industry, OECD, and World Bank ICT indicators.
Industry benchmarks were sourced from recognized non-profit technical and trade associations, including Uptime Institute tier standards and the Japan Data Center Council, alongside NISC cybersecurity framework guidance.
Financial filings and transaction data were cross-checked using Bloomberg, Factiva, Hoovers and PitchBook.
Demand Modeling & Market Estimation
We deployed simultaneous top-down and bottom-up methodologies, reconciled through multi-level data triangulation.
Bottom-up market sizing was built from facility-level IT load capacity (MW), utilized white floor area (sq. ft.), utilized rack counts, and average revenue per MW, aggregated across 219 facilities and validated against colocation revenue of USD 6.70 billion by 2031.
Top-down validation used national ICT investment, cloud adoption rates, and power capacity forecasts of 610 MW by 2031.
Data Accuracy & Quality Check
Every report is updated to the date of purchase, incorporating the latest facility commissioning, investment announcements and power allocation data.
We guarantee an estimated data accuracy level of 85-90%, achieved through multi-level triangulation, primary interview verification and outlier reconciliation.
All estimates are reviewed by a senior industry analyst panel prior to publication, and segment shares are cross-validated against operator disclosures.