1What is the size of the e-paper display signage market in 2025?
The global e-paper display signage market was valued at USD 2.01 Billion in 2025, up from USD 1.82 Billion in 2024, according to our proprietary bottom-up modeling.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 E-paper Display Signage Market
 by Application (Retail, Transportation, Corporate, Healthcare, Education), by Technology (E-paper Display, Electrophoretic Displays, Electrowetting Displays, Microcapsule Technology), by End Use (Advertising, Information Displays, Menu Boards, Wayfinding), by Display Size (Small, Medium, Large, Extra Large), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Asia Pacific (China, Japan, South Korea), by South America, by Middle East & Africa Forecast 2026-2034

Senior Research Analyst

 Related Reports

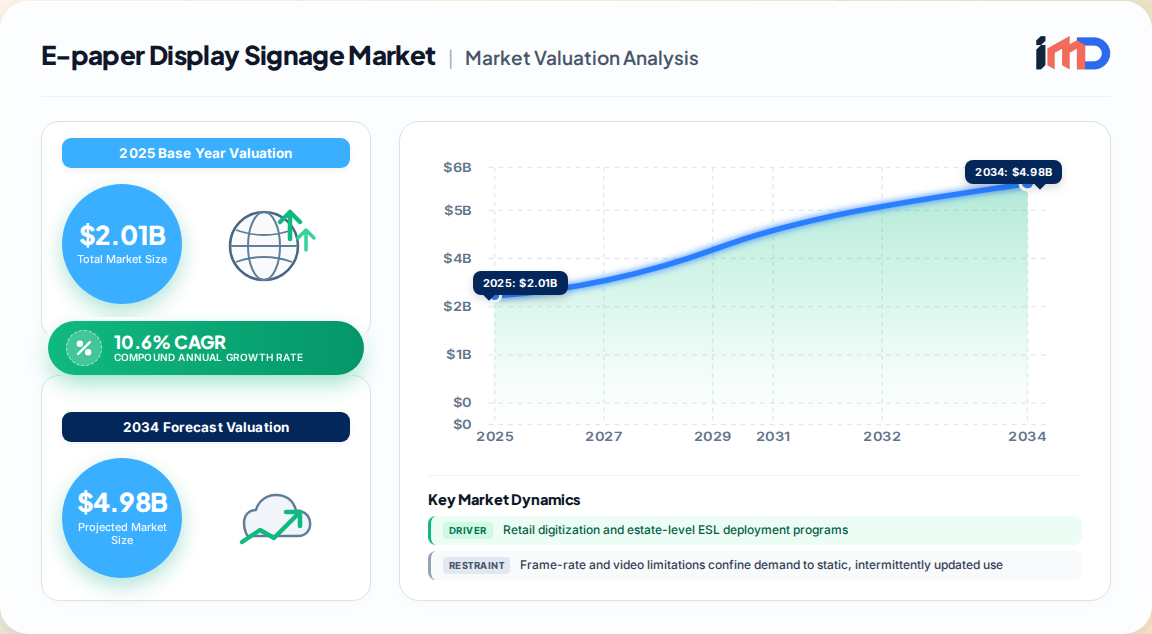
The global E-paper Display Signage Market was valued at USD 2.01 Billion in 2025 and is projected to reach USD 5.5 Billion by 2035, expanding at a 10.6% CAGR across the 2026–2035 forecast window. This segment represents the fastest-commercializing frontier of reflective display technology, moving from pilot installations toward estate-level deployment in retail, transportation, corporate, healthcare, and education environments.
Unlike video-centric digital signage built on LCD or OLED architectures, e-paper signage monetizes a distinct operating logic: persistent image retention, ambient-light readability, and near-zero standby power draw. Our proprietary bottom-up modeling shows that roughly 83% of total e-paper display value in 2025 derived from electrophoretic technology, the dominant architecture underpinning signage deployments.
| Metric | 2025 | 2026 | 2035 |
|---|---|---|---|
| Market Value (Signage Segment) | USD 2.01 Billion | USD 2.22 Billion | USD 5.5 Billion |
| Implied CAGR (2026–2035) | — | — | 10.6% |
| Parent E-paper Display Market | USD 3.7 Billion | USD 4.4 Billion | USD 18.0 Billion |
Signage remains a minority but disproportionately strategic slice of the broader e-paper display universe. Its share of parent-market value is set to rise as retail digitization programs shift from isolated pilots to multi-thousand-store rollouts.
The e-paper signage value chain is concentrated at the electrophoretic film layer and fragmented downstream.
| Stage | Characteristics | Margin Profile |
|---|---|---|
| Electronic ink / film | Highly concentrated; one dominant supplier held over 65.7% share in 2025 | High |
| Panel and module assembly | Regional panel makers and specialists; moderate competition | Moderate |
| Wireless infrastructure | Gateways, access points, protocol stacks | Moderate |
| System integration & CMS software | Fragmented; differentiation via software and service | Moderate to high |
| Installation & managed service | Localized; labor-intensive | Variable |
Our analyst view: top five players collectively held 89.3% of the parent market in 2025, but integrators retain room to compete on connectivity, software, installation capability, and service models rather than panel economics. Record-holder financial disclosures show the parent supplier's IoT applications revenue reached USD 12.9 billion-equivalent scale within its consumer and IoT split, evidencing the shift from e-reader cycles toward infrastructure-grade deployments.
E-paper signage is a traded physical product with a concentrated upstream and globally distributed downstream. Trade flows mirror electronics manufacturing geography.
By application, retail dominates value on the strength of ESL and promotional signage convergence, followed by transportation, corporate wayfinding, healthcare, and education. By technology, electrophoretic displays account for the overwhelming majority of value, with electrowetting and microcapsule-adjacent approaches occupying niche positions. By display size, small and medium formats dominate unit volume through shelf-edge and label use cases, while large and extra-large formats carry higher value per endpoint in wayfinding and public information.
By end use, information displays and wayfinding represent the most defensible demand pools because they replace recurring operational activity rather than adding a display feature. Menu boards and advertising remain growth-optional, contingent on color technology advancement.
| Segment Axis | Leading Segment | Fastest-Growing Segment |
|---|---|---|
| Application | Retail | Transportation / Healthcare |
| Technology | Electrophoretic | Color e-paper variants |
| Display size | Small/medium | Large/extra large |
| End use | Information displays | Wayfinding |
North America leads revenue generation, supported by advanced retail automation, strong logistics and transportation adoption, and high digital signage penetration. Asia-Pacific is the fastest-growing region, propelled by retail digitization, a deep electronics manufacturing base, smart city programs, and expanding e-reader ecosystems. Europe exhibits mature, sustainability-driven demand with strong regulatory tailwinds for low-power display technology. South America and Middle East & Africa remain emerging but show credible pilot-stage traction in retail and public information.
The competitive field spans display material suppliers, panel makers, ESL system vendors, and signage integrators. Strategically, the most consequential battles are fought in three arenas: panel qualification reliability, wireless-system compatibility, and cost per installed endpoint.
Our estimate of growth from USD 2.01 Billion in 2025 to USD 5.5 Billion by 2035 rests primarily on applications where signage replaces recurring operating activity. The 10.6% CAGR masks a technology boundary: e-paper signage wins on persistence and power economics, not on visual dynamism. Vendors that engineer their go-to-market around operational savings, wireless reliability, and installed-endpoint economics will capture the disproportionate share of this expansion.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.6% from 2020-2034 |
| Segmentation |
|
By End Use
By Display Size
| By Geography |
|
The global e-paper display signage market was valued at USD 2.01 Billion in 2025, up from USD 1.82 Billion in 2024, according to our proprietary bottom-up modeling.
The market is projected to expand at a 10.6% CAGR between 2026 and 2035, reaching USD 5.5 Billion by the end of the forecast period.
North America generates the highest revenue, driven by advanced retail automation and transportation adoption, while Asia-Pacific is the fastest-growing region on the strength of retail digitization and manufacturing depth.
Retail dominates, as electronic shelf labels and promotional signage converge into networked store operating systems that replace manual price-change workflows.
Electrophoretic technology accounted for roughly 83% of total e-paper display market value in 2025, underpinning the majority of shelf-edge, wayfinding, and information signage installations.
Key players include E Ink Holdings, Sharp, LG Electronics, Samsung, Panasonic, NEC Display Solutions, Advantech, ViewSonic, Planar Systems, and VusionGroup, among others.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Display Procurement Manager | 35% |
| Chief Technology Officer | 25% |
| Director of Retail Operations | 25% |
| Smart City Program Manager | 15% |
| Company Type | Representation (%) |
|---|---|
| Panel & Module Manufacturers | 30% |
| ESL & Signage System Vendors | 25% |
| Installation & Managed-Service Integrators | 20% |
| E-ink Film & Material Suppliers | 15% |
| Wireless Infrastructure Providers | 10% |