1What is the size of the defense industry market in 2026?
The global defense industry market is valued at USD 542.72 billion in 2026 and is projected to reach USD 739.43 billion by 2030, growing at a CAGR of 8.0%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Defense Industry
 by Sector (Defense, Aerospace), by Platform (Aerial, Terrestrial, Naval, Space), by Service Type (Manufacturing, Maintenance Repair and Overhaul (MRO)), by Component (Airframes and Structures, Propulsion Systems and Engines, Electronics and Mission Systems, Composite and Carbon Fibre Components), by North America (USA, Canada), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, South Korea, India), by Middle East & Africa (Saudi Arabia, UAE, Israel), by South America (Brazil) Forecast 2026-2034

Research Associate


 Related Reports

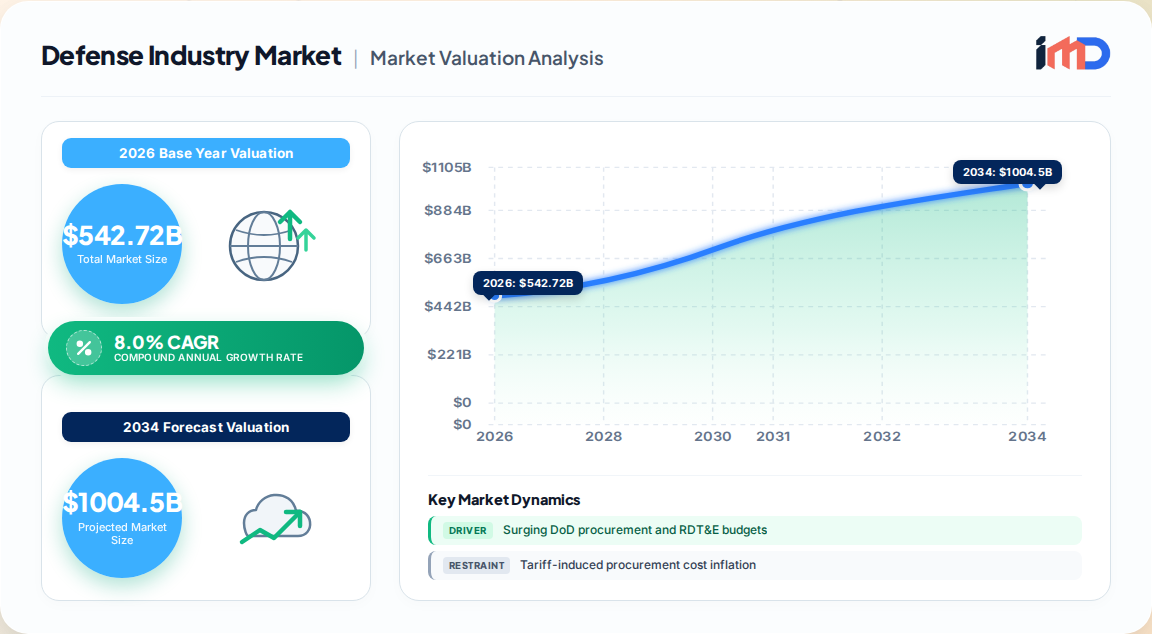
Our proprietary primary research places the global defense industry market at USD 542.72 billion in 2026, expanding to USD 739.43 billion by 2030 at a CAGR of 8.0%. This trajectory is anchored by record global military expenditure of USD 2.44 trillion in 2023, a 6.8% real-terms increase year-on-year. The defense sector is no longer a cyclical procurement story—it is a structural rearmament cycle, driven by geopolitical fragmentation, multi-domain warfare readiness, and an urgent push for "speed to field" across AI-enabled systems.
The defense industry market is shaped by deeply integrated transatlantic and allied supply chains. In 2024, EU member states represented two of the top five export destinations and seven of the top ten import countries of origin for the U.S. aerospace and defense industry.
| Supply Chain Node | Key Geography | Strategic Risk | Mitigation Trend |
|---|---|---|---|
| Titanium and rare-earth magnets | U.S., Australia, Japan | Geopolitical concentration | DPA Title III domestic expansion |
| Wide-bandgap semiconductors | U.S., Taiwan, South Korea | Foundry dependency | CHIPS Act aerospace-grade fabs |
| Composite aerostructures | U.S., Europe | Quality-control repatriation | Spirit AeroSystems Wichita reshoring |
| Naval propulsion and castings | U.S., EU, Japan | Single-source fragility | Multi-year supplier qualification |
| Satellite buses and payloads | U.S., Europe, India | Launch access | Commercial rideshare and LEO diversification |
The defense industry value chain is migrating from linear, platform-centric production to a networked, software-intensive model.
| Value Chain Stage | Primary Activities | Margin Profile | Key Trends |
|---|---|---|---|
| R&D and Design | Hypersonics, AI-enabled mission systems, digital twins | High | Agentic AI for simulation and decision advantage |
| Tier 3–2 Suppliers | Raw materials, components, electronics | Low–Medium | Reshoring, CMMC compliance |
| Tier 1 Systems Integrators | Airframes, propulsion, mission systems | Medium–High | Multi-year contracts, backlog conversion |
| Primes and OEMs | Platform assembly, integration, test | High | Software-defined upgrades, MRO capture |
| Sustainment and MRO | Maintenance, repair, overhaul, upgrades | Medium–High | Digital MRO twins, predictive maintenance |
The defense industry market is characterized by medium concentration, with primes dominating platform integration while venture-backed entrants target autonomous systems, EW, and niche space applications.
| Existing Markets | New Markets | |
|---|---|---|
| Existing Products | Market penetration: Multi-year procurement, FMS expansions | Market development: Indo-Pacific and Middle East offsets |
| New Products | Product development: Autonomous fighter jets, hypersonics, EW | Diversification: Commercial space, dual-use AI, cyber defense |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.0% from 2020-2034 |
| Segmentation |
|
By Service Type
By Component
| By Geography |
|
The global defense industry market is valued at USD 542.72 billion in 2026 and is projected to reach USD 739.43 billion by 2030, growing at a CAGR of 8.0%.
Western Europe is forecast to be the fastest-growing region, driven by NATO burden-sharing commitments and EU defense procurement simplification, while Asia-Pacific remains the largest market.
Key trends include autonomous fighter jets, AI-enabled mission systems, space-based defense constellations, digital MRO twins, and supply-chain reshoring for critical materials like titanium and rare-earth magnets.
Major players include Lockheed Martin, RTX Corporation, Northrop Grumman, General Dynamics, The Boeing Company, BAE Systems, L3Harris Technologies, Leonardo SpA, Thales Group, and Huntington Ingalls Industries.
Tariffs on aircraft components, naval systems, and electronic subsystems are increasing procurement costs and disrupting cross-border sourcing, while also accelerating domestic manufacturing and local defense supply-chain resilience.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Procurement Officer | 30% |
| Program Director (Defense Platforms) | 28% |
| Supply Chain Director | 24% |
| Government Contracting Officer | 18% |
| Company Type | Representation (%) |
|---|---|
| Airframe and Propulsion OEMs | 30% |
| Mission Systems and Electronics Suppliers | 22% |
| Autonomous Systems and UAV Developers | 18% |
| Naval Shipbuilders | 15% |
| Defense MRO Providers | 15% |