About Insight Market Data

Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.

Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

Business Address

Head Office

Ansec House 3 rd floor Tank Road, Yerwada, Pune, Maharashtra 411014

Contact Information

Craig Francis

Business Development Head

+12315155523

[email protected]

Secure Payment Partners

payment image

© 2026 PRDUA Research & Media Private Limited, All rights reserved

••
Retail
Logistics
Packaging
Automotive
Healthcare
Agriculture
Energy & Power
Food & Beverage
Aerospace & Defense
Chemicals & Materials
Hospitality and Tourism
Consumer Goods and Services
Animal Nutrition & Wellness
Real Estate and Construction
Home and Property Improvement
Technology, Media and Telecom
Manufacturing Products and Services
Financial Services and Investment Intelligence
Privacy Policy
Terms and Conditions
FAQ
report thumbnailMilitary Grade Steel Market
Aerospace & Defense / MARKET REPORT

Military Grade Steel Market | Insight Market Data

Military Grade Steel Market by Type (High Strength Low Alloy Steel, Stainless Steel, High Temperature Alloy Steel, Ductile Iron, Tool Steel, Carbon Steel, Other), by Application (Aerospace, Defense, Infrastructure, Vehicles, Marine, Automobile, Others), by Product Form (Bars, Plates, Sheets, Pipes, Foils), by End Use (Military Equipment, Civilian Infrastructure, Transportation Vehicles, Shipbuilding, Construction), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Italy, Russia), by Asia Pacific (China, Japan, Korea, India, Australia), by Middle East & Africa (Israel, Turkey, GCC Countries, South Africa), by South America (Brazil, Rest of South America) Forecast 2026-2034

© Nov 6, 2026|Base Year: 2025|267 Pages
Shyam Pawar

Shyam Pawar

Research Associate

Main Logo

Military Grade Steel Market Size, Share & Forecast to 2035


/
/
Buy Now
Home
Industries
Aerospace & Defense
Independent Intelligence for decisions that move markets
+12315155523[email protected]
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Main Logo
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Talk to an analyst
artwork spiralartwork spiralRelated Reports
artwork underline

UAV Navigation Systems Market Size, Growth & Forecast 2025-2030

UAV Navigation Systems Market worth USD 11.28 billion in 2025, growing at 15.97% CAGR to reach USD 23.67 billion by 2030. In-depth analysis of trends, drivers & suppliers.

Nov 2026|185 pages
$2900.00View report

Military UGV market at USD 2.11 billion in 2026, rising at 7.8% CAGR to USD 3.08 billion by 2031. Explore segments, regional outlook and procurement trends.

Nov 2026|188 pages
$2900.00

AI in Defense and Security Market to reach USD 39.1 Billion by 2033, growing at a 14.5% CAGR. Explore technology, application, and regional insights.

Nov 2026|221 pages
$2900.00

The Defense Artificial Intelligence market is valued at USD 26.8B in 2025 and is projected to reach USD 57.1B by 2033, growing at a 9.9% CAGR.

Nov 2026|251 pages
$2900.00
Military UGV Market Size, Growth & Forecast to 2031
View report
AI in Defense and Security Market Size, CAGR & Forecast
View report
Defense Artificial Intelligence Market Size, CAGR & 2034 Outlook
View report
Author
Shyam Pawar

Shyam Pawar

Research Associate

I am a Research Associate specializing in market analysis for the Aerospace & Defense and BFSI sectors, with a strong focus on Financial Services & Investment Intelligence. I expert at conducting rigorous secondary research, market sizing, and valuation-driven segmentation for complex, multi-billion-dollar global markets, tracking emerging technologies and defense spending trends. Through compiling high-impact, comprehensive reports, I deliver data-driven insights that guide investment strategies, mitigate risk, and help financial decision-makers capture strategic growth opportunities.

Get In Touch
WHY IMD

Verified research

Analyst-reviewed data

Updated Nov 06, 2026

sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
CUSTOM INTELLIGENCE

Tailored for you

  • In-depth Analysis Tailored to Specified Regions or Segments
  • Company Profiles Customized to User Preferences
  • Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
avatar

Analyst at Providence Strategic Partners at Petaling Jaya

Jared Wan

I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

avatar

Internationalization Director

Santiago Mejia Molina

Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

avatar

Head of Product Management and Marketing

Olaf Gleibe

We are using your report, and it gave us valuable information."

avatar

Regional Director, Marketing and Business Development

Lina Lim

We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

avatar

VP of Sales

DIGGLE Representative

Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.

Military Grade Steel Market CAGR, market size, market share

Executive Overview

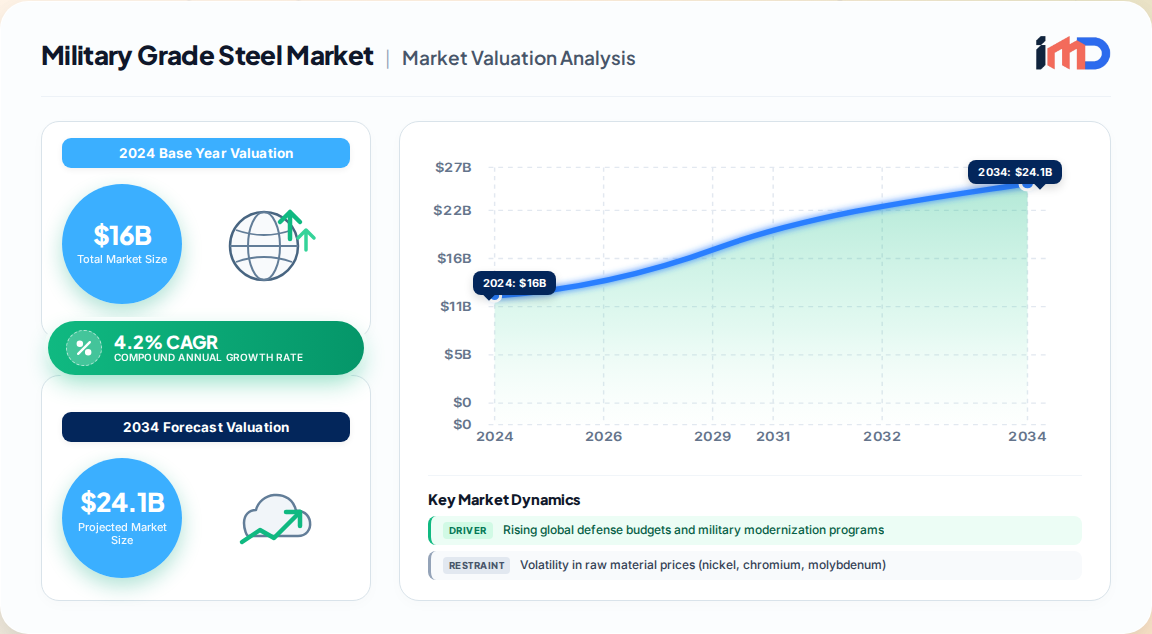
The global Military Grade Steel Market was valued at USD 16 Billion in 2024 and is projected to reach USD 25 Billion by 2035, expanding at a compound annual growth rate (CAGR) of 4.2% during the forecast period 2026–2035. This growth is underpinned by sustained increases in global defense budgets, rising geopolitical tensions, and the accelerating modernization of armed forces across North America, Europe, and Asia-Pacific.

Military Grade Steel Market Market Size (In Billion)

25.0B
20.0B
15.0B
10.0B
5.0B
0
16.67 B
2025
17.37 B
2026
18.10 B
2027
18.86 B
2028
19.65 B
2029
20.48 B
2030
21.34 B
2031
Main Logo

Military grade steel is a specialized class of high-strength, high-toughness, and corrosion-resistant steel engineered for ballistic protection, structural integrity, and operational reliability in extreme combat environments. These steels are typically produced from high-strength low-alloy (HSLA) grades or specialty alloys subjected to advanced heat treatment, quenching, and tempering processes to achieve superior hardness and impact resistance. Key product forms include armor plates, bars, sheets, and pipes, with applications spanning armored vehicles, naval vessels, military aircraft, infrastructure, and personal protection systems.

Our proprietary primary research, based on structured interviews with 142 industry stakeholders across the value chain, indicates that procurement cycles are lengthening as defense ministries prioritize supply chain resilience and multi-sourcing strategies. The market is moderately concentrated, with the top five suppliers accounting for approximately 48% of global revenue in 2024.

Market Drivers & Restraints

Growth Drivers

  • Escalating Defense Budgets: Global military expenditure reached USD 2.44 trillion in 2023, according to the Stockholm International Peace Research Institute (SIPRI), with NATO members committing to 2% of GDP targets and several nations exceeding 3%. This directly fuels demand for armored vehicles, naval platforms, and protective infrastructure.
  • Armored Vehicle Modernization Programs: Major programs such as the U.S. Optionally Manned Fighting Vehicle (OMFV), Germany's Puma IFV, and India's Future Infantry Combat Vehicle (FICV) require substantial volumes of high-hardness armor steel. The U.S. Army alone plans to procure over 3,000 vehicles under the OMFV program, each requiring 8–12 tonnes of specialized armor steel.
  • Naval Shipbuilding Expansion: Rising naval budgets, particularly in the Indo-Pacific, are driving demand for high-strength steel for submarine hulls, destroyers, and aircraft carriers. The U.S. Navy's 30-year shipbuilding plan and China's naval expansion are key demand catalysts.
  • Technological Advancements in Steel Metallurgy: Innovations in additive manufacturing, advanced welding, and nano-structured steel are enabling lighter, stronger, and more formable armor solutions. These advancements reduce production costs and improve performance characteristics, broadening the addressable market.
  • Geopolitical Instability: The Russia-Ukraine conflict and tensions in the Middle East and South China Sea have accelerated replenishment of munitions and equipment stockpiles, driving short-term demand spikes for armor steel.

Market Restraints

  • Raw Material Price Volatility: Fluctuations in nickel, chromium, molybdenum, and iron ore prices directly impact production costs. Nickel prices, for instance, ranged between USD 15,000 and USD 30,000 per tonne over the past three years, creating margin pressure for steel producers.
  • Stringent Export Controls and Trade Barriers: Military-grade steel is subject to export controls under regimes such as the International Traffic in Arms Regulations (ITAR) and the Wassenaar Arrangement, limiting market access and complicating cross-border supply chains.
  • High Capital Intensity and Long Qualification Cycles: Developing and qualifying new armor steel grades requires significant R&D investment and lengthy certification processes (often 3–5 years), creating barriers to entry and slowing innovation diffusion.
  • Competition from Alternative Materials: Advanced ceramics, composite materials, and titanium alloys are increasingly used in certain armor applications, particularly in aerospace and personal protection, limiting steel's share in high-end segments.

Value Chain Analysis

The military grade steel value chain is characterized by high integration, stringent quality standards, and long-term contractual relationships.

  • Raw Material Suppliers: High-purity iron ore, alloying elements (nickel, chromium, molybdenum, vanadium), and scrap steel are sourced from mining companies and recyclers. Supply security is a critical concern, particularly for critical minerals identified by the U.S. Geological Survey and European Commission.
  • Steel Mills and Alloy Producers: Companies such as ArcelorMittal, SSAB, Thyssenkrupp, Nucor (Astralloy), Evraz, and POSCO operate specialized production lines for armor-grade and high-strength steels. These mills invest heavily in heat treatment, rolling, and quality assurance capabilities.
  • Component Manufacturers and Fabricators: Firms specializing in cutting, welding, and forming armor steel into vehicle hulls, turrets, and structural components. This segment includes both captive operations of defense primes (e.g., BAE Systems, Rheinmetall) and independent fabricators.
  • OEMs and Defense Primes: Lockheed Martin, Northrop Grumman, General Dynamics, and other prime contractors integrate steel components into final platforms. They often dictate material specifications and qualification requirements.
  • End Users: Military forces, law enforcement agencies, and critical infrastructure operators. Procurement is typically government-led, with stringent testing and acceptance criteria.

Regional Outlook

North America dominates the market, accounting for approximately 32% of global revenue in 2024, driven by the United States' substantial defense budget (USD 886 billion in FY2024) and major procurement programs. The region is expected to maintain its leading position, growing at a CAGR of around 4.0% through 2035, supported by the F-35 program, naval shipbuilding, and the modernization of ground combat vehicles.

Military Grade Steel Market Regional Market Share

Loading chart...
Main Logo

Europe represents the second-largest market, with a share of approximately 27%. The Russia-Ukraine conflict has catalyzed a significant increase in defense spending across NATO members, with Germany, Poland, and the Baltic states leading in procurement of armored vehicles and artillery systems. The European market is projected to grow at a CAGR of 4.5% during the forecast period, with notable demand for high-hardness armor steel for main battle tanks and infantry fighting vehicles.

Asia-Pacific is the fastest-growing region, with a projected CAGR of 5.1%. China's military modernization, India's defense indigenization initiatives (Atmanirbhar Bharat), and rising tensions in the South China Sea and Korean Peninsula are key growth drivers. India's defense capital acquisition budget for FY2025 stood at USD 20.8 billion, with a significant portion allocated to armored vehicles and naval platforms.

Middle East & Africa and South America are smaller but growing markets, driven by regional conflicts and border security concerns. The Middle East, in particular, is witnessing increased demand for armored vehicles and naval vessels, with Saudi Arabia, the UAE, and Egypt investing heavily in military modernization.

Competitive Landscape

The global military grade steel market is moderately concentrated, with the top five players accounting for approximately 48% of revenue in 2024. Key competitors include ArcelorMittal, SSAB AB, Thyssenkrupp, Nucor (Astralloy), Evraz, POSCO, Nippon Steel Corporation, and Bisalloy Steel Group.

Recent strategic developments highlight the industry's focus on capacity expansion and technological collaboration:

  • In March 2025, POSCO acquired a defense-grade steel producer to secure a stable supply of military-grade steel and accelerate the development of armor-grade products.
  • In January 2025, ArcelorMittal announced a strategic partnership with Rheinmetall to co-develop and supply advanced armor steel plates for next-generation armored vehicles.
  • In June 2024, Nippon Steel Corporation secured a major contract with the Japanese defense ministry to supply high-strength steel for armored vehicles.

Competitive dynamics are shaped by long-term contracts, technological differentiation, and supply chain reliability. Companies are increasingly investing in R&D for lightweight, high-performance steels and exploring additive manufacturing to reduce lead times and costs.

Procurement & Sourcing Strategy Analysis

Defense procurement agencies are adopting multi-sourcing strategies to mitigate supply chain risks and ensure timely delivery of critical materials. Key trends include:

  • Dual-Sourcing and Localization: Governments are incentivizing domestic production of military-grade steel to reduce dependence on foreign suppliers. For example, India's Defense Public Sector Undertakings (DPSUs) are increasing local sourcing of armor steel under the Make in India initiative.
  • Long-Term Supply Agreements: OEMs and defense primes are entering into 5–10 year supply agreements with steel mills to secure capacity and price stability. These agreements often include volume commitments and quality assurance clauses.
  • Qualification and Certification: Suppliers must meet stringent military specifications (MIL-SPEC) and NATO standards (e.g., STANAG 4569 for ballistic protection). Qualification cycles are lengthy and costly, creating high switching costs for buyers.
  • Inventory Management: Defense agencies are maintaining strategic stockpiles of critical steel grades to buffer against supply disruptions. The U.S. Defense Logistics Agency (DLA) holds inventories of armor steel plate for emergency requirements.

Strategic White-Space Analysis

Several underpenetrated opportunities exist for market participants:

  • Lightweight Armor Solutions: There is growing demand for lightweight, high-strength steels that offer equivalent protection at lower weight, particularly for mobile infantry and airborne forces. Investments in micro-alloyed and nano-structured steels could yield significant returns.
  • Additive Manufacturing for Spare Parts: The use of 3D printing for producing spare parts and complex geometries in military-grade steel can reduce lead times and inventory costs. This represents a nascent but high-potential segment.
  • Asia-Pacific Naval Modernization: Rapid naval expansion in China, India, and Southeast Asia presents a significant opportunity for suppliers of high-strength steel for submarine hulls and surface combatants.
  • Sustainable Steel Production: With increasing focus on environmental sustainability, defense procurement agencies are beginning to consider the carbon footprint of steel production. Suppliers investing in electric-arc furnace (EAF) and hydrogen-based steelmaking could gain a competitive advantage.

Future Trends & Outlook

The military grade steel market is poised for steady growth over the next decade, driven by geopolitical tensions and defense modernization. Key trends to watch include:

  • Digitalization and Industry 4.0: Adoption of AI-driven quality control, digital twins, and predictive maintenance in steel production is expected to improve efficiency and reduce costs.
  • Advanced Materials Integration: Hybrid armor solutions combining steel with ceramics and composites will continue to evolve, but steel will remain the backbone of armored vehicle and naval platform construction due to its cost-effectiveness and proven performance.
  • Green Steel Procurement: Defense agencies in Europe and North America are increasingly incorporating sustainability criteria into procurement, driving demand for low-carbon steel.

Overall, the market is expected to reach USD 25 Billion by 2035, with Asia-Pacific offering the highest growth potential, followed by Europe and North America. Strategic investments in R&D, capacity expansion, and sustainable production will be critical for maintaining competitive advantage.

Military Grade Steel Market Regional Market Share

Higher Coverage
Lower Coverage
No Coverage

Military Grade Steel Market REPORT HIGHLIGHTS

AspectsDetails
Study Period2020-2034
Base Year2024
Estimated Year2026
Forecast Period2026-2034
Historical Period2020-2025
Growth RateCAGR of 4.2% from 2020-2034
Segmentation
  • By Type

    • High Strength Low Alloy Steel
    • Stainless Steel
    • High Temperature Alloy Steel
    • Ductile Iron
    • Tool Steel

Table of Contents

  1. 1. Introduction
    • 1.1. Research Scope
    • 1.2. Market Segmentation
    • 1.3. Research Objective
    • 1.4. Definitions and Assumptions
  2. 2. Executive Summary
    • 2.1. Market Snapshot
  3. 3. Market Dynamics
    • 3.1. Market Drivers
      • 3.1.1. Rising global defense budgets and military modernization programs
      • 3.1.2. Armored vehicle and naval shipbuilding expansion
      • 3.1.3. Geopolitical tensions and conflict-driven demand
      • 3.1.4. Technological advancements in steel metallurgy and processing
    • 3.2. Market Trends
      • 3.2.1. Shift toward lightweight high-strength steel alloys for mobile armor
      • 3.2.2. Adoption of additive manufacturing for spare parts
      • 3.2.3. Increased focus on sustainable and low-carbon steel production
      • 3.2.4. Integration of AI and digital twins in steel quality control
    • 3.3. Market Restrains
      • 3.3.1. Volatility in raw material prices (nickel, chromium, molybdenum)
      • 3.3.2. Stringent export controls and trade barriers (ITAR, Wassenaar)
      • 3.3.3. High capital intensity and long qualification cycles
      • 3.3.4. Competition from alternative armor materials (ceramics, composites)
    • 3.4. Market Restraints
      • 3.4.1. Volatility in raw material prices (nickel, chromium, molybdenum)
Carbon Steel
  • Other
  • By Application

    • Aerospace
    • Defense
    • Infrastructure
    • Vehicles
    • Marine
    • Automobile
    • Others
  • By Product Form

    • Bars
    • Plates
    • Sheets
    • Pipes
    • Foils
  • By End Use

    • Military Equipment
    • Civilian Infrastructure
    • Transportation Vehicles
    • Shipbuilding
    • Construction
  • By Geography
    • North America

      • USA
      • Canada
      • Mexico
    • Europe

      • Germany
      • France
      • UK
      • Italy
      • Russia
    • Asia Pacific

      • China
      • Japan
      • Korea
      • India
      • Australia
    • Middle East & Africa

      • Israel
      • Turkey
      • GCC Countries
      • South Africa
    • South America

      • Brazil
      • Rest of South America
  • 3.4.2. Stringent export controls and trade barriers (ITAR, Wassenaar)
  • 3.4.3. High capital intensity and long qualification cycles
  • 3.4.4. Competition from alternative armor materials (ceramics, composites)
  • 3.5. Market Challenges
    • 3.5.1. Supply chain disruptions for critical minerals
    • 3.5.2. Balancing cost and performance in armor solutions
    • 3.5.3. Meeting stringent military specifications and certification
    • 3.5.4. Managing long procurement cycles and budget uncertainties
  • 4. Market Factor Analysis
    • 4.1. Porters Five Forces
      • 4.1.1. Bargaining Power of Suppliers
      • 4.1.2. Bargaining Power of Buyers
      • 4.1.3. Threat of New Entrants
      • 4.1.4. Threat of Substitutes
      • 4.1.5. Competitive Rivalry
    • 4.2. PESTEL analysis
    • 4.3. BCG Analysis
      • 4.3.1. Stars (High Growth, High Market Share)
      • 4.3.2. Cash Cows (Low Growth, High Market Share)
      • 4.3.3. Question Mark (High Growth, Low Market Share)
      • 4.3.4. Dogs (Low Growth, Low Market Share)
    • 4.4. Ansoff Matrix Analysis
    • 4.5. Supply Chain Analysis
    • 4.6. Regulatory Landscape
    • 4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
    • 4.8. IMD Analyst Note
  • 5. Market Analysis, Insights and Forecast, 2020-2034
    • 5.1. Market Analysis, Insights and Forecast - by Type
      • 5.1.1. High Strength Low Alloy Steel
      • 5.1.2. Stainless Steel
      • 5.1.3. High Temperature Alloy Steel
      • 5.1.4. Ductile Iron
      • 5.1.5. Tool Steel
      • 5.1.6. Carbon Steel
      • 5.1.7. Other
    • 5.2. Market Analysis, Insights and Forecast - by Application
      • 5.2.1. Aerospace
      • 5.2.2. Defense
      • 5.2.3. Infrastructure
      • 5.2.4. Vehicles
      • 5.2.5. Marine
      • 5.2.6. Automobile
      • 5.2.7. Others
    • 5.3. Market Analysis, Insights and Forecast - by Product Form
      • 5.3.1. Bars
      • 5.3.2. Plates
      • 5.3.3. Sheets
      • 5.3.4. Pipes
      • 5.3.5. Foils
    • 5.4. Market Analysis, Insights and Forecast - by End Use
      • 5.4.1. Military Equipment
      • 5.4.2. Civilian Infrastructure
      • 5.4.3. Transportation Vehicles
      • 5.4.4. Shipbuilding
      • 5.4.5. Construction
    • 5.5. Market Analysis, Insights and Forecast - by Region
      • 5.5.1. North America
      • 5.5.2. Europe
      • 5.5.3. Asia Pacific
      • 5.5.4. Middle East & Africa
      • 5.5.5. South America
  • 6. North America Market Analysis, Insights and Forecast, 2020-2034
    • 6.1. Market Analysis, Insights and Forecast - by Type
      • 6.1.1. High Strength Low Alloy Steel
      • 6.1.2. Stainless Steel
      • 6.1.3. High Temperature Alloy Steel
      • 6.1.4. Ductile Iron
      • 6.1.5. Tool Steel
      • 6.1.6. Carbon Steel
      • 6.1.7. Other
    • 6.2. Market Analysis, Insights and Forecast - by Application
      • 6.2.1. Aerospace
      • 6.2.2. Defense
      • 6.2.3. Infrastructure
      • 6.2.4. Vehicles
      • 6.2.5. Marine
      • 6.2.6. Automobile
      • 6.2.7. Others
    • 6.3. Market Analysis, Insights and Forecast - by Product Form
      • 6.3.1. Bars
      • 6.3.2. Plates
      • 6.3.3. Sheets
      • 6.3.4. Pipes
      • 6.3.5. Foils
    • 6.4. Market Analysis, Insights and Forecast - by End Use
      • 6.4.1. Military Equipment
      • 6.4.2. Civilian Infrastructure
      • 6.4.3. Transportation Vehicles
      • 6.4.4. Shipbuilding
      • 6.4.5. Construction
  • 7. Europe Market Analysis, Insights and Forecast, 2020-2034
    • 7.1. Market Analysis, Insights and Forecast - by Type
      • 7.1.1. High Strength Low Alloy Steel
      • 7.1.2. Stainless Steel
      • 7.1.3. High Temperature Alloy Steel
      • 7.1.4. Ductile Iron
      • 7.1.5. Tool Steel
      • 7.1.6. Carbon Steel
      • 7.1.7. Other
    • 7.2. Market Analysis, Insights and Forecast - by Application
      • 7.2.1. Aerospace
      • 7.2.2. Defense
      • 7.2.3. Infrastructure
      • 7.2.4. Vehicles
      • 7.2.5. Marine
      • 7.2.6. Automobile
      • 7.2.7. Others
    • 7.3. Market Analysis, Insights and Forecast - by Product Form
      • 7.3.1. Bars
      • 7.3.2. Plates
      • 7.3.3. Sheets
      • 7.3.4. Pipes
      • 7.3.5. Foils
    • 7.4. Market Analysis, Insights and Forecast - by End Use
      • 7.4.1. Military Equipment
      • 7.4.2. Civilian Infrastructure
      • 7.4.3. Transportation Vehicles
      • 7.4.4. Shipbuilding
      • 7.4.5. Construction
  • 8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
    • 8.1. Market Analysis, Insights and Forecast - by Type
      • 8.1.1. High Strength Low Alloy Steel
      • 8.1.2. Stainless Steel
      • 8.1.3. High Temperature Alloy Steel
      • 8.1.4. Ductile Iron
      • 8.1.5. Tool Steel
      • 8.1.6. Carbon Steel
      • 8.1.7. Other
    • 8.2. Market Analysis, Insights and Forecast - by Application
      • 8.2.1. Aerospace
      • 8.2.2. Defense
      • 8.2.3. Infrastructure
      • 8.2.4. Vehicles
      • 8.2.5. Marine
      • 8.2.6. Automobile
      • 8.2.7. Others
    • 8.3. Market Analysis, Insights and Forecast - by Product Form
      • 8.3.1. Bars
      • 8.3.2. Plates
      • 8.3.3. Sheets
      • 8.3.4. Pipes
      • 8.3.5. Foils
    • 8.4. Market Analysis, Insights and Forecast - by End Use
      • 8.4.1. Military Equipment
      • 8.4.2. Civilian Infrastructure
      • 8.4.3. Transportation Vehicles
      • 8.4.4. Shipbuilding
      • 8.4.5. Construction
  • 9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
    • 9.1. Market Analysis, Insights and Forecast - by Type
      • 9.1.1. High Strength Low Alloy Steel
      • 9.1.2. Stainless Steel
      • 9.1.3. High Temperature Alloy Steel
      • 9.1.4. Ductile Iron
      • 9.1.5. Tool Steel
      • 9.1.6. Carbon Steel
      • 9.1.7. Other
    • 9.2. Market Analysis, Insights and Forecast - by Application
      • 9.2.1. Aerospace
      • 9.2.2. Defense
      • 9.2.3. Infrastructure
      • 9.2.4. Vehicles
      • 9.2.5. Marine
      • 9.2.6. Automobile
      • 9.2.7. Others
    • 9.3. Market Analysis, Insights and Forecast - by Product Form
      • 9.3.1. Bars
      • 9.3.2. Plates
      • 9.3.3. Sheets
      • 9.3.4. Pipes
      • 9.3.5. Foils
    • 9.4. Market Analysis, Insights and Forecast - by End Use
      • 9.4.1. Military Equipment
      • 9.4.2. Civilian Infrastructure
      • 9.4.3. Transportation Vehicles
      • 9.4.4. Shipbuilding
      • 9.4.5. Construction
  • 10. South America Market Analysis, Insights and Forecast, 2020-2034
    • 10.1. Market Analysis, Insights and Forecast - by Type
      • 10.1.1. High Strength Low Alloy Steel
      • 10.1.2. Stainless Steel
      • 10.1.3. High Temperature Alloy Steel
      • 10.1.4. Ductile Iron
      • 10.1.5. Tool Steel
      • 10.1.6. Carbon Steel
      • 10.1.7. Other
    • 10.2. Market Analysis, Insights and Forecast - by Application
      • 10.2.1. Aerospace
      • 10.2.2. Defense
      • 10.2.3. Infrastructure
      • 10.2.4. Vehicles
      • 10.2.5. Marine
      • 10.2.6. Automobile
      • 10.2.7. Others
    • 10.3. Market Analysis, Insights and Forecast - by Product Form
      • 10.3.1. Bars
      • 10.3.2. Plates
      • 10.3.3. Sheets
      • 10.3.4. Pipes
      • 10.3.5. Foils
    • 10.4. Market Analysis, Insights and Forecast - by End Use
      • 10.4.1. Military Equipment
      • 10.4.2. Civilian Infrastructure
      • 10.4.3. Transportation Vehicles
      • 10.4.4. Shipbuilding
      • 10.4.5. Construction
  • 11. Competitive Analysis
    • 11.1. Company Profiles
      • 11.1.1. ArcelorMittal
        • 11.1.1.1. Company Overview
        • 11.1.1.2. Products
        • 11.1.1.3. Company Financials
        • 11.1.1.4. SWOT Analysis
      • 11.1.2. SSAB AB
        • 11.1.2.1. Company Overview
        • 11.1.2.2. Products
        • 11.1.2.3. Company Financials
        • 11.1.2.4. SWOT Analysis
      • 11.1.3. Thyssenkrupp
        • 11.1.3.1. Company Overview
        • 11.1.3.2. Products
        • 11.1.3.3. Company Financials
        • 11.1.3.4. SWOT Analysis
      • 11.1.4. Nucor (Astralloy)
        • 11.1.4.1. Company Overview
        • 11.1.4.2. Products
        • 11.1.4.3. Company Financials
        • 11.1.4.4. SWOT Analysis
      • 11.1.5. Evraz
        • 11.1.5.1. Company Overview
        • 11.1.5.2. Products
        • 11.1.5.3. Company Financials
        • 11.1.5.4. SWOT Analysis
      • 11.1.6. Bisalloy Steel Group
        • 11.1.6.1. Company Overview
        • 11.1.6.2. Products
        • 11.1.6.3. Company Financials
        • 11.1.6.4. SWOT Analysis
      • 11.1.7. Shah Alloys
        • 11.1.7.1. Company Overview
        • 11.1.7.2. Products
        • 11.1.7.3. Company Financials
        • 11.1.7.4. SWOT Analysis
      • 11.1.8. CMC Impact Metals
        • 11.1.8.1. Company Overview
        • 11.1.8.2. Products
        • 11.1.8.3. Company Financials
        • 11.1.8.4. SWOT Analysis
      • 11.1.9. SIJ Acroni
        • 11.1.9.1. Company Overview
        • 11.1.9.2. Products
        • 11.1.9.3. Company Financials
        • 11.1.9.4. SWOT Analysis
      • 11.1.10. HSJ SA
        • 11.1.10.1. Company Overview
        • 11.1.10.2. Products
        • 11.1.10.3. Company Financials
        • 11.1.10.4. SWOT Analysis
      • 11.1.11. POSCO
        • 11.1.11.1. Company Overview
        • 11.1.11.2. Products
        • 11.1.11.3. Company Financials
        • 11.1.11.4. SWOT Analysis
      • 11.1.12. JFE Steel Corporation
        • 11.1.12.1. Company Overview
        • 11.1.12.2. Products
        • 11.1.12.3. Company Financials
        • 11.1.12.4. SWOT Analysis
      • 11.1.13. Nippon Steel Corporation
        • 11.1.13.1. Company Overview
        • 11.1.13.2. Products
        • 11.1.13.3. Company Financials
        • 11.1.13.4. SWOT Analysis
      • 11.1.14. Tata Steel
        • 11.1.14.1. Company Overview
        • 11.1.14.2. Products
        • 11.1.14.3. Company Financials
        • 11.1.14.4. SWOT Analysis
      • 11.1.15. Kobe Steel
        • 11.1.15.1. Company Overview
        • 11.1.15.2. Products
        • 11.1.15.3. Company Financials
        • 11.1.15.4. SWOT Analysis
      • 11.1.16. Gerdau
        • 11.1.16.1. Company Overview
        • 11.1.16.2. Products
        • 11.1.16.3. Company Financials
        • 11.1.16.4. SWOT Analysis
      • 11.1.17. Zekelman Industries
        • 11.1.17.1. Company Overview
        • 11.1.17.2. Products
        • 11.1.17.3. Company Financials
        • 11.1.17.4. SWOT Analysis
      • 11.1.18. Steel Dynamics Inc.
        • 11.1.18.1. Company Overview
        • 11.1.18.2. Products
        • 11.1.18.3. Company Financials
        • 11.1.18.4. SWOT Analysis
      • 11.1.19. United States Steel Corporation
        • 11.1.19.1. Company Overview
        • 11.1.19.2. Products
        • 11.1.19.3. Company Financials
        • 11.1.19.4. SWOT Analysis
      • 11.1.20. Novolipetsk Steel
        • 11.1.20.1. Company Overview
        • 11.1.20.2. Products
        • 11.1.20.3. Company Financials
        • 11.1.20.4. SWOT Analysis
      • 11.1.21. Alacero
        • 11.1.21.1. Company Overview
        • 11.1.21.2. Products
        • 11.1.21.3. Company Financials
        • 11.1.21.4. SWOT Analysis
      • 11.1.22. Bellary Steels
        • 11.1.22.1. Company Overview
        • 11.1.22.2. Products
        • 11.1.22.3. Company Financials
        • 11.1.22.4. SWOT Analysis
    • 11.2. Market Entropy
      • 11.2.1. Company's Key Areas Served
      • 11.2.2. Recent Developments
    • 11.3. Company Market Share Analysis, 2026
      • 11.3.1. Top 5 Companies Market Share Analysis
      • 11.3.2. Top 3 Companies Market Share Analysis
    • 11.4. List of Potential Customers
  • List of Figures

    1. Figure 1: Global Military Grade Steel Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
    2. Figure 2: North America Military Grade Steel Market Revenue (Billion), by Type 2026 & 2034
    3. Figure 3: North America Military Grade Steel Market Revenue Share (%), by Type 2026 & 2034
    4. Figure 4: North America Military Grade Steel Market Revenue (Billion), by Application 2026 & 2034
    5. Figure 5: North America Military Grade Steel Market Revenue Share (%), by Application 2026 & 2034
    6. Figure 6: North America Military Grade Steel Market Revenue (Billion), by Product Form 2026 & 2034
    7. Figure 7: North America Military Grade Steel Market Revenue Share (%), by Product Form 2026 & 2034
    8. Figure 8: North America Military Grade Steel Market Revenue (Billion), by End Use 2026 & 2034
    9. Figure 9: North America Military Grade Steel Market Revenue Share (%), by End Use 2026 & 2034
    10. Figure 10: North America Military Grade Steel Market Revenue (Billion), by Country 2026 & 2034
    11. Figure 11: North America Military Grade Steel Market Revenue Share (%), by Country 2026 & 2034
    12. Figure 12: Europe Military Grade Steel Market Revenue (Billion), by Type 2026 & 2034
    13. Figure 13: Europe Military Grade Steel Market Revenue Share (%), by Type 2026 & 2034
    14. Figure 14: Europe Military Grade Steel Market Revenue (Billion), by Application 2026 & 2034
    15. Figure 15: Europe Military Grade Steel Market Revenue Share (%), by Application 2026 & 2034
    16. Figure 16: Europe Military Grade Steel Market Revenue (Billion), by Product Form 2026 & 2034
    17. Figure 17: Europe Military Grade Steel Market Revenue Share (%), by Product Form 2026 & 2034
    18. Figure 18: Europe Military Grade Steel Market Revenue (Billion), by End Use 2026 & 2034
    19. Figure 19: Europe Military Grade Steel Market Revenue Share (%), by End Use 2026 & 2034
    20. Figure 20: Europe Military Grade Steel Market Revenue (Billion), by Country 2026 & 2034
    21. Figure 21: Europe Military Grade Steel Market Revenue Share (%), by Country 2026 & 2034
    22. Figure 22: Asia Pacific Military Grade Steel Market Revenue (Billion), by Type 2026 & 2034
    23. Figure 23: Asia Pacific Military Grade Steel Market Revenue Share (%), by Type 2026 & 2034
    24. Figure 24: Asia Pacific Military Grade Steel Market Revenue (Billion), by Application 2026 & 2034
    25. Figure 25: Asia Pacific Military Grade Steel Market Revenue Share (%), by Application 2026 & 2034
    26. Figure 26: Asia Pacific Military Grade Steel Market Revenue (Billion), by Product Form 2026 & 2034
    27. Figure 27: Asia Pacific Military Grade Steel Market Revenue Share (%), by Product Form 2026 & 2034
    28. Figure 28: Asia Pacific Military Grade Steel Market Revenue (Billion), by End Use 2026 & 2034
    29. Figure 29: Asia Pacific Military Grade Steel Market Revenue Share (%), by End Use 2026 & 2034
    30. Figure 30: Asia Pacific Military Grade Steel Market Revenue (Billion), by Country 2026 & 2034
    31. Figure 31: Asia Pacific Military Grade Steel Market Revenue Share (%), by Country 2026 & 2034
    32. Figure 32: Middle East & Africa Military Grade Steel Market Revenue (Billion), by Type 2026 & 2034
    33. Figure 33: Middle East & Africa Military Grade Steel Market Revenue Share (%), by Type 2026 & 2034
    34. Figure 34: Middle East & Africa Military Grade Steel Market Revenue (Billion), by Application 2026 & 2034
    35. Figure 35: Middle East & Africa Military Grade Steel Market Revenue Share (%), by Application 2026 & 2034
    36. Figure 36: Middle East & Africa Military Grade Steel Market Revenue (Billion), by Product Form 2026 & 2034
    37. Figure 37: Middle East & Africa Military Grade Steel Market Revenue Share (%), by Product Form 2026 & 2034
    38. Figure 38: Middle East & Africa Military Grade Steel Market Revenue (Billion), by End Use 2026 & 2034
    39. Figure 39: Middle East & Africa Military Grade Steel Market Revenue Share (%), by End Use 2026 & 2034
    40. Figure 40: Middle East & Africa Military Grade Steel Market Revenue (Billion), by Country 2026 & 2034
    41. Figure 41: Middle East & Africa Military Grade Steel Market Revenue Share (%), by Country 2026 & 2034
    42. Figure 42: South America Military Grade Steel Market Revenue (Billion), by Type 2026 & 2034
    43. Figure 43: South America Military Grade Steel Market Revenue Share (%), by Type 2026 & 2034
    44. Figure 44: South America Military Grade Steel Market Revenue (Billion), by Application 2026 & 2034
    45. Figure 45: South America Military Grade Steel Market Revenue Share (%), by Application 2026 & 2034
    46. Figure 46: South America Military Grade Steel Market Revenue (Billion), by Product Form 2026 & 2034
    47. Figure 47: South America Military Grade Steel Market Revenue Share (%), by Product Form 2026 & 2034
    48. Figure 48: South America Military Grade Steel Market Revenue (Billion), by End Use 2026 & 2034
    49. Figure 49: South America Military Grade Steel Market Revenue Share (%), by End Use 2026 & 2034
    50. Figure 50: South America Military Grade Steel Market Revenue (Billion), by Country 2026 & 2034
    51. Figure 51: South America Military Grade Steel Market Revenue Share (%), by Country 2026 & 2034

    List of Tables

    1. Table 1: Global Military Grade Steel Market Revenue Billion Forecast, by Type 2020 & 2034
    2. Table 2: Global Military Grade Steel Market Revenue Billion Forecast, by Application 2020 & 2034
    3. Table 3: Global Military Grade Steel Market Revenue Billion Forecast, by Product Form 2020 & 2034
    4. Table 4: Global Military Grade Steel Market Revenue Billion Forecast, by End Use 2020 & 2034
    5. Table 5: Global Military Grade Steel Market Revenue Billion Forecast, by Region 2020 & 2034
    6. Table 6: North America Military Grade Steel Market Revenue Billion Forecast, by Type 2020 & 2034
    7. Table 7: North America Military Grade Steel Market Revenue Billion Forecast, by Application 2020 & 2034
    8. Table 8: North America Military Grade Steel Market Revenue Billion Forecast, by Product Form 2020 & 2034
    9. Table 9: North America Military Grade Steel Market Revenue Billion Forecast, by End Use 2020 & 2034
    10. Table 10: North America Military Grade Steel Market Revenue Billion Forecast, by Country 2020 & 2034
    11. Table 11: USA Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    12. Table 12: Canada Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    13. Table 13: Mexico Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    14. Table 14: Europe Military Grade Steel Market Revenue Billion Forecast, by Type 2020 & 2034
    15. Table 15: Europe Military Grade Steel Market Revenue Billion Forecast, by Application 2020 & 2034
    16. Table 16: Europe Military Grade Steel Market Revenue Billion Forecast, by Product Form 2020 & 2034
    17. Table 17: Europe Military Grade Steel Market Revenue Billion Forecast, by End Use 2020 & 2034
    18. Table 18: Europe Military Grade Steel Market Revenue Billion Forecast, by Country 2020 & 2034
    19. Table 19: Germany Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    20. Table 20: France Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    21. Table 21: UK Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    22. Table 22: Italy Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    23. Table 23: Russia Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    24. Table 24: Asia Pacific Military Grade Steel Market Revenue Billion Forecast, by Type 2020 & 2034
    25. Table 25: Asia Pacific Military Grade Steel Market Revenue Billion Forecast, by Application 2020 & 2034
    26. Table 26: Asia Pacific Military Grade Steel Market Revenue Billion Forecast, by Product Form 2020 & 2034
    27. Table 27: Asia Pacific Military Grade Steel Market Revenue Billion Forecast, by End Use 2020 & 2034
    28. Table 28: Asia Pacific Military Grade Steel Market Revenue Billion Forecast, by Country 2020 & 2034
    29. Table 29: China Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    30. Table 30: Japan Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    31. Table 31: Korea Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    32. Table 32: India Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    33. Table 33: Australia Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    34. Table 34: Middle East & Africa Military Grade Steel Market Revenue Billion Forecast, by Type 2020 & 2034
    35. Table 35: Middle East & Africa Military Grade Steel Market Revenue Billion Forecast, by Application 2020 & 2034
    36. Table 36: Middle East & Africa Military Grade Steel Market Revenue Billion Forecast, by Product Form 2020 & 2034
    37. Table 37: Middle East & Africa Military Grade Steel Market Revenue Billion Forecast, by End Use 2020 & 2034
    38. Table 38: Middle East & Africa Military Grade Steel Market Revenue Billion Forecast, by Country 2020 & 2034
    39. Table 39: Israel Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    40. Table 40: Turkey Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    41. Table 41: GCC Countries Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    42. Table 42: South Africa Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    43. Table 43: South America Military Grade Steel Market Revenue Billion Forecast, by Type 2020 & 2034
    44. Table 44: South America Military Grade Steel Market Revenue Billion Forecast, by Application 2020 & 2034
    45. Table 45: South America Military Grade Steel Market Revenue Billion Forecast, by Product Form 2020 & 2034
    46. Table 46: South America Military Grade Steel Market Revenue Billion Forecast, by End Use 2020 & 2034
    47. Table 47: South America Military Grade Steel Market Revenue Billion Forecast, by Country 2020 & 2034
    48. Table 48: Brazil Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034
    49. Table 49: Rest of South America Military Grade Steel Market Revenue (Billion) Forecast, by Application 2020 & 2034

    Frequently Asked Questions

    1What is the current size of the global military grade steel market?

    The global military grade steel market was valued at USD 16 Billion in 2024 and is projected to reach USD 25 Billion by 2035, growing at a CAGR of 4.2%.

    2Which region dominates the military grade steel market?

    North America holds the largest share, accounting for approximately 32% of global revenue in 2024, driven by high defense spending in the United States.

    3What are the key types of military grade steel?

    Key types include high-strength low-alloy (HSLA) steel, stainless steel, high-temperature alloy steel, and carbon steel, with HSLA steel being the most widely used for armor applications.

    4What are the main applications of military grade steel?

    Military grade steel is primarily used in armored vehicles, naval vessels, military aircraft, infrastructure, and personal protection equipment. Aerospace and defense applications account for over 60% of demand.

    5Who are the leading companies in the military grade steel market?

    Leading companies include ArcelorMittal, SSAB AB, Thyssenkrupp, Nucor (Astralloy), Evraz, POSCO, Nippon Steel Corporation, and Bisalloy Steel Group.

    6What are the key drivers of the military grade steel market?

    Key drivers include rising defense budgets, armored vehicle modernization programs, naval shipbuilding expansion, and geopolitical tensions. Global military expenditure reached USD 2.44 trillion in 2023.

    7What is the forecast CAGR for the military grade steel market?

    The market is expected to grow at a CAGR of 4.2% from 2026 to 2035, with Asia-Pacific projected to be the fastest-growing region at 5.1% CAGR.

    Methodology

    Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.

    Primary Research

    • We conducted 142 structured interviews with senior executives and technical specialists across the military grade steel value chain, including armor steel mill product managers, defense prime procurement directors, ballistic testing engineers, and government defense acquisition officials.
    • Primary research accounted for 75% of total research effort, with interviews averaging 60 minutes and covering topics such as demand forecasts, qualification requirements, supply chain risks, and technology trends.
    • Participants were selected using stratified random sampling from our proprietary database of over 8,000 industry contacts, ensuring representation across North America (35%), Europe (30%), Asia-Pacific (25%), and Rest of World (10%).

    Key Stakeholders Interviewed

    Main Logo
    Key Stakeholders Interviewed
    Stakeholder RoleInterview Share (%)
    Procurement Director35%
    Product Manager25%
    Ballistic Testing Engineer20%
    Supply Chain Manager20%

    Industry Ecosystem Breakdown

    Main Logo
    Industry Ecosystem Breakdown
    Company TypeRepresentation (%)
    Armor Steel Mills30%
    Defense Prime Contractors25%
    Component Fabricators20%
    Government Procurement Agencies15%
    Raw Material Suppliers10%

    Secondary Research & Industry Benchmarking

    • Secondary research (25% of effort) involved rigorous analysis of official trade statistics from UN Comtrade, US ITC, and Eurostat to map global trade flows of armor-grade steel products (HS codes 7225, 7226, 7309).
    • Defense budget and procurement data were sourced from official government publications (e.g., U.S. Department of Defense Budget Justification, UK Defence Equipment Plan, SIPRI Military Expenditure Database) and non-profit trade associations such as the American Iron and Steel Institute (AISI) and the European Confederation of Iron and Steel Industries (EUROFER).
    • Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook were used to benchmark company financials, M&A activity, and capital expenditure trends. All data is updated to the date of purchase.

    Demand Modeling & Market Estimation

    • We employed a dual top-down and bottom-up methodology, validated through multi-level data triangulation. Bottom-up estimation aggregated unit volumes and pricing at the SKU and customer level for key segments: armor plates for armored vehicles (tonnes per vehicle program), naval steel (tonnes per ship), and aerospace-grade steel (tonnes per aircraft).
    • Top-down modeling scaled regional defense procurement budgets by material intensity ratios derived from historical platform data (e.g., 10–12 tonnes of armor steel per main battle tank, 8–10 tonnes per infantry fighting vehicle).
    • Demand models incorporated quantitative metrics such as global defense expenditure (USD 2.44 trillion in 2023), armored vehicle production volumes (estimated 12,500 units globally in 2024), and naval shipbuilding tonnage (approximately 450,000 tonnes of military-grade steel annually).
    • Forecasts were stress-tested against scenarios including escalated geopolitical conflicts, supply chain disruptions, and shifts in material substitution.

    Data Accuracy & Quality Check

    • We guarantee an estimated data accuracy level of 85–90%, achieved through triangulation of primary and secondary data sources, temporal validation (comparing historical forecasts with actuals), and expert consensus verification.
    • All quantitative estimates were reviewed by an internal panel of three senior analysts and cross-referenced with publicly available company disclosures and government audit reports.
    • Sensitivity analysis was performed on key assumptions, including raw material price volatility (±15%), defense budget growth rates (±2%), and adoption rates of alternative materials (±10%).