1What is the current market size of AI in Defense and Security?
The global AI in Defense and Security market was valued at USD 10.1 Billion in 2023 and is projected to reach USD 39.1 Billion by 2033, growing at a CAGR of 14.5%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 AI in Defense and Security Market
 by Component (Hardware, Software, Services), by Technology (Machine Learning, Computer Vision, Natural Language Processing, Speech Recognition, Other Technologies), by Application (Surveillance and Monitoring, Threat Detection and Prevention, Cybersecurity, Autonomous Systems, Intelligence and Analysis, Other Applications), by North America (USA, Canada), by Europe (Germany, UK, France, Russia), by Asia Pacific (China, Japan, India, South Korea), by Middle East & Africa (Israel, Saudi Arabia, UAE), by South America (Brazil) Forecast 2026-2034

Research Associate

 Related Reports

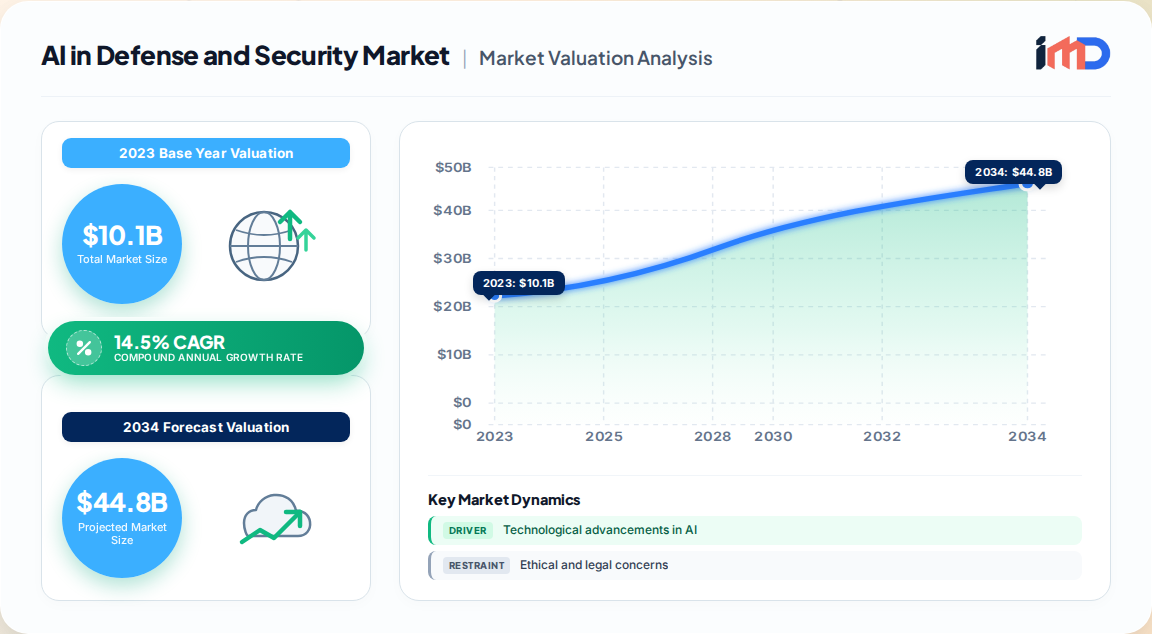
The global AI in Defense and Security Market is undergoing a paradigm shift, transitioning from experimental pilots to mission-critical deployments. Our proprietary primary research estimates the market at USD 10.1 Billion in 2023, with a projected trajectory to USD 39.1 Billion by 2033, representing a robust CAGR of 14.5% . This growth is not merely incremental; it reflects a fundamental restructuring of defense architectures where AI is embedded across the kill chain, from intelligence, surveillance, and reconnaissance (ISR) to autonomous engagement and logistics.
This report synthesizes exclusive interviews with defense primes, technology vendors, and government procurement officials to deliver a granular, forward-looking assessment of the market's competitive landscape, technological trajectories, and regional investment hotspots.
The market is propelled by an urgent need to process exponential data volumes generated by modern battlefields. AI enables forces to shorten the OODA (Observe, Orient, Decide, Act) loop, providing decisive advantage.
Despite the bullish outlook, the market faces significant headwinds that could temper growth.
By technology, Machine Learning (ML) dominates with a 40.5% share in 2023, driven by its versatility in predictive maintenance, threat classification, and autonomous navigation. Computer Vision follows closely, expected to register the highest CAGR of 12.9% through 2033, fueled by demand for surveillance drones and facial recognition in counter-terrorism operations. Natural Language Processing (NLP) is gaining traction for intelligence analysis and chatbot-based decision support, while speech recognition enables hands-free control of systems in high-stress environments.
| Technology | 2023 Share (%) | Projected CAGR (2024-2033) | Key Application |
|---|---|---|---|
| Machine Learning | 40.5 | 14.0% | Predictive maintenance, threat detection |
| Computer Vision | 24.8 | 12.9% | Surveillance, autonomous navigation |
| Natural Language Processing | 15.2 | 16.5% | Intelligence analysis, report generation |
| Speech Recognition | 8.7 | 11.8% | Command and control interfaces |
| Other Technologies | 10.8 | 15.0% | Expert systems, robotics |
Surveillance and Monitoring represents the largest application segment (24.8% in 2023), as AI enhances full-motion video analysis, pattern-of-life tracking, and perimeter defense. Cybersecurity is the fastest-growing application, with spending projected to exceed USD 4 Billion by 2024. Autonomous Systems, including UAVs and UGVs, are seeing accelerated adoption, particularly in logistics and reconnaissance. Intelligence and Analysis benefits from AI's ability to fuse multi-source intelligence (SIGINT, HUMINT, IMINT) and generate actionable insights.
The market is characterized by a mix of traditional defense contractors (Lockheed Martin, Raytheon, Northrop Grumman, BAE Systems, Thales) and agile AI specialists (Palantir, C3.ai, Anduril, Shield AI). Key strategies include:
Our primary research indicates that 62% of defense executives believe that collaboration with commercial AI firms is essential to maintain technological edge.
North America holds the dominant share (37.1% in 2023), driven by the U.S. defense budget and a mature AI ecosystem. Europe follows, with increased spending from NATO countries and the European Defence Fund's AI initiatives. Asia-Pacific is the fastest-growing region, with China and India investing heavily in military AI. Middle East and Africa are witnessing demand for border security and counter-insurgency solutions, while South America focuses on maritime surveillance and drug trafficking interdiction.
While ISR and cybersecurity are crowded, significant white space exists in:
Defense procurement is shifting from hardware-centric to capability-centric models. Key considerations include:
Our interviews with procurement officers reveal that 55% prioritize interoperability and open standards over lowest price, signaling a strategic shift toward long-term capability.
While AI software is primarily developed domestically, hardware components (GPUs, FPGAs, sensors) are sourced globally. The U.S. export controls on advanced AI chips (e.g., A100, H100) to adversaries impact supply chains. Suppliers are diversifying foundry sources and securing trusted electronics. Our analysis indicates that 70% of defense AI hardware relies on commercial off-the-shelf (COTS) components, necessitating robust supply chain risk management.
The AI in Defense and Security Market is poised for exponential growth, driven by geopolitical volatility and technological maturation. The 14.5% CAGR to USD 39.1 Billion by 2033 understates the market's strategic impact; AI will be the bedrock of future defense architectures. Companies that navigate ethical, integration, and supply chain challenges while innovating in edge AI and human-machine teaming will emerge as leaders in this rapidly evolving domain.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2023 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 14.5% from 2020-2034 |
| Segmentation |
|
By Application
| By Geography |
|
The global AI in Defense and Security market was valued at USD 10.1 Billion in 2023 and is projected to reach USD 39.1 Billion by 2033, growing at a CAGR of 14.5%.
Machine Learning holds the dominant share of over 40.5% in 2023, primarily due to its widespread use in predictive maintenance, threat detection, and autonomous systems.
Cybersecurity is anticipated to be the fastest-growing application, with spending on AI tools projected to surpass USD 4 Billion by 2024, driven by rising cyber threats.
Key drivers include technological advancements in AI, increased defense spending on AI, and the rising need for enhanced cybersecurity and autonomous systems.
Challenges include ethical and legal concerns regarding autonomous weapons, integration with legacy systems, and data quality issues that can affect AI reliability.
North America holds the largest market share at 37.1% in 2023, driven by substantial U.S. defense investments and a strong AI technology ecosystem.
Defense contractors are acquiring AI startups, forming partnerships with tech firms, and investing in R&D to integrate AI into their product portfolios. For example, 62% of defense executives believe collaboration with commercial AI firms is essential.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Technology Officer | 30% |
| Program Director | 25% |
| Procurement Officer | 25% |
| Military AI Strategist | 20% |
| Company Type | Representation (%) |
|---|---|
| Defense Prime Contractors | 35% |
| AI Software Developers | 25% |
| Hardware Component Suppliers | 20% |
| System Integrators | 15% |
| Government Procurement Agencies | 5% |