Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Defense Artificial Intelligence Market Size, CAGR & 2034 Outlook
Independent Intelligence for decisions that move markets
for Defense Artificial Intelligence Industry | Insight Market Data
for Defense Artificial Intelligence Industry by Offering (Hardware, Software, Services), by Deployment Type (On-premises, Cloud), by Platform (Airborne, Land, Naval, Space), by Technology (Machine Learning, Computer Vision, Natural Language Processing, Big Data Analytics, Other Technologies), by Application (Surveillance and Monitoring, Threat Detection and Prevention, Cybersecurity, Autonomous Systems, Intelligence and Analysis, Battlefield Healthcare, Logistics Management, Training and Simulation), by End Use (Government & Law Enforcement, Defense Contractors), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, India, Japan, South Korea, Australia), by Middle East & Africa (Saudi Arabia, UAE, Israel), by South America (Brazil, Argentina) Forecast 2026-2034
Executive Overview: The Institutionalization of Defense AI
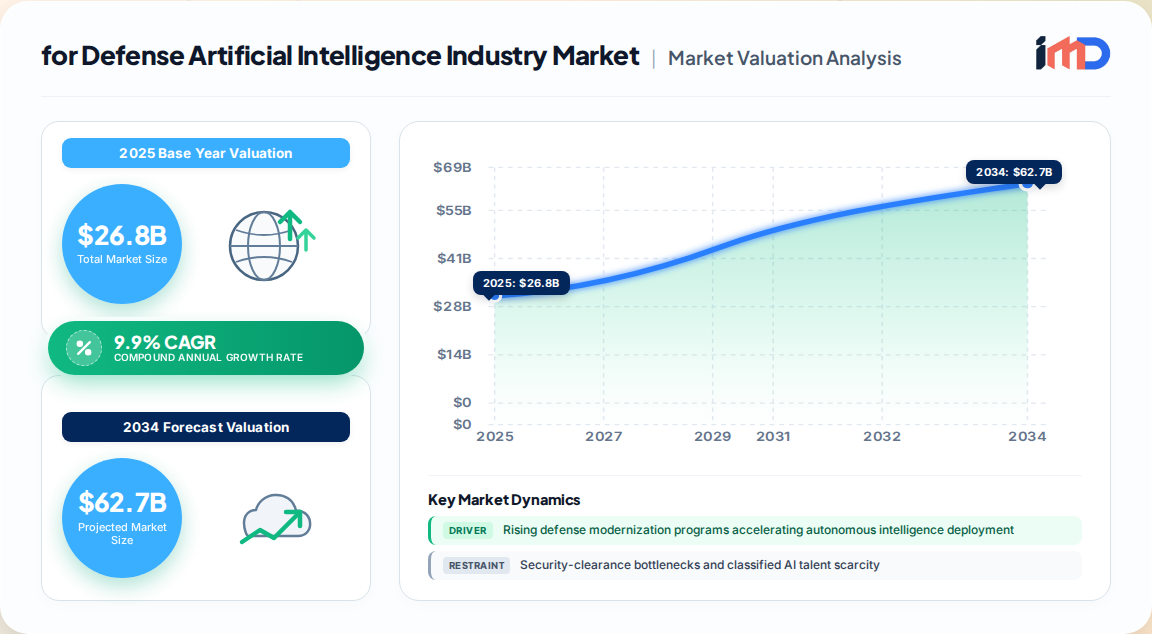
The global Defense Artificial Intelligence market has moved decisively from experimental pilots to contracted operational deployments. Our proprietary bottom-up modeling places the market at USD 26.8 billion in 2025, rising to USD 29.3 billion in 2026 and projected to reach USD 57.1 billion by 2033, reflecting a 9.9% CAGR over the 2026–2033 forecast window. A parallel, broader definition encompassing AI analytics and services across military intelligence, command, and logistics values the opportunity at USD 48.6 billion in 2026, expanding to USD 130.7 billion by 2035 at an 11.5% CAGR.
for Defense Artificial Intelligence Industry Market Size (In Billion)
50.0B
40.0B
30.0B
20.0B
10.0B
0
26.80 B
2025
29.45 B
2026
32.37 B
2027
35.57 B
2028
39.09 B
2029
42.97 B
2030
47.22 B
2031
This growth is not a simple continuation of digitalization. It reflects a structural shift in defense procurement: AI is now being acquired as operational infrastructure, not as a discrete software tool. The strongest demand sits where analytics compress the sensor-to-decision cycle, and where vendors can demonstrate accredited deployment across classified cloud, on-premises, and tactical-edge environments.
North America remains the largest regional market, accounting for 41.4% of global revenue in 2025, supported by statutory AI mandates and multi-year program authorities.
Asia-Pacific is the fastest-growing region, with a projected 12.6% CAGR through 2033, driven by defense modernization in China, India, Japan, and South Korea.
Software and services are outpacing hardware as buyers consolidate around platform agreements that embed data integration and model governance across services and classification levels.
Market Drivers: Budget Cycles, Doctrine, and Data Volume
Three structural forces are expanding the addressable budget for defense AI. First, global military expenditure reached USD 2,887 billion in 2025, the eleventh consecutive annual increase recorded by SIPRI, creating a rising procurement envelope across NATO, Indo-Pacific, and Middle Eastern defense establishments. Second, statutory AI mandates are converting discretionary pilots into durable contract pipelines; the FY25 National Defense Authorization Act authorized over USD 521 million for artificial intelligence and autonomy programs within the U.S. Department of Defense. Third, multi-domain operations doctrine is creating systemic demand for interoperable command networks, as evidenced by NATO's revised AI Strategy directing Allies to accelerate AI adoption roadmaps aligned with six Responsible Use Principles.
The operational driver is data volume. Operational video and telemetry generation has surged, with active conflict zones producing millions of hours of video used to train detection and targeting models. Fusing satellite, drone, and radar feeds using machine learning has demonstrated improved detection accuracy in contested environments, supporting the case for multi-sensor analytics on contested borders.
Driver
Evidence Signal
Forecast Impact
Defense modernization budgets
Global military expenditure of USD 2,887B in 2025 (SIPRI)
Expands addressable budget for ISR, C2, and autonomous systems
Statutory AI mandates
FY25 NDAA authorized USD 521M+ for DoD AI programs
Reduces discretionary risk and sustains annual contract awards
Multi-domain interoperability
NATO revised AI Strategy (July 2024)
Drives multi-year joint platform procurement among Allies
Real-time battlefield data growth
Millions of hours of operational video for model training
Accelerates adoption of automated triage and human-on-the-loop review
Restraints and Challenges: Clearance Bottlenecks and Accreditation Friction
The binding constraint on market growth is not demand but deployment capacity. Security-clearance bottlenecks and classified AI talent scarcity compress vendor scalability and system integration throughput. The U.S. Department of Defense cyber and AI-related civilian vacancy rate remains approximately 15% despite expanded direct-hire authority, reflecting persistent structural shortfalls in cleared AI practitioners. This extends integration timelines, raises deployment costs, and limits effective market access for commercial AI vendors seeking defense revenue.
Regulatory complexity is the second restraint. Complex regulatory frameworks limit operational implementation, particularly where autonomous systems intersect with lethal decision-making. Ethical and legal concerns around privacy, algorithmic bias, and autonomous engagement require careful governance, and governments are establishing guidelines that channel investment toward logistics, maintenance, intelligence fusion, and training use cases that avoid sensitive debates over lethal autonomy. Integration with legacy systems remains a material challenge, as coalition forces require systems that operate across national data boundaries, classification levels, and legacy command networks.
Clearance-constrained scaling: Persistent 15% vacancy rates in cleared AI roles delay classified deployment.
Accreditation thresholds: Buyers consolidate around platforms that can unlock classified and coalition data while meeting accreditation requirements.
Legacy interoperability: Export-control and coalition-operating requirements raise the engineering bar for suppliers.
Segmentation Analysis: Software, Edge, and Autonomy Lead Growth
Our segmentation model tracks the market across offering, deployment, platform, technology, application, and end use. Hardware represented the largest offering share in 2025 at 42.6%, reflecting the compute and sensor infrastructure required to host AI workloads in secure environments. However, services are the fastest-growing component, projected at a 17.10% CAGR through 2031, as buyers shift from one-time prototypes toward recurring integration, data-management, and model-governance work.
On-premises deployment accounted for 55.5% of 2025 revenue, reflecting classification and data-sovereignty requirements that preclude public cloud for many mission workloads. Airborne platforms dominated in 2025, while land systems captured 43.55% of platform revenue, and airborne platforms are projected to advance at a 15.85% CAGR through 2031 as autonomous aircraft and collaborative combat programs mature. Machine learning held the largest technology share in 2025, while big data analytics is projected to grow at a 16.95% CAGR through 2031 as institutions build model-serving platforms and common data layers in accredited environments.
Segment Dimension
2025 Leading Segment
Share / Growth Signal
Offering
Hardware (42.6%)
Services growing at 17.10% CAGR
Deployment
On-premises (55.5%)
Classified workloads anchor on-premises
Platform
Land (43.55%)
Airborne at 15.85% CAGR through 2031
Technology
Machine learning (40.5%)
Big data analytics at 16.95% CAGR
Application
Surveillance & monitoring (24.8–28.8%)
Training & simulation at 16.30% CAGR
End Use
Government & law enforcement
Defense contractors expanding
Regional Outlook: North American Dominance and Indo-Pacific Acceleration
North America accounted for 41.4% of global revenue in 2025, supported by substantial defense budgets, a robust R&D ecosystem, and the presence of leading contractors. The U.S. held the largest country share. Procurement momentum is anchored by multi-year software agreements and defense-cloud deployments, with buyers consolidating around platforms that unlock classified and coalition data while meeting accreditation thresholds. Recent flight test activity has advanced autonomy maturity with collaborative combat aircraft demonstrations that validate mid-flight software handoffs and interoperability between competing control stacks.
for Defense Artificial Intelligence Industry Regional Market Share
Loading chart...
Europe is shaped by NATO interoperability requirements and EU defense initiatives, including a renewed focus on defense innovation. Regional collaboration through NATO and European Space Agency programs, alongside funding for advanced avionics, sustains demand. The competitive landscape includes Airbus, Thales Group, and Leonardo S.p.A., leveraging partnerships to enhance capabilities.
Asia-Pacific is the fastest-growing region at a 12.6% CAGR, driven by rapidly growing defense budgets in China and India, technological innovation in Japan and South Korea, and a push toward localized manufacturing. Government-backed aerospace programs and rising adoption of AI in defense systems amplify growth. The competitive landscape features global giants alongside regional powerhouses such as Hindustan Aeronautics Limited and Mitsubishi Electric.
Middle East, Africa, and South America saw noteworthy progress, with countries such as Saudi Arabia and the UAE leading defense modernization, while Brazil and South Africa focus on commercial aviation and satellite communications. Growth is underpinned by rising defense expenditure, space exploration activities, and adoption of advanced avionics.
Competitive Landscape: Platform Consolidation and Cleared Vendor Ecosystems
The market is moderately concentrated. Lockheed Martin led with over 7.3% market share in 2025, and the top five players—including Northrop Grumman, RTX (Raytheon Technologies), Palantir Technologies, and Booz Allen Hamilton—collectively held 25.1% of the market. Competitive advantage is shifting toward vendors that can bridge commercial AI advances and defense-grade assurance, export-control compliance, and coalition-operating requirements.
Key strategic moves include the October 2025 partnership between Lockheed Martin and Google Public Sector to integrate an AI Factory with advanced generative AI models, signaling deeper collaboration between traditional primes and commercial AI providers. The U.S. Navy's multiyear award for modular unmanned surface vessels validates procurement acceptance of attritable autonomous systems, while enterprise-level agreements for data integration platforms demonstrate consolidation around platform-level providers. Recent solicitations for classified-ready compute clusters indicate continued investment in hardened edge and deployable cloud infrastructure.
The highest-value white space sits at the intersection of edge intelligence and accredited cloud. Programs with a credible path from sensor ingestion to operational decision-making are better positioned to secure larger, longer-duration awards because they address cross-domain integration needs that isolated analytical tools cannot resolve. Generative AI for cleared users—focused on mission planning, training content, and intelligence synthesis under strict governance—represents an early-stage opportunity with significant upside.
Predictive maintenance remains an underpenetrated application with clear ROI, reducing unexpected equipment failures and downtime by forecasting component service needs. Synthetic training environments and battlefield healthcare are projected to expand rapidly, with training and simulation growing at a 16.30% CAGR. Vendors able to adapt commercial AI to defense-grade assurance, export-control, and coalition-operating requirements can capture demand beyond a single service or national customer.
Procurement strategy should prioritize multi-year capability roadmaps over greenfield procurement, as established contract relationships and cleared vendor ecosystems channel incremental budget growth into platform extensions and mission-domain expansions. The 2026–2035 window captures this maturation dynamic, with AI procurement increasingly structured as enterprise agreements rather than discrete pilots.
for Defense Artificial Intelligence Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
for Defense Artificial Intelligence Industry REPORT HIGHLIGHTS
3.4.3. Ethical and legal concerns around autonomous lethal decision-making
3.4.4. Integration complexity with legacy command networks and multi-classification data
3.5. Market Challenges
3.5.1. Persistent ~15% vacancy rate in cleared AI practitioners extends integration timelines
3.5.2. Export-control and coalition-operating requirements raise engineering barriers
3.5.3. Accreditation thresholds constrain deployment of commercial AI advances
3.5.4. Balancing speed of commercial AI innovation with defense-grade assurance
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Offering
5.1.1. Hardware
5.1.2. Software
5.1.3. Services
5.2. Market Analysis, Insights and Forecast - by Deployment Type
5.2.1. On-premises
5.2.2. Cloud
5.3. Market Analysis, Insights and Forecast - by Platform
5.3.1. Airborne
5.3.2. Land
5.3.3. Naval
5.3.4. Space
5.4. Market Analysis, Insights and Forecast - by Technology
5.4.1. Machine Learning
5.4.2. Computer Vision
5.4.3. Natural Language Processing
5.4.4. Big Data Analytics
5.4.5. Other Technologies
5.5. Market Analysis, Insights and Forecast - by Application
5.5.1. Surveillance and Monitoring
5.5.2. Threat Detection and Prevention
5.5.3. Cybersecurity
5.5.4. Autonomous Systems
5.5.5. Intelligence and Analysis
5.5.6. Battlefield Healthcare
5.5.7. Logistics Management
5.5.8. Training and Simulation
5.6. Market Analysis, Insights and Forecast - by End Use
5.6.1. Government & Law Enforcement
5.6.2. Defense Contractors
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Middle East & Africa
5.7.5. South America
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Offering
6.1.1. Hardware
6.1.2. Software
6.1.3. Services
6.2. Market Analysis, Insights and Forecast - by Deployment Type
6.2.1. On-premises
6.2.2. Cloud
6.3. Market Analysis, Insights and Forecast - by Platform
6.3.1. Airborne
6.3.2. Land
6.3.3. Naval
6.3.4. Space
6.4. Market Analysis, Insights and Forecast - by Technology
6.4.1. Machine Learning
6.4.2. Computer Vision
6.4.3. Natural Language Processing
6.4.4. Big Data Analytics
6.4.5. Other Technologies
6.5. Market Analysis, Insights and Forecast - by Application
6.5.1. Surveillance and Monitoring
6.5.2. Threat Detection and Prevention
6.5.3. Cybersecurity
6.5.4. Autonomous Systems
6.5.5. Intelligence and Analysis
6.5.6. Battlefield Healthcare
6.5.7. Logistics Management
6.5.8. Training and Simulation
6.6. Market Analysis, Insights and Forecast - by End Use
6.6.1. Government & Law Enforcement
6.6.2. Defense Contractors
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Offering
7.1.1. Hardware
7.1.2. Software
7.1.3. Services
7.2. Market Analysis, Insights and Forecast - by Deployment Type
7.2.1. On-premises
7.2.2. Cloud
7.3. Market Analysis, Insights and Forecast - by Platform
7.3.1. Airborne
7.3.2. Land
7.3.3. Naval
7.3.4. Space
7.4. Market Analysis, Insights and Forecast - by Technology
7.4.1. Machine Learning
7.4.2. Computer Vision
7.4.3. Natural Language Processing
7.4.4. Big Data Analytics
7.4.5. Other Technologies
7.5. Market Analysis, Insights and Forecast - by Application
7.5.1. Surveillance and Monitoring
7.5.2. Threat Detection and Prevention
7.5.3. Cybersecurity
7.5.4. Autonomous Systems
7.5.5. Intelligence and Analysis
7.5.6. Battlefield Healthcare
7.5.7. Logistics Management
7.5.8. Training and Simulation
7.6. Market Analysis, Insights and Forecast - by End Use
7.6.1. Government & Law Enforcement
7.6.2. Defense Contractors
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Offering
8.1.1. Hardware
8.1.2. Software
8.1.3. Services
8.2. Market Analysis, Insights and Forecast - by Deployment Type
8.2.1. On-premises
8.2.2. Cloud
8.3. Market Analysis, Insights and Forecast - by Platform
8.3.1. Airborne
8.3.2. Land
8.3.3. Naval
8.3.4. Space
8.4. Market Analysis, Insights and Forecast - by Technology
8.4.1. Machine Learning
8.4.2. Computer Vision
8.4.3. Natural Language Processing
8.4.4. Big Data Analytics
8.4.5. Other Technologies
8.5. Market Analysis, Insights and Forecast - by Application
8.5.1. Surveillance and Monitoring
8.5.2. Threat Detection and Prevention
8.5.3. Cybersecurity
8.5.4. Autonomous Systems
8.5.5. Intelligence and Analysis
8.5.6. Battlefield Healthcare
8.5.7. Logistics Management
8.5.8. Training and Simulation
8.6. Market Analysis, Insights and Forecast - by End Use
8.6.1. Government & Law Enforcement
8.6.2. Defense Contractors
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Offering
9.1.1. Hardware
9.1.2. Software
9.1.3. Services
9.2. Market Analysis, Insights and Forecast - by Deployment Type
9.2.1. On-premises
9.2.2. Cloud
9.3. Market Analysis, Insights and Forecast - by Platform
9.3.1. Airborne
9.3.2. Land
9.3.3. Naval
9.3.4. Space
9.4. Market Analysis, Insights and Forecast - by Technology
9.4.1. Machine Learning
9.4.2. Computer Vision
9.4.3. Natural Language Processing
9.4.4. Big Data Analytics
9.4.5. Other Technologies
9.5. Market Analysis, Insights and Forecast - by Application
9.5.1. Surveillance and Monitoring
9.5.2. Threat Detection and Prevention
9.5.3. Cybersecurity
9.5.4. Autonomous Systems
9.5.5. Intelligence and Analysis
9.5.6. Battlefield Healthcare
9.5.7. Logistics Management
9.5.8. Training and Simulation
9.6. Market Analysis, Insights and Forecast - by End Use
9.6.1. Government & Law Enforcement
9.6.2. Defense Contractors
10. South America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Offering
10.1.1. Hardware
10.1.2. Software
10.1.3. Services
10.2. Market Analysis, Insights and Forecast - by Deployment Type
10.2.1. On-premises
10.2.2. Cloud
10.3. Market Analysis, Insights and Forecast - by Platform
10.3.1. Airborne
10.3.2. Land
10.3.3. Naval
10.3.4. Space
10.4. Market Analysis, Insights and Forecast - by Technology
10.4.1. Machine Learning
10.4.2. Computer Vision
10.4.3. Natural Language Processing
10.4.4. Big Data Analytics
10.4.5. Other Technologies
10.5. Market Analysis, Insights and Forecast - by Application
10.5.1. Surveillance and Monitoring
10.5.2. Threat Detection and Prevention
10.5.3. Cybersecurity
10.5.4. Autonomous Systems
10.5.5. Intelligence and Analysis
10.5.6. Battlefield Healthcare
10.5.7. Logistics Management
10.5.8. Training and Simulation
10.6. Market Analysis, Insights and Forecast - by End Use
10.6.1. Government & Law Enforcement
10.6.2. Defense Contractors
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Lockheed Martin
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Northrop Grumman
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. RTX (Raytheon Technologies)
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Palantir Technologies
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Booz Allen Hamilton
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Boeing
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Airbus
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Thales Group
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Leonardo S.p.A.
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Hindustan Aeronautics Limited
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Mitsubishi Electric
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Saronic
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Google Public Sector
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global for Defense Artificial Intelligence Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America for Defense Artificial Intelligence Industry Revenue (Billion), by Offering 2026 & 2034
Figure 3: North America for Defense Artificial Intelligence Industry Revenue Share (%), by Offering 2026 & 2034
Figure 4: North America for Defense Artificial Intelligence Industry Revenue (Billion), by Deployment Type 2026 & 2034
Figure 5: North America for Defense Artificial Intelligence Industry Revenue Share (%), by Deployment Type 2026 & 2034
Figure 6: North America for Defense Artificial Intelligence Industry Revenue (Billion), by Platform 2026 & 2034
Figure 7: North America for Defense Artificial Intelligence Industry Revenue Share (%), by Platform 2026 & 2034
Figure 8: North America for Defense Artificial Intelligence Industry Revenue (Billion), by Technology 2026 & 2034
Figure 9: North America for Defense Artificial Intelligence Industry Revenue Share (%), by Technology 2026 & 2034
Figure 10: North America for Defense Artificial Intelligence Industry Revenue (Billion), by Application 2026 & 2034
Figure 11: North America for Defense Artificial Intelligence Industry Revenue Share (%), by Application 2026 & 2034
Figure 12: North America for Defense Artificial Intelligence Industry Revenue (Billion), by End Use 2026 & 2034
Figure 13: North America for Defense Artificial Intelligence Industry Revenue Share (%), by End Use 2026 & 2034
Figure 14: North America for Defense Artificial Intelligence Industry Revenue (Billion), by Country 2026 & 2034
Figure 15: North America for Defense Artificial Intelligence Industry Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe for Defense Artificial Intelligence Industry Revenue (Billion), by Offering 2026 & 2034
Figure 17: Europe for Defense Artificial Intelligence Industry Revenue Share (%), by Offering 2026 & 2034
Figure 18: Europe for Defense Artificial Intelligence Industry Revenue (Billion), by Deployment Type 2026 & 2034
Figure 19: Europe for Defense Artificial Intelligence Industry Revenue Share (%), by Deployment Type 2026 & 2034
Figure 20: Europe for Defense Artificial Intelligence Industry Revenue (Billion), by Platform 2026 & 2034
Figure 21: Europe for Defense Artificial Intelligence Industry Revenue Share (%), by Platform 2026 & 2034
Figure 22: Europe for Defense Artificial Intelligence Industry Revenue (Billion), by Technology 2026 & 2034
Figure 23: Europe for Defense Artificial Intelligence Industry Revenue Share (%), by Technology 2026 & 2034
Figure 24: Europe for Defense Artificial Intelligence Industry Revenue (Billion), by Application 2026 & 2034
Figure 25: Europe for Defense Artificial Intelligence Industry Revenue Share (%), by Application 2026 & 2034
Figure 26: Europe for Defense Artificial Intelligence Industry Revenue (Billion), by End Use 2026 & 2034
Figure 27: Europe for Defense Artificial Intelligence Industry Revenue Share (%), by End Use 2026 & 2034
Figure 28: Europe for Defense Artificial Intelligence Industry Revenue (Billion), by Country 2026 & 2034
Figure 29: Europe for Defense Artificial Intelligence Industry Revenue Share (%), by Country 2026 & 2034
Figure 30: Asia Pacific for Defense Artificial Intelligence Industry Revenue (Billion), by Offering 2026 & 2034
Figure 31: Asia Pacific for Defense Artificial Intelligence Industry Revenue Share (%), by Offering 2026 & 2034
Figure 32: Asia Pacific for Defense Artificial Intelligence Industry Revenue (Billion), by Deployment Type 2026 & 2034
Figure 33: Asia Pacific for Defense Artificial Intelligence Industry Revenue Share (%), by Deployment Type 2026 & 2034
Figure 34: Asia Pacific for Defense Artificial Intelligence Industry Revenue (Billion), by Platform 2026 & 2034
Figure 35: Asia Pacific for Defense Artificial Intelligence Industry Revenue Share (%), by Platform 2026 & 2034
Figure 36: Asia Pacific for Defense Artificial Intelligence Industry Revenue (Billion), by Technology 2026 & 2034
Figure 37: Asia Pacific for Defense Artificial Intelligence Industry Revenue Share (%), by Technology 2026 & 2034
Figure 38: Asia Pacific for Defense Artificial Intelligence Industry Revenue (Billion), by Application 2026 & 2034
Figure 39: Asia Pacific for Defense Artificial Intelligence Industry Revenue Share (%), by Application 2026 & 2034
Figure 40: Asia Pacific for Defense Artificial Intelligence Industry Revenue (Billion), by End Use 2026 & 2034
Figure 41: Asia Pacific for Defense Artificial Intelligence Industry Revenue Share (%), by End Use 2026 & 2034
Figure 42: Asia Pacific for Defense Artificial Intelligence Industry Revenue (Billion), by Country 2026 & 2034
Figure 43: Asia Pacific for Defense Artificial Intelligence Industry Revenue Share (%), by Country 2026 & 2034
Figure 44: Middle East & Africa for Defense Artificial Intelligence Industry Revenue (Billion), by Offering 2026 & 2034
Figure 45: Middle East & Africa for Defense Artificial Intelligence Industry Revenue Share (%), by Offering 2026 & 2034
Figure 46: Middle East & Africa for Defense Artificial Intelligence Industry Revenue (Billion), by Deployment Type 2026 & 2034
Figure 47: Middle East & Africa for Defense Artificial Intelligence Industry Revenue Share (%), by Deployment Type 2026 & 2034
Figure 48: Middle East & Africa for Defense Artificial Intelligence Industry Revenue (Billion), by Platform 2026 & 2034
Figure 49: Middle East & Africa for Defense Artificial Intelligence Industry Revenue Share (%), by Platform 2026 & 2034
Figure 50: Middle East & Africa for Defense Artificial Intelligence Industry Revenue (Billion), by Technology 2026 & 2034
Figure 51: Middle East & Africa for Defense Artificial Intelligence Industry Revenue Share (%), by Technology 2026 & 2034
Figure 52: Middle East & Africa for Defense Artificial Intelligence Industry Revenue (Billion), by Application 2026 & 2034
Figure 53: Middle East & Africa for Defense Artificial Intelligence Industry Revenue Share (%), by Application 2026 & 2034
Figure 54: Middle East & Africa for Defense Artificial Intelligence Industry Revenue (Billion), by End Use 2026 & 2034
Figure 55: Middle East & Africa for Defense Artificial Intelligence Industry Revenue Share (%), by End Use 2026 & 2034
Figure 56: Middle East & Africa for Defense Artificial Intelligence Industry Revenue (Billion), by Country 2026 & 2034
Figure 57: Middle East & Africa for Defense Artificial Intelligence Industry Revenue Share (%), by Country 2026 & 2034
Figure 58: South America for Defense Artificial Intelligence Industry Revenue (Billion), by Offering 2026 & 2034
Figure 59: South America for Defense Artificial Intelligence Industry Revenue Share (%), by Offering 2026 & 2034
Figure 60: South America for Defense Artificial Intelligence Industry Revenue (Billion), by Deployment Type 2026 & 2034
Figure 61: South America for Defense Artificial Intelligence Industry Revenue Share (%), by Deployment Type 2026 & 2034
Figure 62: South America for Defense Artificial Intelligence Industry Revenue (Billion), by Platform 2026 & 2034
Figure 63: South America for Defense Artificial Intelligence Industry Revenue Share (%), by Platform 2026 & 2034
Figure 64: South America for Defense Artificial Intelligence Industry Revenue (Billion), by Technology 2026 & 2034
Figure 65: South America for Defense Artificial Intelligence Industry Revenue Share (%), by Technology 2026 & 2034
Figure 66: South America for Defense Artificial Intelligence Industry Revenue (Billion), by Application 2026 & 2034
Figure 67: South America for Defense Artificial Intelligence Industry Revenue Share (%), by Application 2026 & 2034
Figure 68: South America for Defense Artificial Intelligence Industry Revenue (Billion), by End Use 2026 & 2034
Figure 69: South America for Defense Artificial Intelligence Industry Revenue Share (%), by End Use 2026 & 2034
Figure 70: South America for Defense Artificial Intelligence Industry Revenue (Billion), by Country 2026 & 2034
Figure 71: South America for Defense Artificial Intelligence Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Offering 2020 & 2034
Table 2: Global for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Deployment Type 2020 & 2034
Table 3: Global for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Platform 2020 & 2034
Table 4: Global for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Technology 2020 & 2034
Table 5: Global for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 6: Global for Defense Artificial Intelligence Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 7: Global for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Offering 2020 & 2034
Table 9: North America for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Deployment Type 2020 & 2034
Table 10: North America for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Platform 2020 & 2034
Table 11: North America for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Technology 2020 & 2034
Table 12: North America for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 13: North America for Defense Artificial Intelligence Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 14: North America for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Canada for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: Mexico for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: Europe for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Offering 2020 & 2034
Table 19: Europe for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Deployment Type 2020 & 2034
Table 20: Europe for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Platform 2020 & 2034
Table 21: Europe for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Technology 2020 & 2034
Table 22: Europe for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 23: Europe for Defense Artificial Intelligence Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 24: Europe for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 25: Germany for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: UK for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: France for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: Italy for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Asia Pacific for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Offering 2020 & 2034
Table 30: Asia Pacific for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Deployment Type 2020 & 2034
Table 31: Asia Pacific for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Platform 2020 & 2034
Table 32: Asia Pacific for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Technology 2020 & 2034
Table 33: Asia Pacific for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 34: Asia Pacific for Defense Artificial Intelligence Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 35: Asia Pacific for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 36: China for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 37: India for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: Japan for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: South Korea for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: Australia for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: Middle East & Africa for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Offering 2020 & 2034
Table 42: Middle East & Africa for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Deployment Type 2020 & 2034
Table 43: Middle East & Africa for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Platform 2020 & 2034
Table 44: Middle East & Africa for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Technology 2020 & 2034
Table 45: Middle East & Africa for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 46: Middle East & Africa for Defense Artificial Intelligence Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 47: Middle East & Africa for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 48: Saudi Arabia for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 49: UAE for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 50: Israel for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 51: South America for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Offering 2020 & 2034
Table 52: South America for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Deployment Type 2020 & 2034
Table 53: South America for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Platform 2020 & 2034
Table 54: South America for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Technology 2020 & 2034
Table 55: South America for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 56: South America for Defense Artificial Intelligence Industry Revenue Billion Forecast, by End Use 2020 & 2034
Table 57: South America for Defense Artificial Intelligence Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 58: Brazil for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 59: Argentina for Defense Artificial Intelligence Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the Defense Artificial Intelligence market?
Our proprietary modeling values the global Defense Artificial Intelligence market at USD 26.8 billion in 2025, rising to USD 29.3 billion in 2026. The market is projected to reach USD 57.1 billion by 2033, reflecting a 9.9% CAGR over the 2026–2033 forecast window.
2Which region dominates the Defense Artificial Intelligence market?
North America is the largest regional market, accounting for 41.4% of global revenue in 2025, supported by substantial defense budgets and statutory AI mandates. Asia-Pacific is the fastest-growing region, with a projected 12.6% CAGR through 2033.
3What are the key drivers of defense AI adoption?
Global military expenditure reached USD 2,887 billion in 2025 per SIPRI, creating a rising procurement envelope. The FY25 National Defense Authorization Act authorized over USD 521 million for DoD AI programs, and NATO's revised AI Strategy is driving multi-year interoperability procurement among Allies.
4Who are the leading companies in the Defense Artificial Intelligence market?
Lockheed Martin led with over 7.3% market share in 2025. The top five players—Lockheed Martin, Northrop Grumman, RTX, Palantir Technologies, and Booz Allen Hamilton—collectively held 25.1% of the market.
5What is the largest application segment for defense AI?
Surveillance and monitoring led with 24.8–28.8% revenue share in 2025, driven by AI-enabled data fusion, target recognition, and command-and-control systems. Training and simulation is the fastest-growing application, projected at a 16.30% CAGR through 2031.
6What restraints limit the Defense Artificial Intelligence market?
Security-clearance bottlenecks and classified AI talent scarcity constrain vendor scalability; the U.S. DoD cyber and AI-related civilian vacancy rate remains approximately 15%. Complex regulatory frameworks, ethical concerns, and legacy system integration also limit operational implementation.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conduct 70–80% of our research through primary engagement, including structured interviews with program officers, acquisition specialists, and technical leads across defense ministries and prime contractors.
Interviews are carried out with 4–5 specific company types: defense prime contractors, defense AI software and analytics vendors, autonomous systems and UAV manufacturers, secure cloud and edge compute providers, and systems integrators.
Stakeholder interviews target Procurement Director, Chief AI Officer, Program Executive Officer (PEO), and Mission Systems Architect roles to capture both budget authority and technical validation.
We engage with 3–4 recognized regulatory and standards bodies, including NATO Communications and Information Agency (NCIA), U.S. Department of Defense Chief Digital and Artificial Intelligence Office (CDAO), European Defence Agency (EDA), and NIST for AI risk management frameworks.
Primary interviews are triangulated with budget documents and program-of-record data to validate vendor revenue attribution.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
35%
Chief AI Officer
25%
Program Executive Officer
22%
Mission Systems Architect
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Defense Prime Contractors
30%
Defense AI Software & Analytics Vendors
25%
Autonomous Systems & UAV Manufacturers
20%
Secure Cloud & Edge Compute Providers
15%
Systems Integrators
10%
Secondary Research & Industry Benchmarking
We maintain a 20–30% secondary research allocation, drawing on official multilateral and governmental sources such as SIPRI (sipri.org), OECD STIP Compass (stip.oecd.org), U.S. Congressional budget justification documents (congress.gov), and NATO (nato.int).
Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook are used for vendor financial benchmarking and contract award tracking.
We monitor official .gov and .org procurement portals, including the System for Award Management (SAM.gov) and the European Defence Fund project database.
All secondary benchmarks are cross-checked against our primary interview findings to prevent single-source bias.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation. Top-down models use global defense AI expenditure envelopes; bottom-up models build from program-level budgets and vendor revenue.
Bottom-up calculation uses 4 specific quantitative metrics: (1) AI-attributable share of defense modernization budgets, (2) contract award values for AI programs, (3) platform unit shipments with embedded AI compute, and (4) cleared AI deployment headcount as a capacity proxy.
Segment-level estimates are reconciled against vendor-reported defense revenue and program-of-record funding lines to derive market shares.
Regional models incorporate classification-level deployment capacity and accreditation throughput as supply-side constraints on demand realization.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through multi-level triangulation and expert review.
Every report is updated to the date of purchase, incorporating the latest contract awards, budget authorizations, and policy changes.
A senior analyst panel reviews all market sizing and forecast assumptions prior to publication.
Variance between primary interview signals and secondary benchmarks is flagged and reconciled before final forecast sign-off.
Related Reports
Military Grade Steel Market valued at USD 16 Billion in 2024, growing at 4.2% CAGR to reach USD 25 Billion by 2035. Defense modernization drives demand.
Nov 2026|267 pages
$2900.00
UAV Navigation Systems Market worth USD 11.28 billion in 2025, growing at 15.97% CAGR to reach USD 23.67 billion by 2030. In-depth analysis of trends, drivers & suppliers.
Nov 2026|185 pages
$2900.00
Military UGV market at USD 2.11 billion in 2026, rising at 7.8% CAGR to USD 3.08 billion by 2031. Explore segments, regional outlook and procurement trends.
Nov 2026|188 pages
$2900.00
AI in Defense and Security Market to reach USD 39.1 Billion by 2033, growing at a 14.5% CAGR. Explore technology, application, and regional insights.