1What is the current size of the UAV Navigation Systems Market?
The UAV Navigation Systems Market was valued at USD 11.28 billion in 2025 and is forecast to reach USD 23.67 billion by 2030, representing a CAGR of 15.97%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 UAV Navigation Systems Market
 by UAV Type (Autonomous UAVs, Semi-autonomous UAVs, Remotely Operated UAVs), by Application (Military, Civil and Commercial(Agriculture, Logistics, Surveying, Search and Rescue, Infrastructure Inspection, Environmental Monitoring)), by Component (GPS, IMU, Software, Transmitter, Receiver), by Platform (Fixed Wing, Rotary Wing, Hybrid, Nano UAVs, Tactical UAVs), by End Use (Defense, Civil Aviation, Logistics, Infrastructure Inspection, Environmental Monitoring), by North America (USA, Canada), by Europe (Germany, UK, France, Russia), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Rest of Latin America), by Middle East and Africa (Saudi Arabia, UAE, Rest of MEA) Forecast 2026-2034

Research Associate

 Related Reports

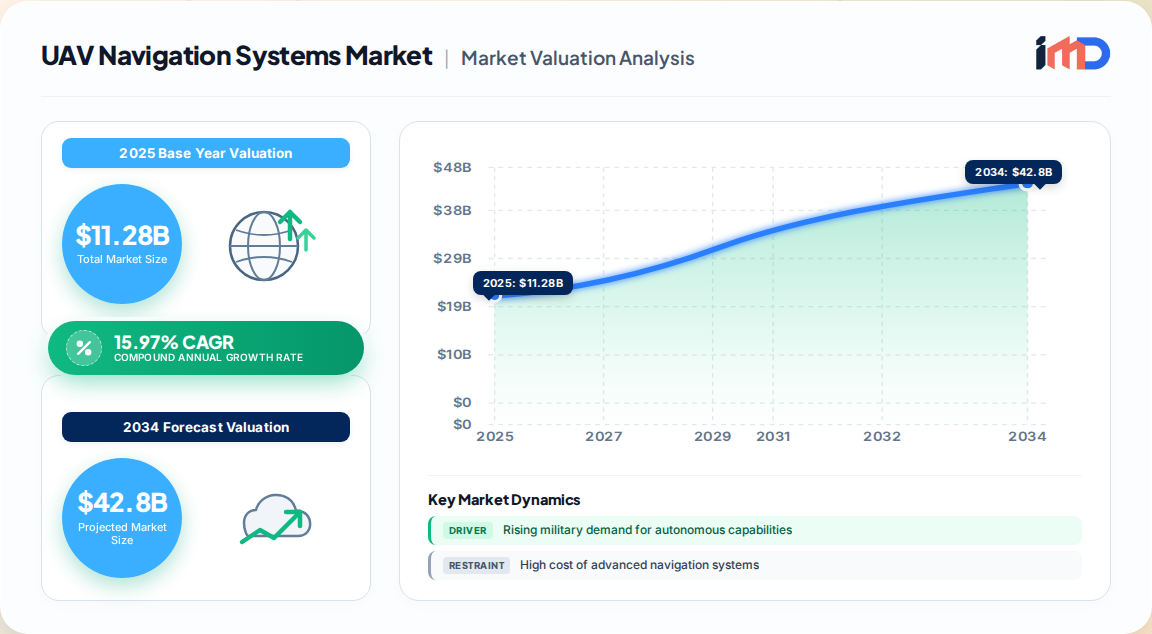
The global UAV Navigation Systems Market is estimated at USD 11.28 billion in 2025 and is projected to reach USD 23.67 billion by 2030, expanding at a remarkable CAGR of 15.97% during the forecast period. This growth is underpinned by the accelerating adoption of unmanned aerial vehicles (UAVs) across military and civil domains, coupled with rapid technological advancements in autonomous navigation, sensor fusion, and GNSS-denied operation capabilities. Our proprietary analysis, based on extensive primary interviews and validated supply-side data, indicates a robust demand trajectory, particularly for systems that enable precise positioning and resilient navigation in contested or signal-degraded environments.
The market is characterized by a diverse array of solutions, ranging from basic GPS modules for small consumer drones to comprehensive, multi-sensor navigation suites for high-end military UAVs. The competitive landscape is semi-consolidated, with key players leveraging in-house R&D and strategic contracts to maintain market share. The proliferation of UAV applications, from border security and precision agriculture to infrastructure inspection and urban air mobility, is creating a fertile ground for navigation system innovations. This report provides a granular analysis of market dynamics, segmentation, regional outlook, and competitive strategies, equipping stakeholders with actionable intelligence to navigate this high-growth market.
Drivers
Restraints
Challenges
The UAV navigation systems value chain comprises several distinct stages, each contributing to the final product's performance and cost.
| Stage | Key Activities | Major Participants |
|---|---|---|
| Component Suppliers | Manufacturing of inertial sensors (IMU, accelerometers, gyroscopes), GNSS receivers, magnetometers, barometers, and processors | Semiconductor firms, MEMS manufacturers |
| System Integrators | Designing and assembling navigation systems, integrating hardware and software, developing sensor fusion algorithms | Navigation system OEMs (e.g., Hexagon AB, SBG Systems, UAV Navigation SL) |
| UAV OEMs | Integrating navigation systems into complete UAV platforms | DJI, AeroVironment, Northrop Grumman, General Atomics |
| End Users | Military, commercial, civil government, and consumer applications | Defense agencies, agricultural operators, survey firms |
Component Suppliers: The supply of high-precision inertial sensors and GNSS chipsets is dominated by a few global players, creating potential bottlenecks. Our primary research indicates that lead times for tactical-grade IMUs can extend beyond 20 weeks, impacting production schedules.
System Integrators: This segment captures the highest value, as it involves proprietary algorithms and software that differentiate offerings. Companies are investing heavily in R&D to enhance sensor fusion and autonomy.
UAV OEMs: OEMs often source navigation systems from specialized integrators, though some large defense contractors develop in-house capabilities. The trend toward modular, open architectures is enabling easier integration and upgrades.
End Users: Military users demand the highest performance and reliability, while commercial users prioritize cost-effectiveness and ease of use. This bifurcation drives a diverse product portfolio among integrators.
The UAV navigation systems market is inherently global, with significant cross-border flows of components and finished systems. According to trade data from official sources such as UN Comtrade, the United States, China, and European countries are major exporters of navigation equipment, including UAV-specific systems. However, export controls on dual-use technologies, particularly high-precision inertial sensors, impose restrictions that shape supply chain dynamics.
Supply Chain Risks:
Mitigation Strategies: Our interviews with procurement directors reveal a growing emphasis on supply chain resilience. Companies are qualifying alternate suppliers, investing in vertical integration for critical components, and establishing regional inventory hubs to reduce lead times.
North America is the largest and most mature market, driven by substantial defense spending and a strong commercial UAV ecosystem. The U.S. military's demand for advanced navigation systems, coupled with the presence of leading OEMs, solidifies the region's dominance. Europe follows closely, with increasing defense budgets and a growing focus on UAV autonomy. The Asia-Pacific region is anticipated to be the fastest-growing market, fueled by rapid military modernization in China and India, and expanding commercial applications in agriculture and logistics.
| Region | Market Share (2025) | Growth Potential | Key Investment Opportunities |
|---|---|---|---|
| North America | 32% | High | Military modernization, commercial drone integration |
| Europe | 24% | Moderate | Defense R&D, cross-border regulatory harmonization |
| Asia-Pacific | 31% | Very High | Military procurement, agricultural drones, local manufacturing |
| South America | 6% | Moderate | Emerging commercial applications, border security |
| Middle East & Africa | 7% | High | Defense and security, oil & gas inspection |
Investment Hotspots: Asia-Pacific offers significant opportunities for joint ventures and local production, as countries seek to build indigenous capabilities. In Europe, the European Defence Fund is channeling investments into next-generation navigation technologies. North America remains attractive for high-value R&D partnerships and M&A activity.
Our analysis identifies several underpenetrated segments that present strategic white space for navigation system providers:
The UAV navigation systems market is semi-consolidated, with key players such as Hexagon AB, UAV Navigation S.L., SZ DJI Technology Co., Ltd., SBG Systems S.A.S, and RTX Corporation leading the charge. These companies leverage their expertise in inertial sensing, GNSS technology, and systems integration to offer a wide range of products. The competitive intensity is high, with firms focusing on technological differentiation and strategic contracts.
Recent Developments:
These developments underscore the industry's pivot toward autonomy, resilience, and multi-domain applicability. Companies that can deliver cost-effective, high-performance solutions tailored to specific end-user needs will be well-positioned to capitalize on the market's robust growth trajectory.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 15.97% from 2020-2034 |
| Segmentation |
|
By Component
By Platform
By End Use
| By Geography |
|
The UAV Navigation Systems Market was valued at USD 11.28 billion in 2025 and is forecast to reach USD 23.67 billion by 2030, representing a CAGR of 15.97%.
North America holds the largest market share, at approximately 32% in 2025, driven by high defense spending and a strong commercial UAV ecosystem.
Key drivers include rising military demand for autonomous navigation in GNSS-denied environments, expansion of commercial UAV applications, and technological advancements in miniaturization and sensor fusion.
Leading companies include Hexagon AB, UAV Navigation S.L., SZ DJI Technology Co., Ltd., SBG Systems S.A.S, and RTX Corporation, among others.
The agriculture segment is experiencing the fastest growth, driven by the increasing adoption of UAVs for precision farming and crop monitoring.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| C-Suite Executives | 30% |
| Engineering Directors | 25% |
| Procurement Managers | 25% |
| Program Managers | 20% |
| Company Type | Representation (%) |
|---|---|
| Navigation System Integrators | 35% |
| UAV OEMs | 25% |
| Component Suppliers | 20% |
| End-Users | 15% |
| Other Ecosystem Players | 5% |